
Corruption and Mining: Hidden Harms to People and Planet

As demand for transition minerals grows, the hidden costs of corruption are mounting. Decisions about mining — whether it should happen, where and how — are too often distorted by vested interests, undermining safeguards for communities, Indigenous Peoples and the environment.
This video highlights the findings of our joint briefing, Digging Into the Problem, which explores how corruption fuels socioenvironmental and human rights harms in mining, and what must change to build responsible and secure supply chains.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Delayed Regulations Hurting Growth Of Uganda’s Mining Sector
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Illegal Gold Mining: A Growing Threat to the Peruvian Amazon

Illegal gold mining has become one of the biggest threats to the Peruvian Amazon and important region to the world because of its role in regulating the climate and its extraordinary biodiversity. This illicit activity is expanding rapidly across several departments in the region, including Loreto, Madre de Dios, Amazonas, Huánuco and San Martín, and has already affected more than 30 districts in the country.
Distinguishing informal mining —which is undergoing a legal formalization process, from illegal mining—which operates entirely outside the law, often operating in prohibited areas using toxic substances and disregarding environmental and safety regulations—is crucial.
A highly profitable but deeply destructive activity
Illegal gold extraction is an extremely lucrative business. A single dredge can generate over USD 135,000 per month, which explains the rapid growth of this illicit trade. However, behind this profitability lies a trail of increasingly severe environmental, social, cultural and economic destruction.
In recent years, the situation has particularly worsened in Loreto, Peru’s largest department, whose geography facilitates the expansion of illegal mining along its rivers. While oil extraction was historically the main economic driver in Loreto, illegal mining has shown steady growth, fueled by rising gold prices, weakened territorial control and unclear formalization policies.
Today, much of this activity is concentrated in the Nanay River basin, one of Loreto’s five major watersheds and the main water source for its capital, Iquitos. By the end of 2024, 210 dredges were operating there out of the 280 identified across the department.
Criminal networks and weakened state control
Illegal mining in Loreto is not an isolated activity. It is closely linked to broader criminal networks and other illegal economies controlled by transnational criminal organizations. These groups influence public decision-making through political pressure, media manipulation and corruption.
Between 2021 and 2024, 25 legislative bills related to informal mining were submitted, 23 of which promoted the deregulation of the sector and weakened the state's ability to control it. While Loreto has not yet experienced full state capture, there are growing concerns that certain private interests are shaping public policies to their advantage.
Impact on communities
The expansion of illegal mining impacts local populations and Indigenous communities directly. While some communities maintain effective territorial control and denounce illegal activities, others have become involved, either by providing labor or by offering support services.
This creates internal tension, weakens social cohesion and fosters economic dependence on illicit activities.
An urgent challenge, a possible opportunity
Loreto faces a significant challenge. However, there is still an opportunity to reverse the situation and strengthen governance across its territories. This requires firm commitment from the Government, national institutions, clarity in formalization policies, and substantial improvements to monitoring and enforcement mechanisms.
The future of Loreto—and of the Peruvian Amazon—must be based on sustainable development that respects life, the rights of communities and the integrity of ecosystems.
Amazonia: challenges and threats
Would you like to learn more about the extraction of hydrocarbons and the illegal mining of gold in the Peruvian Amazon?
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Six Keys to Unlocking Equitable Value Addition in Mining

Key messages
- Governments and civil society actors in low- and middle-income mineral-producing countries are calling for more domestic value addition to boost exports, create jobs and provide inputs for their economies. Governments of consumer countries and multistakeholder initiatives are also acknowledging the inequity in global mineral value chains caused by the limited value addition in producing countries.
- The keys to translating this recent focus into viable value addition projects that meaningfully benefit people in producing countries are:
- Governments should clearly define their strategic objectives, which should be specific to individual minerals and stages of the value chain, and based on national development plans, economic feasibility, market outlook and rigorous cost-benefit analysis.
- Governments should place the principle of doing no harm at the core of their value addition strategies, with moving along the value chain not coming at the expense of environmental and social wellbeing.
- Governments should tailor fiscal, industrial and trade policy mechanisms to their value addition strategies, with a consistent focus on equitable distribution of benefits.
- Governments and companies should address the corruption risks associated with value addition, including those related to policy capture, licensing and permitting, financial incentives, infrastructure development and socio-environmental harms.
- Development partners and consumer country governments should provide financial and technical assistance, while ensuring that this assistance is not undermined by other support that inequitably benefits their own industries.
- Governments should ensure a transparent approach involving citizens at every step. Accountability actors should evaluate the plans of government and companies.
Introduction
Governments and civil society actors in low- and middle-income mineral-producing countries are calling for more domestic value addition of their minerals to increase export revenues, generate jobs and support development of other sectors.
Historically, minerals have typically been extracted and exported with little processing from low- and middle-income countries (except for China). This imbalance has limited the benefits that the mining sector has generated for people in producer countries.
Producer countries have therefore long prioritized moving along the value chain to undertake mineral processing and the manufacturing of semi-finished and finished products. Many countries increased value addition ambitions in the past couple of decades. Expectation of a transition mineral boom has further reinforced this trend. In a 2023 survey by the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development, more governments named value addition as the key driver for their critical mineral strategy than any other factor.
Value addition also occupies an important place in the broader rhetoric around mining in the context of energy transition. For example, the United States-initiated Mineral Security Partnership (MSP)—a collaboration of primarily consumer countries aiming to catalyze public and private investment in supply chains and reduce their dependence on China—has committed to support only projects that promote local value addition. Multistakeholder initiatives, such as the United Nations Secretary-General’s Panel on Critical Energy Transition Minerals (“UNSG CETM panel”), have also identified the importance of low- and middle-income countries moving along the value chain for economic equity. The World Bank has launched the Resilient and Inclusive Supply-Chain Enhancement (RISE) Partnership, with initial funding from Japan, to support low- and middle-countries in this area.
This international recognition is likely a result of various factors. These factors include geopolitical competition, with consumer countries and companies competing for access to minerals by offering more benefits to producer countries; a growing realization that value addition is important for the social license to operate and that this social license is critical for ensuring secure, undisrupted supply; and a genuine recognition that “this time must be different” and the inequities that have historically characterized the mining sector cannot be repeated.
This heightened focus is welcome and overdue, and can help push things forward. However, it can also create unrealistic “hype”, increasing the likelihood of value addition being pursued for political rather than socioeconomic gains, and leading to unsuccessful or counter-productive policy making. Translating this focus into value addition projects that provide meaningful benefits to people in producer countries will require clearer strategy, reforms of policies and practices by a range of actors, and changes in public awareness.
As part of our broader work on minerals governance, NRGI is committed to supporting low- and middle-income countries to maximize economic benefits, including through equitable value addition. We continue to research and develop ideas in this area, which will enable us to contribute to initiatives such as the UNSG CETM panel actionable recommendation 1 on benefit sharing, value addition and economic diversification.
Below are six keys to unlock equitable value addition, building on work we and others have done in this area. We hope such a framework can help stakeholders, including governments and civil society in low- and middle-income producer countries, to soberly assess value addition plans and rhetoric and set parameters for taking forward value addition ambitions.
1. Define a clear strategy based on the national development plan, economic feasibility, market outlook and rigorous cost-benefit analysis
The term “value addition” is used inconsistently. Governments, among others, use the term to describe a variety of goals and processes, for which the feasibility and benefits differ considerably between countries and value chains. Yet, it is not uncommon for strategy and policy documents to reference value addition ambitions in vague terms that take a blanket approach to a country’s mining sector. (Skeptics who reflexively write off the chances of an increase in mineral value addition in low and middle-income countries often similarly lack nuance.)
Governments should evaluate whether value addition is the most effective strategy to reach national development goals. To do this, they should clearly define their strategic objectives. These objectives should be specific to individual minerals and stages of the value chain, and based on economic feasibility, market outlook and rigorous cost-benefit analysis. This clarity is critical for informing government decision-making on the amount of political capital, time and money to spend, trade-offs to accept, and risks to take in attempting to progressively move along the value chain—and which value chains, and parts of these chains, to pursue.
Articulate goals
Governments often target value addition in pursuit of one or more goals. They aim to create jobs; strengthen the public finances through higher government revenues, more foreign exchange and less exposure to commodity market volatility; support development of other sectors (including for diversification purposes) through cheaper inputs, and the transfer of knowledge and skills; improve infrastructure; or support social development in the locality of mining and value addition operations. Governments may also have geopolitical motivations, such as reducing their dependence on other countries or increasing their ability to influence others.
The likelihood of achieving these goals depends on a range of factors which are usually specific to the mineral and the stage of the value chain that is targeted. For example, in the nickel value chain the nickel ore price makes up only 40 percent of the price of mixed hydroxide precipitate (one of the possible next stages in the nickel value chain).1 So for a country such as Indonesia, nickel processing is conducive for achieving a goal of greater government revenue since doing so can add 60 percent of value to the product being taxed in-country. However, this is not the same for all minerals. For example, Indonesian plans to move along the copper value chain and process more copper concentrate into copper cathodes will not yield the same government revenue outcome given that processing copper into cathodes tends to only add 4-6 percent of value.
Similarly, how far along the value chain a country can move will impact whether some goals, such as stimulating the development of other sectors, are likely to be achieved. For example, the Democratic Republic of the Congo (DRC) increasing copper refining may not, on its own, be a significant catalyst for the development of other sectors given that the know-how utilized in refining has limited transferability to other potential economic activity. However, if the country can go further along the value chain and start large-scale manufacturing of products such as copper wires and rods, it would not only result in inputs for other sectors but also the development of know-how that could enable entry into other forms of manufacturing.
Moving several stages along a value chain takes time. China has taken several decades to progress along the value chains it dominates today. Governments may accept limited payoffs from initial measures if these develop capabilities that enable subsequent moves with greater payoffs. However, to ensure optimal decision-making, governments must clearly define this long-term vision from the start.
Clear goals are therefore critical to inform assessment of whether and how the envisaged value addition can achieve them, and how that achievement would support the national development plan.
Assess feasibility
Governments must base their value addition strategy on a clear-eyed view of their country’s current and longer-term potential comparative advantage in a given value chain, and the feasibility of moving along it if this advantage does not exist. Whether a country has a comparative advantage will determine its ability to attract investment. If the government decides to invest public resources or provide incentives, it will determine the ability of new activity to be competitive and therefore sustainable without sustained government support. For example, in the absence of clear competitive advantage, most of the gold refineries constructed in Ghana are lying largely idle due to a combination of profitability constraints. In Australia, the government has had to provide subsidies for several decades to keep the country’s aluminum smelters operating.
The economics of processing certain minerals make it likely that some value addition will occur at or near the mine site even without a significant government push to do so.2 However, as many countries have already experienced, proximity to mineral deposits plays only a small role in determining the location of stages in value chains. A country’s competitiveness further along a value chain depends on multiple factors. These factors, and their importance, depend on the mineral, value chain and stage of the value chain. For example, Figure 1 sets out some of the drivers that determine competitiveness at different stages of the automotive battery value chain.
Figure 1. Comparative advantage drivers and potential competitiveness of low- and middle-income producer countries across the automotive battery value chain
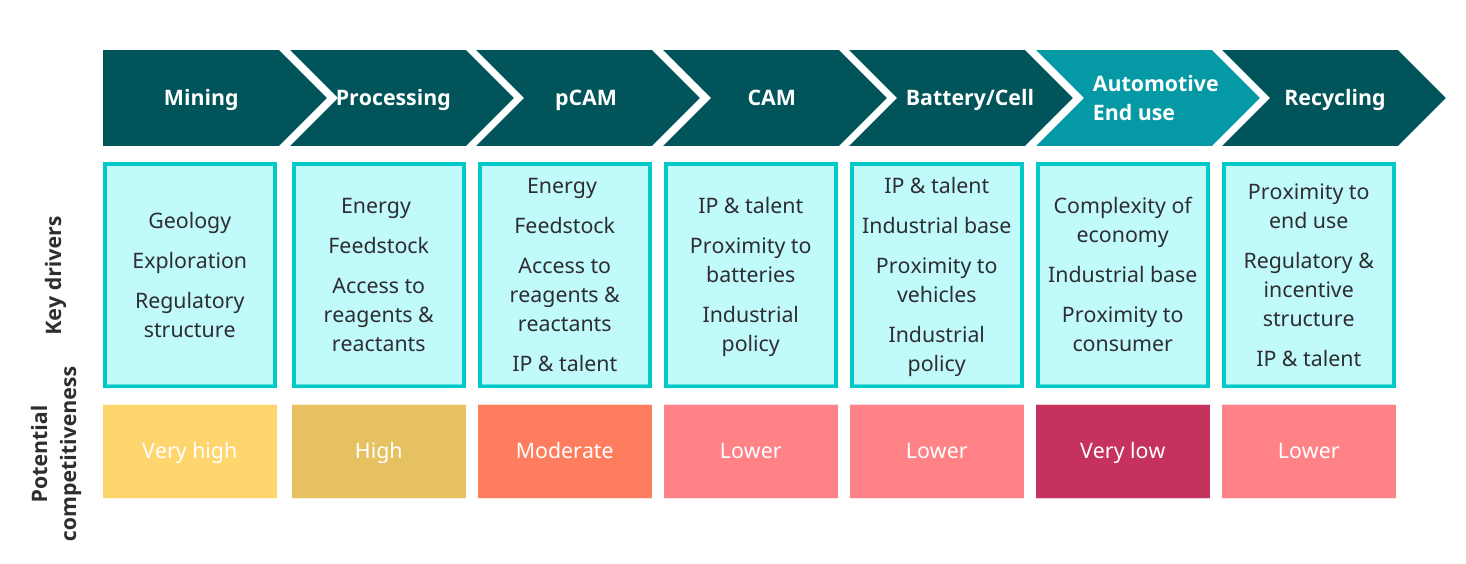
Source: Wood Mackenzie
Typical value addition success factors
In general, the most important success factors for mineral processing are:
Size of mineral supply. Scale is a critical determinant of a processing facility’s economic viability. The size of mineral supply also affects a country’s bargaining power. The differing size and market share of Indonesia’s nickel and bauxite reserves are the main reasons why its bans on unprocessed exports of these minerals—first imposed in 2014—have had different impacts. Companies have constructed 42 nickel smelters in Indonesia since 2014. The country is the world’s largest nickel ore producer, has the largest reserves, and has high-quality nickel. This meant that smelters in China would struggle to find an alternative to Indonesia’s nickel in both the short and long term, and therefore had to acquiesce to the Indonesian government’s insistence that China construct smelters in Indonesia instead. In the bauxite sector, however, Indonesia lacked similar leverage, and the main impact of the 2014 ban was a reduction in bauxite production. Indonesia was the world’s second-largest bauxite producer on the eve of the ban but its reserves are only the sixth largest (according to the U.S. Geological Survey). These smaller reserves made the profitability of alumina refining uncertain, and it was easier for China and other bauxite importers to source bauxite from other suppliers. The government lifted the bauxite ban in 2017, then reimposed it on bauxite ore exports in 2023, but is reportedly considering easing it again.
Transport costs. Processing can significantly reduce the weight of the minerals that are transported. The further away the customers, the greater the saving in costs from processing before export. For example, Zambia’s copper belt is 11,000 kilometers from China’s industrial zones. It therefore makes economic sense for companies to smelt their copper in Zambia even if smelters in China are more efficient, to save on transporting the heavier unrefined ore and concentrate. A large proportion of Zambia’s copper is smelted domestically as a result.
Availability of competitively priced, reliable, clean energy. Mineral processing tends to consume large amounts of energy. Producing countries with expensive, limited or unstable energy supply therefore face a significant obstacle to moving along the value chain. Some processing is particularly energy intensive: for example, energy accounts for around 40 percent of aluminum production costs. When energy prices rose in 2021-22, 50 percent of the European Union’s aluminum production capacity was forced offline. How clean the energy is also increasingly matters. For example, manufacturers of batteries using Indonesian nickel, and manufacturers of the electric vehicles using those batteries, may find it difficult to access the European market once the EU implements its battery passport in 2027. This mechanism—which will require companies operating in the European market to report on carbon footprint among other information—will likely penalize the high emissions from Indonesia’s nickel smelters’ use of coal.
Competing capacity elsewhere. The availability and cost of processing capacity elsewhere affects how important the above success factors are for a country’s prospects. For example, Guinea’s alumina refining ambitions, and Chile’s plans to construct new copper smelters, are complicated by excess capacity in China. The source of this competition is increasingly dynamic. Governments in many countries, such as the U.S., EU member states and Gulf states, are increasingly supporting to their domestic mineral processing industries to compete with China (and each other). This could further alter the economics of value addition prospects in low- and middle-income producer countries (see Key 5).
Good governance. Most value addition projects have large upfront construction costs and take a long time to make a profit. Predictable and transparent policymaking—in relation to both the broader mining sector (to reduce the risk of mineral supply disruptions) and for individual value addition projects—is therefore critical for investor confidence. As discussed in keys 2 and 4, investors are increasingly considering broader environmental, social and governance issues in their decision-making.
Additional success factors are relevant to value addition further along the value chain. In particular:
Proximity to downstream markets. As products get more complex, manufacturers tend to benefit from being close to their markets so they can capitalize on quicker, more flexible delivery to customers. Proximity can also help manufacturers to avoid difficulties in transporting specific products. For example, battery cathodes are chemically unstable. Cathode production therefore tends to be located close to battery manufacturing, as shown in Figure 1. Battery manufacturers benefit from being close to electric vehicle (EV) manufacturers, who in turn benefit from being close to large EV markets. This has implications for Congolese and Zambian plans to develop a nickel-manganese-cobalt (NMC) battery value chain. The African market for the types of cars that use NMC batteries is likely to remain small. As a result, despite the region’s large nickel, manganese and cobalt reserves, it will likely only be able to produce NMC battery precursors and then export them. Lithium-iron-phosphate (LFP) batteries, on the other hand, are used in the electric two- and three- wheelers and stationary power storage increasingly in demand across Africa. This value chain could therefore be both more beneficial for the region and more viable.
Existence of an industrial base. An existing industrial base helps to reduce the costs and risks of more complex processes. It enables investors to leverage existing infrastructure, a pool of companies and workers with similar know-how, local supply of inputs and a proven business environment for industrial activity. Partly because of these agglomeration effects, Wood Mackenzie predicts that battery production will largely coalesce in high- and middle-income economies in Asia, North America and Europe.
A country may have these success factors in place for some minerals but not others, and for some stages of the value chain and not others. As discussed in Key 3, governments can use a range of policies to fill gaps. However, they face limits in what policies can achieve, with several factors outside of governments’ control. If few of these success factors are in place, government incentives or penalties may be insufficient to encourage value addition, and may carry considerable costs. Governments should therefore ensure their strategies account for feasibility, and target value addition that leverages their comparative advantages. Governments with strategies centered on developing capabilities that provide new comparative advantages in the longer term, such as an industrial base, must be clear on the required steps and realistic about the prospects for—and costs of—taking them.
Countries’ own sector-level feasibility assessments should be informed by rigorous, independent project-level feasibility studies as part of the mine licensing process.3 Project-level feasibility studies can help governments, and other actors such as development partners, to identify missing success factors and the actions necessary to address them, and to manage expectations if filling these gaps appears insurmountable. Governments increasingly require license applicants to conduct some form of scoping of value addition feasibility. For example, the Ghanaian government has required a scoping study for a possible refinery in the license conditions for the country’s first lithium mine. However, these assessments are often ill-defined, lack clear timeframes and are rarely publicly disclosed. Producer country governments and citizens may also have limited trust in them given the companies involved in the project typically procure and pay the contractor conducting the assessment. Governments should therefore consider delinking procurement and payment for feasibility studies from the companies involved.4
Analyze the market outlook
Governments must account for the market outlook in their strategies. Value chains are dynamic. Changes in technology can result in large shifts in demand for products and therefore affect the benefit of attempts to move along value chains.
Some minerals and value chains are more exposed to technology risk than others. For example, long-term demand for copper and steel is likely to remain robust given their role in both the energy transition and wider global economy. Battery value chains, on the other hand, face significant uncertainty. NMC batteries have dominated markets until now, but market share for NMC batteries is shrinking. As Figure 2 shows, the International Energy Agency (IEA), among others, expects LFP batteries to become the dominant battery chemistry within the next decade, before ceding market share to lithium-free sodium-ion batteries. However, given the amount of ongoing research on battery chemistries—to improve performance, reduce costs and strengthen geopolitical positions—the future could also differ considerably from such predictions.
Figure 2. International Energy Agency’s projected market shares of electric vehicle battery chemistries
Governments of dominant mineral-producing countries, such as the DRC (for cobalt) and Indonesia (nickel), can influence the market trajectory to some extent. For example, battery manufactures are shifting away from using cobalt partly because of persistent concerns over DRC’s license security, taxation, corruption, and the welfare of artisanal miners. By improving governance, the DRC government could slow this shift. However, it is unlikely that any one producing country could fundamentally change the long-term outlook for a commodity for which demand is ebbing due to technological innovation.
Governments should therefore be cautious about pursuing value chains that are highly exposed to technology risk. This is particularly the case for projects that are still many years from being developed and therefore likely to miss any existing window of opportunity.
Analyze trade-offs and costs, not just benefits
Governments should base value addition strategies on rigorous cost-benefit analysis. This is particularly important given that many governments are not only pursuing value addition for socioeconomic gains, but also political ones: demonstrating the authorities’ capacities to “prioritize” national interests and actors, over international and corporate ones.
Even if a government realizes socioeconomic benefits from value addition, these benefits may not always outweigh the direct and indirect costs of the plan. These costs include environmental and social harm after the implementation of any anticipated avoidance and mitigation measures (see Key 2). For example, incorporation of the environmental and social impacts in an economic model used by one study of Indonesia’s nickel smelting operations found that continued smelting growth in three regions would have a positive economic impact in the first few years. However, the study found within ten years, the industry’s impact on the environment and public health would begin to negatively affect the regions’ overall economic output, including through reduced agricultural and fishing output.
Value addition can also have opportunity costs such as the diversion of public funds or electricity away from other productive or social needs. For example, Ghana’s aluminum value chain ambitions would require almost all the country’s hydropower capacity, which, without other new competitively priced electricity capacity coming online, would likely increase electricity costs for other businesses and households.
Governments must also consider the potential trade-offs between value addition and other ways that citizens can benefit from their mineral wealth. For example, if a government achieves value addition through instruments such as export bans, discounted mineral prices or downstream subsidies, it might create jobs, but in some cases weaken the public finances and therefore reduce spending on other development priorities. Similarly, governments must consider how the political capital, time and money spent on pursuing value addition, and the impact on the economics of mining operations, affect the potential to develop local suppliers of products and services to these mining operations. The procurement of goods and services usually amounts to 50 to 70 percent of all money spent by mining companies in producing countries. Local procurement by mine operators is therefore also a considerable opportunity for countries to increase government revenue, create jobs and develop new sectors.
A government’s cost-benefit analysis of value addition plans must also account for the distribution of costs and benefits across the population. It must ensure there is not only a net benefit nationally but also that benefits are equitably distributed across regions and for low- and middle-income as well as marginalized groups, including women, children, youth and communities living near value addition sites. The costs and benefits of value addition will not automatically accrue equitably within a country or even in the producing region within the country. For example, while Indonesia’s nickel activity has increased government revenue nationally and economic growth within the nickel-producing regions, poverty in those regions has increased, counter to the national trend.
2. Do no harm
The principle of doing no harm must be at the core of any government value addition strategy. Value addition, like mining, can cause significant environmental and social harms. It can lead to large swathes of forest being destroyed, create significant amounts of toxic waste, cause local air pollution as well as contribute to global carbon emissions, cause water stress and contaminate waterways and soil. The resulting impact on the health, livelihoods and general wellbeing of communities living near value addition facilities has been documented in countries including Brazil, China, Indonesia, Namibia and South Africa. The Chilean government closed two copper smelters in 2023-24 partly because of their impact on the environment and public health.
Governments should prohibit mining and value addition in areas of particularly high environmental and social sensitivity. Laws often provide governments with the authority to declare “no-go zones.” However, governments rarely utilize such provisions, and when they do, they sometimes fail to robustly enforce them or use them to cover all areas of environmental and social sensitivity. Company commitments, such as that by International Council of Mining and Metals (ICMM) members to not explore or mine in UNESCO world heritage sites, are also insufficient.5 They fall short, for example, of protecting forests of high conservation value inside and outside of protected areas. Mining concessions currently overlap with nearly 27 percent of the Congo Basin’s and more than 33 percent of the Amazon Basin’s intact tropical rainforests—areas that are critical for both resident communities and the planet.
To create the incentive for governments to establish and enforce no-go zones, development partners and other climate finance providers should offer conservation financing. Governments often undervalue the environment due to pressure to prioritize short-term revenue and jobs. This risk is potentially even greater for value addition projects. Public support for value addition ambitions means that governments are increasingly under pressure to deliver value addition at all costs. Conservation financing—building on lessons from projects such as the Central African Forestry Initiative through which the U.S., South Korean and several European governments provide financing to Gabon to maintain its forests—could change this calculus.
Governments should also not proceed with value addition activities when Indigenous peoples and local communities have not been meaningfully involved in decision making, or the right to free, prior and informed consent (FPIC) has not been respected.
For value addition projects outside of no-go zones and that have received the necessary consent, governments must account for potential environmental and social costs when granting permits to operators. Governments will have to overcome common technical and political economy challenges in incorporating these costs in permitting processes, however. They should implement existing guidance on good practice, such as that from the International Finance Corporation. Similar to value addition feasibility studies, to reduce the risk of corporate influence on the outcome of environmental and social impact assessments, governments should consider delinking procurement and payment for assessments from the companies involved in the project. Governments must also manage internal power dynamics to ensure effective cooperation between the authorities responsible for assessing projects’ environmental risks and their economic viability and benefits.
Governments also need to prevent risks from materializing once a value addition project proceeds. In doing so, governments should involve communities in environmental monitoring. Community involvement often leads to better and more cost-effective outcomes. Countries such as Argentina, Bolivia and Peru have introduced participatory environmental monitoring committees—though such practices can only achieve so much without addressing the growing government and corporate hostility toward, and violence against, environmental defenders and community leaders.
Addressing environmental and social impacts is critical first and foremost for reducing harm to the people in mining countries. However, it is also increasingly important for attracting investment and therefore achieving government value chain ambitions. For example, auto maker Mercedes-Benz will now only work with suppliers who purchase minerals from mines audited by the Initiative for Responsible Mining Assurance (IRMA) and who comply with OECD due diligence guidelines.
3. Design policy mechanisms tailored to the value addition strategy and consistently focused on equitable distribution of benefits
Governments can use a range of instruments—including fiscal, industrial and trade policy—in pursuit of value addition. Governments should select their policy approach based on the goals, economic feasibility assessment, market outlook and cost-benefit analysis set out in the value addition strategy, as well as their capacity and geopolitical leverage. Given the impact of the policy approach on the costs and benefits of value addition, governments should ensure a feedback loop between the strategy and policy approach and recalibrate as necessary.
Typical value addition policy approaches
Most policy instruments can be broadly categorized as restrictions and penalties, incentives or enablers.
Restrictions and penalties. Some governments impose a domestic supply obligation on mining companies to ensure that a portion of their minerals are processed domestically. China used a quota system to help develop its rare earth value chain. Chile’s lithium mining companies are required to sell a portion of their production at preferential prices to domestic value addition facilities. Several governments, including Tanzania, restrict licenses to companies that commit to value addition. Other governments prohibit the export of some or all unprocessed minerals. Indonesia has banned the export of nickel and bauxite ore, as noted in Key 1, and is planning to reimpose a copper concentrate export ban at the end of 2024. Other countries such as Namibia and Zimbabwe have also instituted various forms of export bans. Some governments do not restrict the volume of unprocessed exports and charge higher taxes on them instead. China does not refund value-added tax on rare earth exports but provides refunds for rare earth magnet exports. Mongolia charges higher royalty rates on ore and concentrate exports than refined copper exports.6
Incentives. Governments often offer tax incentives to reduce value addition costs and/or make value addition more attractive to investors. Indonesia offers a corporate tax holiday, import duty and VAT exemptions and lower local government taxes to value addition projects. Western Australia limits the royalty amount due on lithium hydroxide and carbonate to that payable on the lower value concentrate feedstock. Several governments subsidize inputs, such as South Africa’s electricity subsidies to its aluminum smelters and other processing plants. Another incentive is discounted mineral prices. This discount could result from government requiring mining companies to offer lower prices, such as in Chile, or government direct or indirect subsidization of the price. Some governments provide direct financial support in the form of equity stakes, grants, concessional loans and sovereign guarantees. The U.S. recently announced a $2.3 billion low-interest loan to support construction of a domestic lithium carbonate refinery. As discussed in Key 5, governments can also sign agreements with other countries that provide a source of incentives in addition to any that they offer themselves. Morocco’s free trade agreement with the U.S. unlocks access to the Inflation Reduction Act’s tax credits for minerals processed in Morocco.
Enablers. The EU intends to streamline permitting processes for “strategic projects” selected under its Critical Raw Materials Act to increase the attractiveness of such projects to investors. Several governments are investing in infrastructure improvements, either unilaterally or in collaboration with industry, to reduce operating costs within a value chain. For example, Canada’s Critical Mineral Strategy sets out investment in energy and transport infrastructure. Some governments actively coordinate the development of industrial clusters—through infrastructure provision, tax incentives and regulation—to generate agglomeration benefits for companies. Much of Indonesia’s processing takes place in industrial parks, while DRC and Zambia are planning to establish special economic zones to support their battery value chain ambitions. Some governments, such as Australia’s, are funding training programs and apprenticeships, while others have reduced restrictions on foreign workers to fill skills gaps.
Another key enabler can be regional coordination when it helps governments to overcome individual country constraints. For example, combining feedstock volumes from several countries can help achieve economies of scale. DRC and Zambia's planned battery precursor project requires coordination between the two countries, and minerals and other inputs from others. However, regional coordination must navigate a range of economic and political dynamics, and grapple with the inherent tension between cooperation and competition among participating countries.
Different policies will be optimal for different countries and value chains. As noted in Key 1, if feasibility constraints are considerable, most policies are likely to be insufficient to encourage value addition and may have significant costs. In this context, the main impact of penalties risks companies reducing their mining activity. Feasibility challenges also increase the risk that incentives, such as subsidies or direct financial support, not only divert government resources away from other development objectives but are used to benefit specific individuals or companies without meaningfully increasing value addition (see Key 4).
Governments should also base their policy approach on their value addition goals. For example, if a government’s main goal is to generate more revenue, authorities must use tax incentives carefully to ensure they do not eliminate most of the potential revenue from a value addition project.7 They must also calibrate instruments such as export bans, downstream subsidies and discounted mineral prices to avoid reducing overall government revenue from the sector. If the government is aiming for “shared-use” infrastructure—for example, a railway that transports both minerals and other cargo or paying passengers—then officials may need to primarily use incentives to mitigate the higher costs (provided these incentives do not outweigh the overall benefits).8
Governments should also account for their financial, technical and regulatory capacity, as well as geopolitical leverage, in their policy approach. For example, fast-track permitting raises the risk that a government might make mistakes or miss environmental, social or corruption red flags. However, this risk is higher for countries with lower regulatory capacity. Governments with scarce financial resources should be particularly cautious about pursuing value chains that are highly exposed to technology risk given the considerable opportunity costs. Governments should also weigh the risk of trade disputes, and their ability to challenge or withstand them when choosing a policy approach: for example, in choosing between imposing an export ban or quotas, which can be challenged under World Trade Organization rules, or export taxes, which tend not to be.
Finally, governments must integrate the distinct experiences, needs and contributions of different marginalized groups into their policies. Ensuring that these groups are unharmed by value addition is critical but insufficient. Governments must also ensure that such groups receive a more equitable share of the benefits than has often been the case in the mining sector. For example, shared power generation capacity should benefit local communities as well as supply the national grid; government skills development policies should be designed specifically to reach women and facilitate their participation in the value chain.9
Irrespective of which policy approach a government takes, the approach should be clear and applied in a consistent and transparent way. Failure to do so could undermine any positive impact that government policy would have otherwise had.
4. Address corruption risks
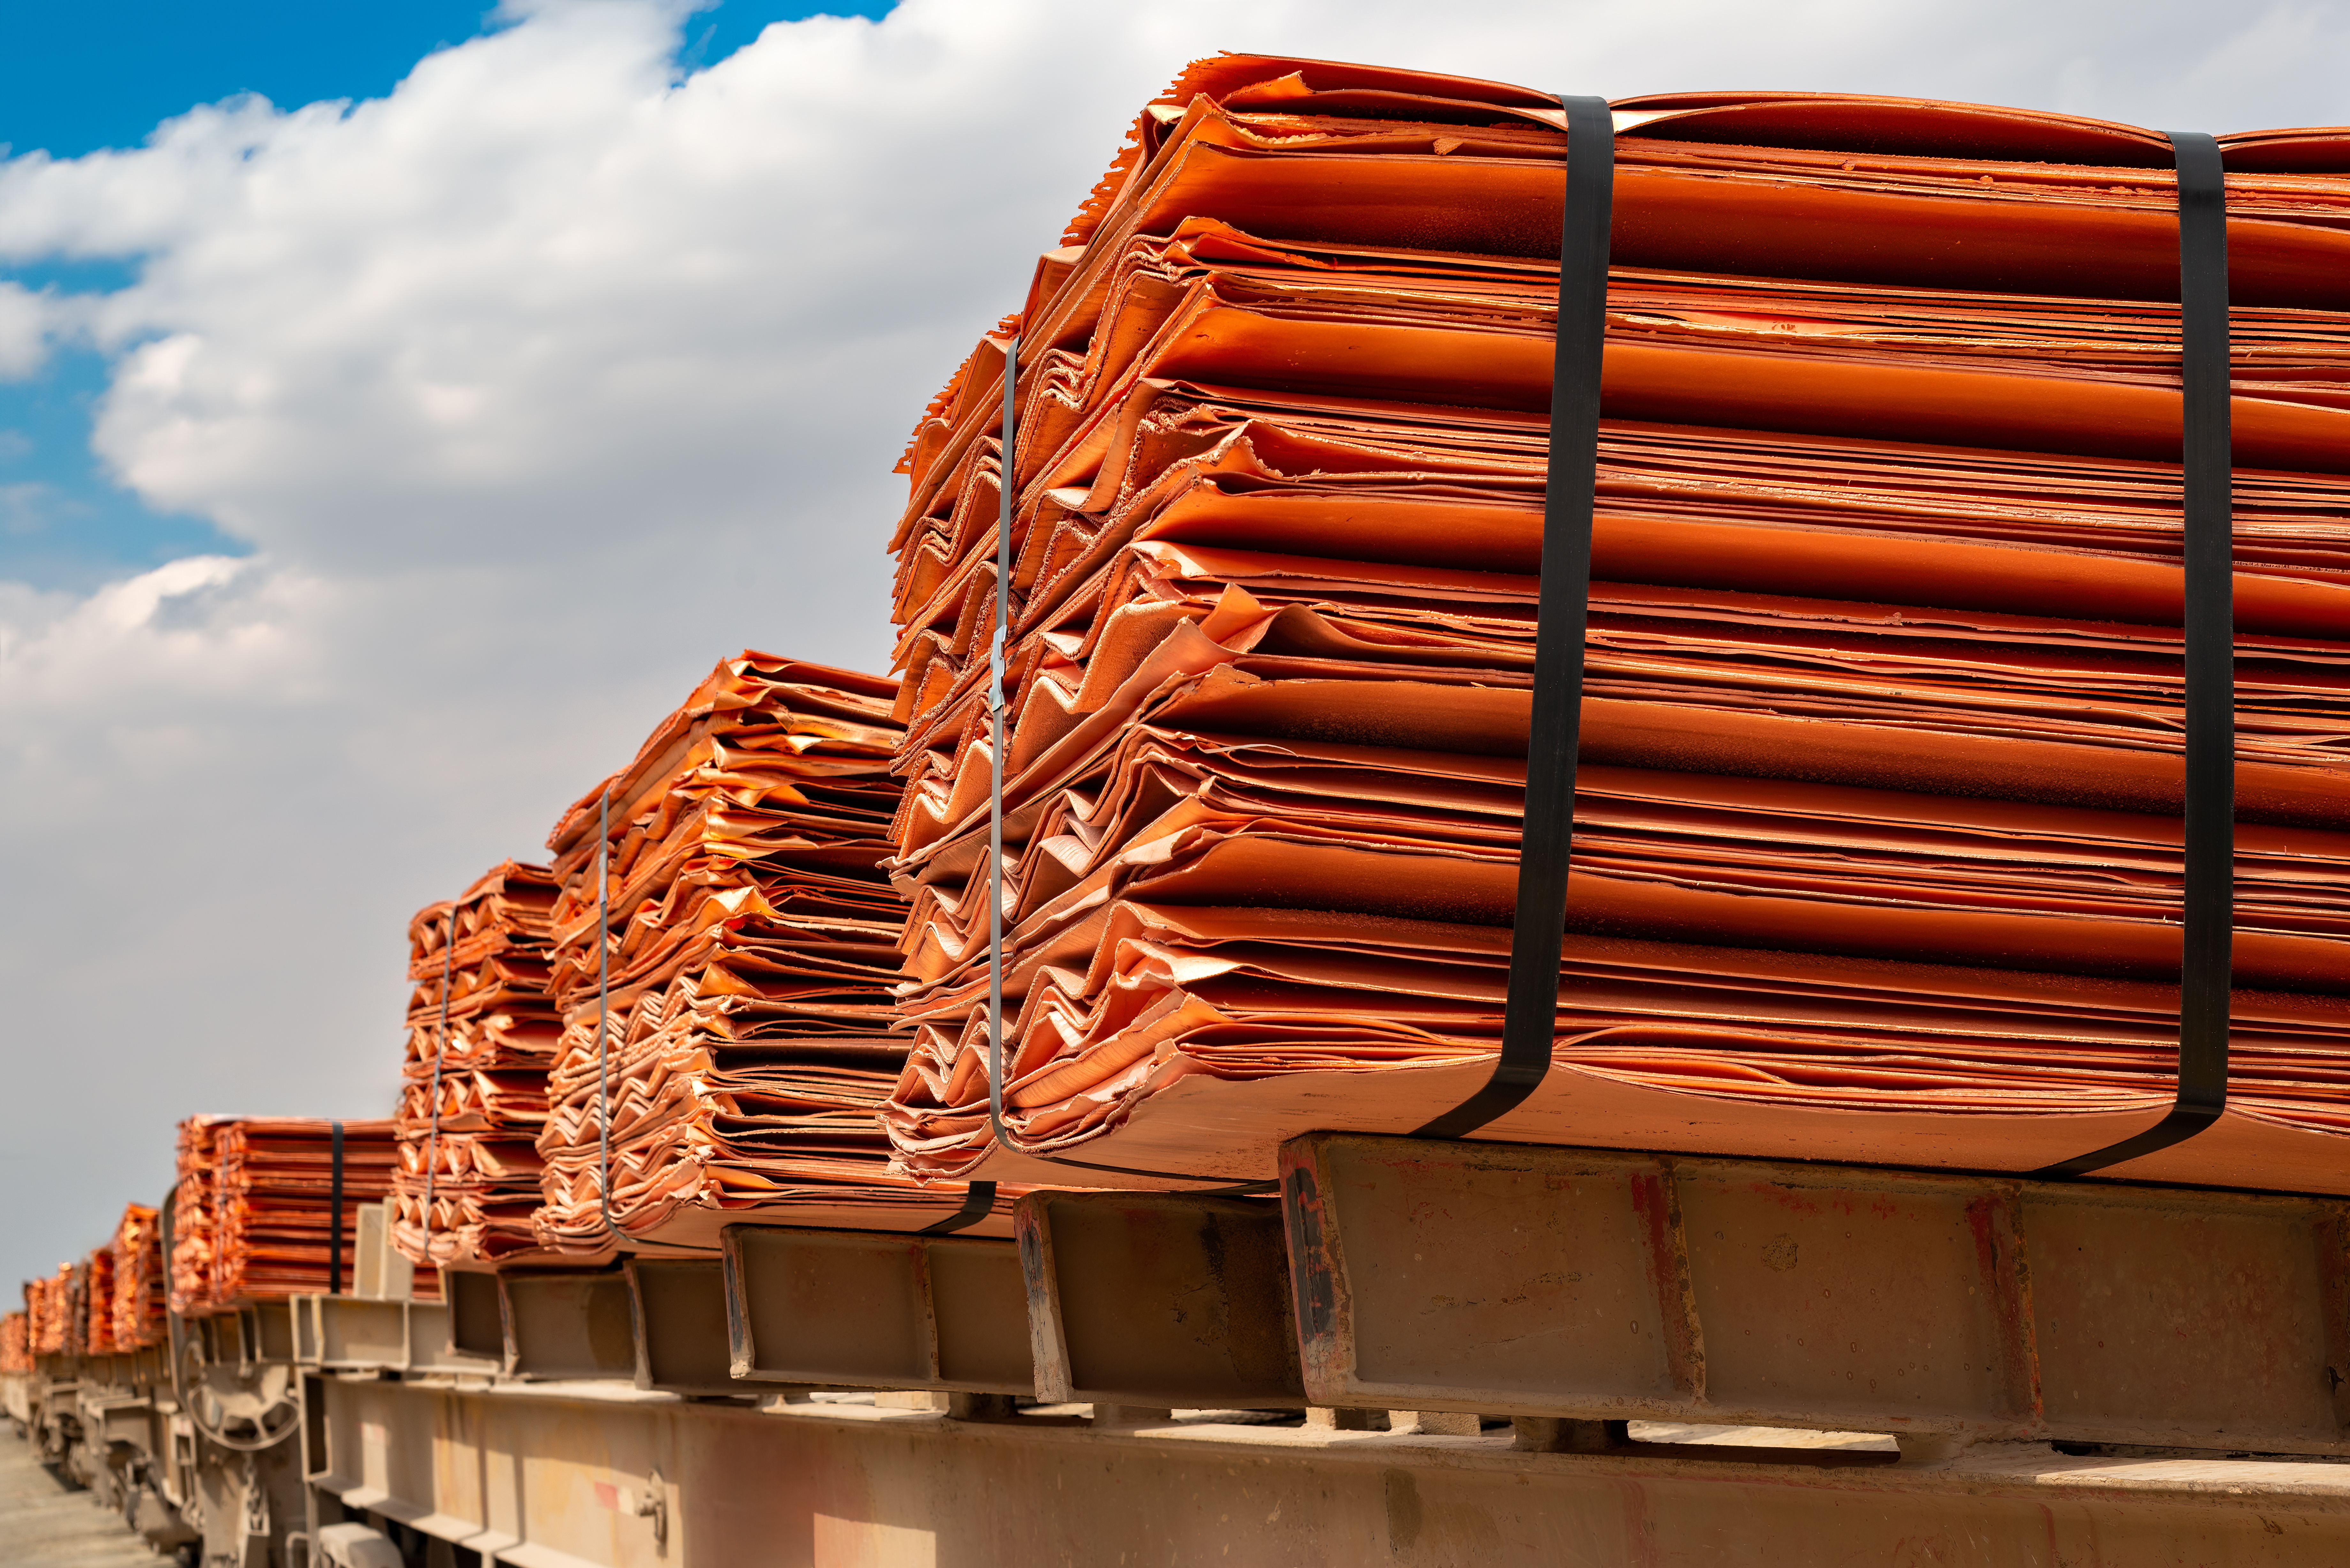
Value addition policies are always, on paper, officially designed to benefit the citizens in producer countries. However, by creating economic opportunities and incentives, these policies are exposed to corruption risks. The extractive sector is particularly prone to corruption.In the context of a transition minerals rush—characterized by geopolitical competition and ambitious value addition agendas—various corruption risks are likely to increase further.
Tackling corruption will be essential for designing fundable value addition projects that provide a net benefit for people in producer countries. While NRGI is working on these issues and will soon publish detailed analysis, we have already identified—building on previous work—some of the main risks that governments must address.10
Policy capture. Like all policies, value addition policies can be influenced by private interests seeking to shape their design for personal gain, often at the expense of the country’s wider population (though these interests can sometimes align). For example, actors who have the capital, knowledge and connections to develop domestic processing—and to be the first movers to do so—will have a strong incentive to push or support an export ban. The risk of policy capture has been documented across many policy areas: from environmental regulation in the Chilean lithium sector and cost assessment rules in the Indonesian nickel sector to local content rules in several countries including the US.
Licensing and permitting. The licensing and permitting phases have some of the highest corruption risks. Examples abound of corruption in mining licensing and permitting, from Portugal to Namibia. The risks appear to be similar for licensing and permitting of processing facilities. For example, Indonesia’s nickel smelter permitting process has been accused of a mix of favoritism, nepotism and bribery. Questions have been raised about the beneficial ownership of a Ghanaian gold refinery that has been granted an advantageous permit to refine gold purchased by the Bank of Ghana. Similar corruption cases have been documented in the awarding of government contracts for goods and services.
Financial incentives. Value addition policies often rely on financial incentives, as described in Key 3, which can increase corruption risks. The design, negotiation and granting of tax breaks, subsidies, grants or loans are all decision points where government officials can favor certain companies or actors: companies to which they are connected in different ways (e.g., companies they own or those owned by relatives or allies). These are also moments where companies’ representatives might try to bribe decision-makers for unfair access to these incentives. Such incentives can have unintended consequences, particularly if accessed through corrupt means. For example, if the same or related companies own both a mine and the refinery it supplies, a lower tax level for the refinery could lead to transfer pricing abuse. If not monitored carefully, discounted mineral prices could provide owners of value addition facilities with a cheap source of minerals that they then export with minimal further processing.
Infrastructure. Many low- and middle-income countries will likely require a considerable amount of new infrastructure to move along the value chain, with governments overseeing and sometimes providing direct support to its construction. Construction is one of the sectors most prone to corruption across the world. Infrastructure projects are often large, complex and involve many different actors. Corruption risks arise from undue influence in project selection to favoritism in the award of contracts. For example, corruption has been one of the reasons why the Sicomines “resources for infrastructure” deal in the DRC has resulted in delayed, low-quality infrastructure.
Socio-environmental harm. Corruption is one of the worst aggravating factors that can enable the socio-environmental harm described in Key 2. It can undermine the integrity of environmental and social impact assessments, manipulate community consultations and FPIC, and distort land access negotiations. Corruption can also enable companies to conceal socio-environmental damage or operate with unsafe and unfair conditions for workers, as seen in the rare earth mines of Myanmar.
Industry players, such as automakers, entering new parts of the value chain due to the rush for transition minerals could heighten these corruption risks.11 Such companies likely have less experience and knowledge of mining sector practices and challenges, particularly in the geographies where mineral reserves are located, making them more vulnerable to sector-specific corruption risks.
Failure to address the above risks would not only reduce the benefits from value addition in the short term but would likely deter investment in both mining and value addition projects in the long term. Some of these risks are broader than mineral governance; for example, the challenge of policy capture interacts with a country’s political system. Nevertheless, governments can mitigate many of these risks by having a clearly defined, evidence-based value addition strategy to inform policy approaches (see Key 1) and by equipping their value addition policies and projects with strong integrity safeguards. Based on NRGI’s experience, these safeguards include measures to: enhance transparency; increase consultation and participation in decision-making; strengthen oversight actors; reform regulatory processes; improve rule enforcement; and address foreign enablers.
5. Acquire any additional finance and support needed to make projects viable and beneficial
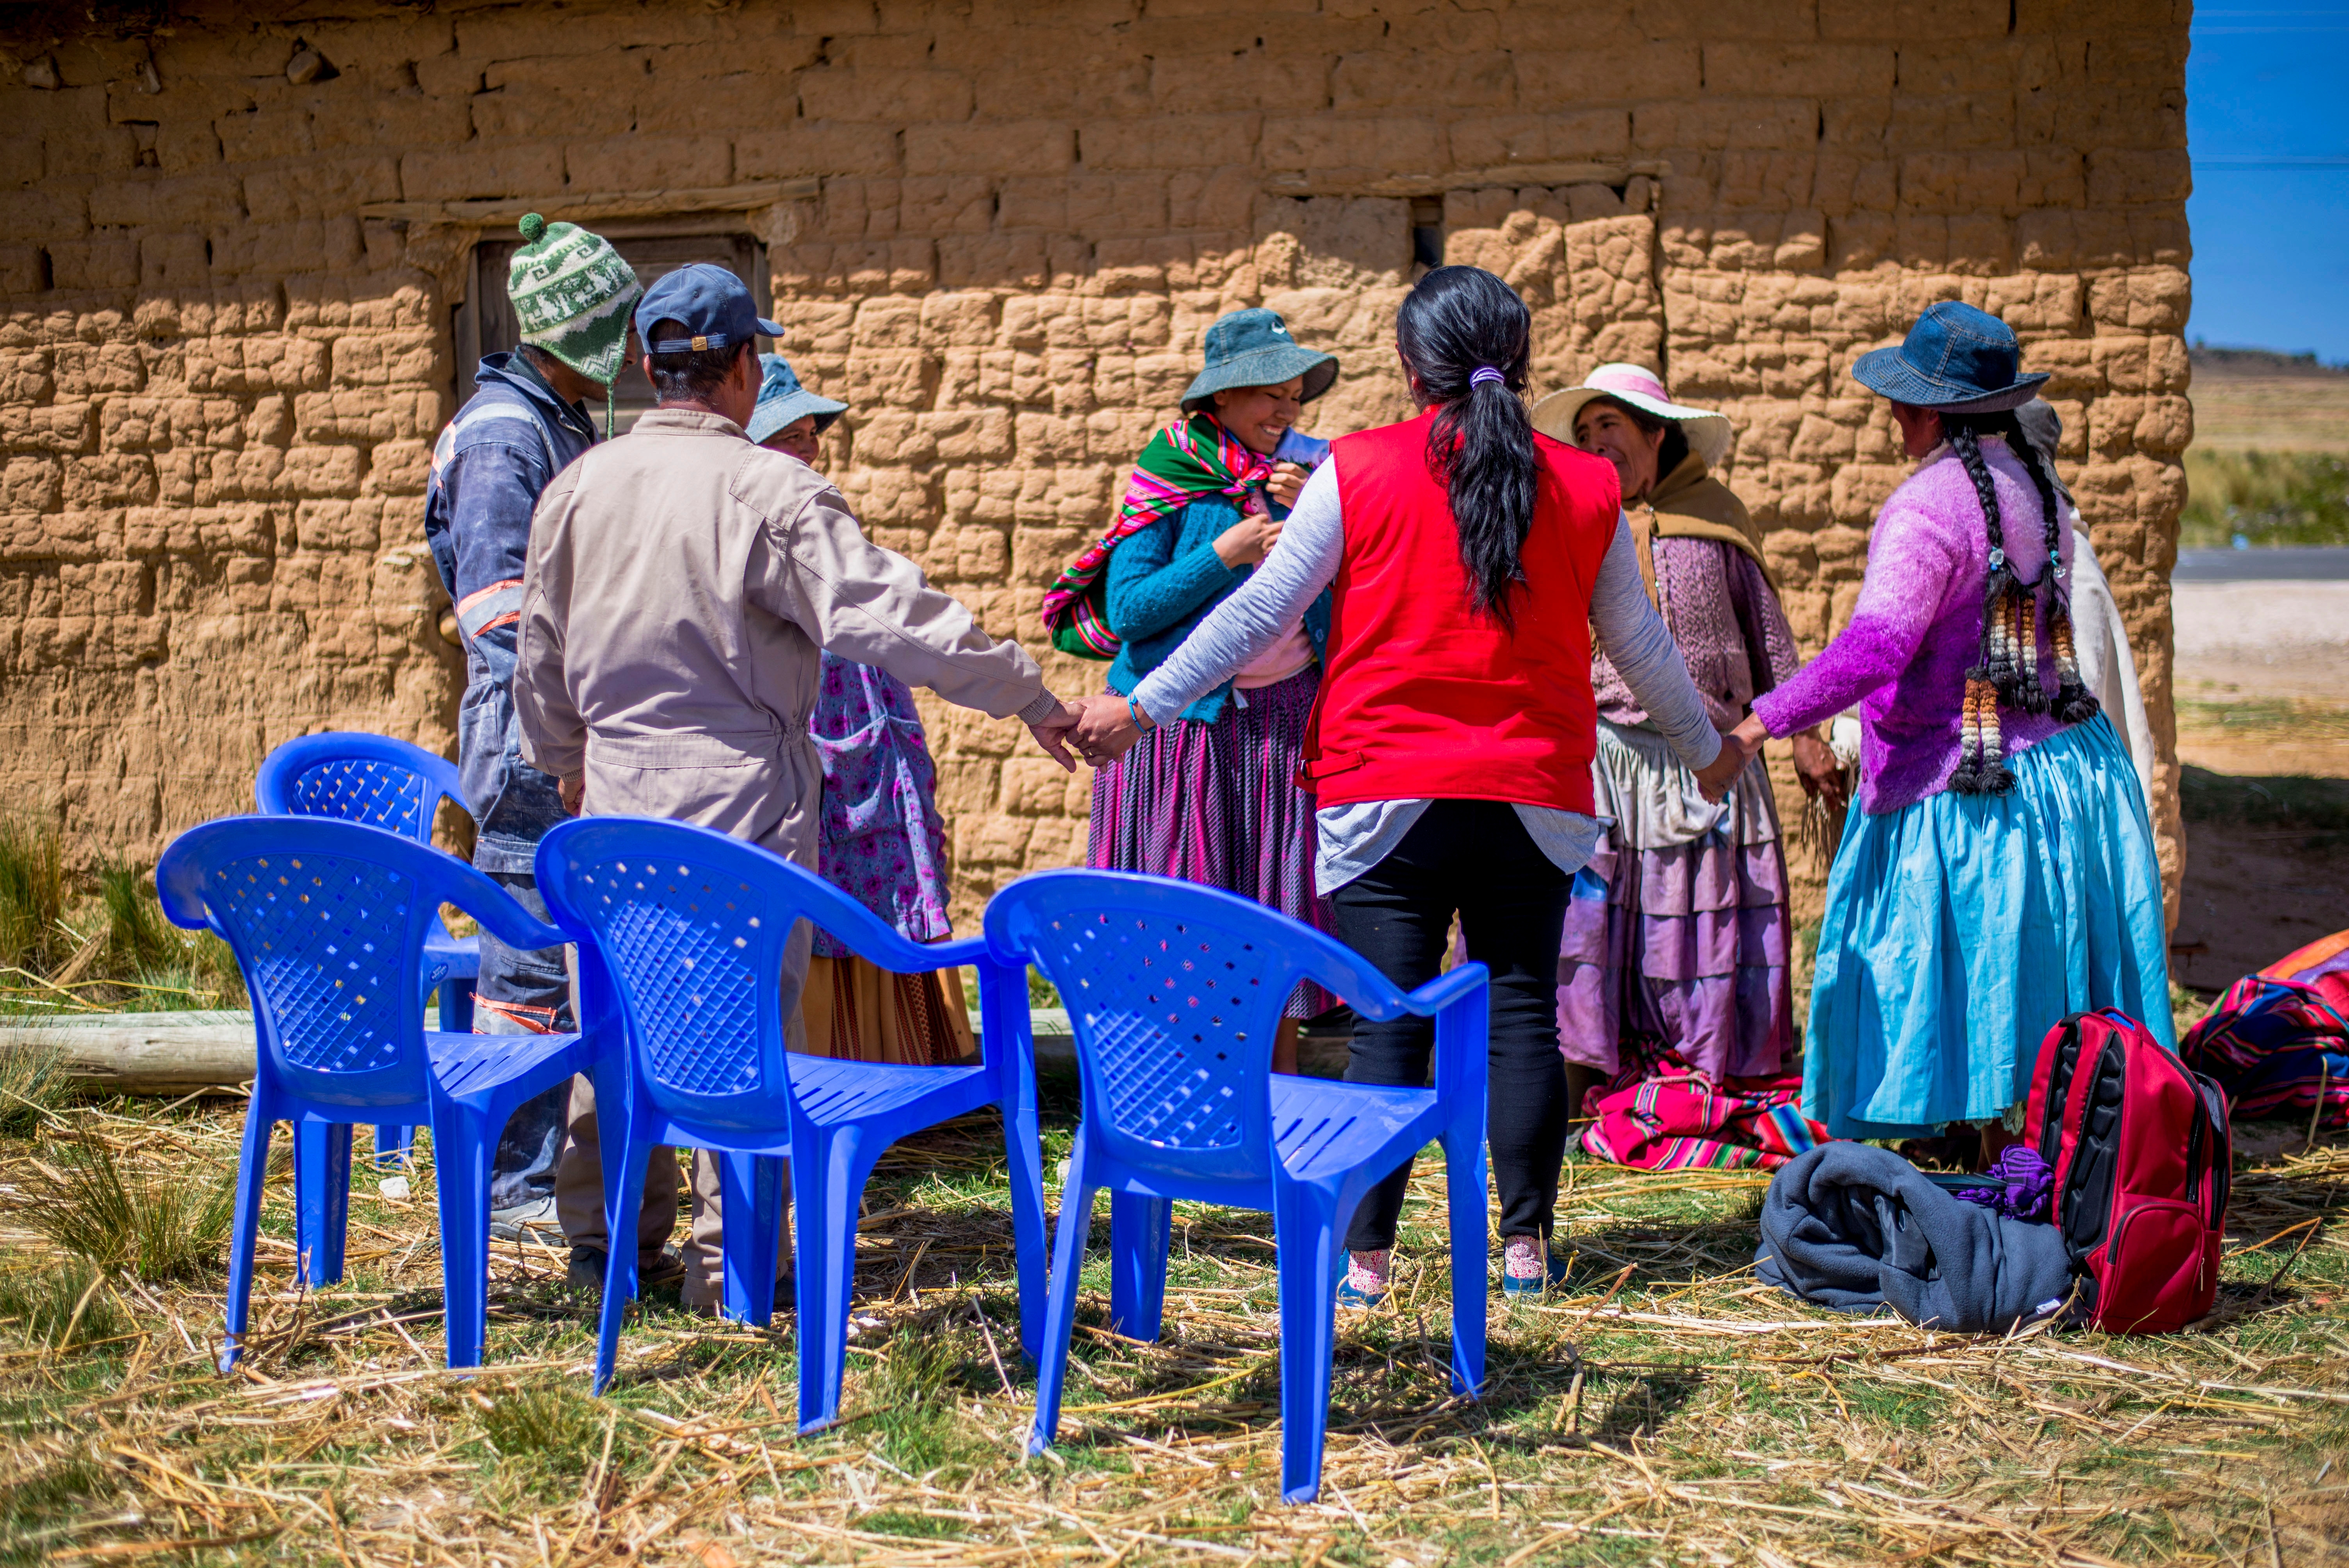
Governments of low- and middle-income producer countries must do the legwork to pave the way for fundable, beneficial projects. However, development partners and consumer country governments have a critical role in enabling more value addition in low- and middle-income producer countries and ensuring it provides a net benefit for their people.
Development partners and consumer country governments should increase funding and technical support to authorities in these countries. Many low- and middle-income country governments do not currently have sufficient resources or information to develop, implement and monitor detailed value addition strategies and policies. These constraints also hinder their capacity to conduct rigorous cost-benefit analyses of potential projects and effectively regulate their operation.
Based on their value addition strategies, low- and middle-income producer country governments should coordinate with companies and development partners to identify where concessional financing to governments can also realistically help address feasibility constraints, including by crowding in more private investment. Support could target value addition facilities directly or address bottlenecks in areas such as local skills and transport and energy infrastructure. Infrastructure support can be particularly impactful when designed to maximize spillover benefits. By reducing the cost of shared-use infrastructure for companies involved in value addition projects, development support can also help governments avoid offering tax breaks and other concessions in exchange (see Key 3). Development partners and consumer country governments should consider how to configure this range of financial and technical assistance to overcome political economy challenges and incentivize high environmental, social and governance standards in producer countries.
Consumer country governments have mooted this type of support—through the MSP and other state-state partnerships—as they attempt to secure the minerals of low- and middle-income producer countries. However, whether they will “put their money where their mouth is” remains to be seen. The MSP’s recently announced support for a nickel project in Tanzania is the first to a lower-income country that has a (previously planned) value addition component. Meanwhile, the EU is expected to announce its first tranche of “strategic projects” in the coming months.
Consumer country governments must also ensure they do not counteract any proactive support to value addition ambitions with other measures that hinder greater international equity around mineral value addition opportunities. As noted in Key 1, government support to domestic industry in China, U.S. and other higher-income countries is increasing. This not only intensifies the competition faced by low- and middle-income countries; some of this support—in the form of trade restrictions, subsidy regimes and sustainability requirements—could also impede their value addition ambitions in other ways.
The EU signed a new trade agreement with Chile in 2023 that prevents restriction of exports or disadvantaging of EU access to Chile’s minerals, for example. It also limits Chile’s ability to offer preferential prices to domestic value addition facilities by requiring that prices not be set below the export price of the previous year. The U.S. Inflation Reduction Act provides electric vehicle tax credits only for minerals processed in the U.S. or a country for which it has a free trade agreement. While this provision has benefited some low- and middle-income countries, such as Morocco, it likely reduces the potential for value addition investment in others. Sustainability requirements can also have unintended consequences for potential investment in low- and middle-income countries. For example, the EU Carbon Border Adjustment Mechanism will tax products such as aluminum and steel that have a large carbon footprint. If this mechanism is not accompanied by the necessary support to help countries such as Ghana and Mozambique reduce their emissions, it could lock their exports out of the European market.
As low- and middle-income producer governments account for the myriad of agreements, frameworks and mechanisms in their value addition strategies, they must also navigate the complex and evolving geopolitical landscape. For example, Indonesia has so far been unsuccessful in negotiating a free trade agreement with the U.S. to qualify for the Inflation Reduction Act’s incentives due to Chinese dominance in the Indonesian nickel sector. As a result, the Indonesian government is currently attempting to reduce Chinese investment in new projects. How low- and middle-income producer countries leverage this geopolitical competition while managing the associated complexities will be critical for successfully moving along the value chain.
6. Ensure a transparent approach involving citizens every step of the way
Having increased their calls for, and promises of, more value addition, governments of low- and middle-income producer countries are under growing pressure to deliver for their citizens. Establishing value addition projects is also becoming increasingly important for the social license to operate for mining companies. For example, the Ghanaian government’s ambition to establish lithium refining in the country has broad public support, including from civil society groups, which have described it as a “red line.” However, as this brief has set out, value addition will not always be viable for a country, nor will it always generate a net benefit for its people.
Governments and companies must therefore engage the public in value addition planning. Transparency and trust are essential to manage public expectations and to avoid governments pursuing value addition at all costs, for the benefit of only a happy few, or a backlash against the mining sector. Governments and companies must disclose and consult with the public on feasibility studies, environmental and social impact assessments and cost-benefit analyses for value addition projects. Governments should also encourage informed debate about the trade-offs involved, especially when opportunity costs are considerable. Governments and companies must ensure these processes are inclusive, in which marginalized groups are not only included but actively engaged in shaping decisions. Accountability actors—such as parliamentarians, civil society organizations and media—must also play an active role and rigorously evaluate government and company plans.
Failing to involve the public in navigating these complex decisions could leave a country with the worst of both worlds: no or costly value addition, and even more public frustration and disruption of mining projects.
Conclusion
Governments and civil society actors in low- and middle-income producer countries are calling for more domestic value addition of their minerals to increase government revenues, generate jobs and support the development of other sectors. Consumer countries and multistakeholder initiatives are also belatedly acknowledging the inequities of global value chains. However, significant work is needed to translate this focus into viable value addition projects that provide meaningful benefits to people in producer countries including marginalized groups. Time is of the essence. Addressing the historical inequities of the mining sector is critical for meeting the urgent needs of people in producer countries. By reducing the risk of public frustration in these countries, and therefore helping to derisk investment in mining and encourage global cooperation, it is also essential for tackling the climate crisis.
Acknowledgements
The authors thank colleagues across NRGI, in particular Alex Malmqvist, Amir Shafaie, Ana Carolina González Espinosa, David Sefa Adjei, Dorjdari Namkhaijantsan, Erica Westenberg, Lee Bailey, Moise Liboto Makuta, Patrick Heller and Pedro Zapata for providing valuable support, perspectives and advice, as well as the fundraising and operations teams for making this brief possible.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Setting Up Uganda’s National Mining Company to Boost Sustainable Development

Key messages
- A Natural Resource Governance Institute survey of national mining companies (NMCs) provides useful lessons for the newly established Uganda National Mining Company (UNMC), as the Ugandan government and UNMC Board of Directors work to operationalize the company.
- With a limited commercial mandate, UNMC could play a valuable role in unlocking Uganda’s mineral potential by investing in geological surveys and co-financing exploration to derisk projects for experienced exploration companies.
- A cautious approach would be beneficial, given the considerable opportunity cost of using public funds and the risky nature of exploration, especially in the early years as the company builds experience.
- UNMC could learn from other NMCs that have struggled to benefit from minority state equity and reconsider these plans. If it continues to seek minority equity, its strategy for negotiating shareholder agreements and dividend rights will be critical and could involve guaranteed dividends or preferred shares.
- Regardless of UNMC’s mandate, a clear funding model, along with strong management, oversight and transparency policies and implementation mechanisms, is essential for enabling the company to successfully contribute to Uganda’s sustainable development.
The Government of Uganda recently established UNMC as part of its effort to increase the contribution of the nascent mineral sector to sustainable development. In November 2024, the Ministry of Energy and Mineral Development appointed the Board of Directors to begin operationalizing the company.
To support this process, we have compiled the experiences of other NMCs. Most of the more than 62 other NMCs around the world have a commercial mandate to manage the state’s majority or minority equity participation in mines. Operational mandates are less common, primarily because most NMCs lack the technical or financial capacity to efficiently operate mines. While some governments have assigned both regulatory and commercial mandates to NMCs, most have separated these roles to avoid conflicts of interest and reduce the risk of corruption.
National mining companies across the world
NMCs can help the government exercise greater control over the sector, speed up technological and human-capacity development, address market failures, generate additional revenue, and ensure responsible mining. Some NMCs have successfully achieved their objectives as well as long-term profitability. However, many face significant weaknesses or struggle to fulfill their mandates. NMCs that have a controlling interest in or operate mines often suffer from high costs and weak revenue generation. Those with minority or non-controlling equity in mines have also generally experienced financial disappointments. Unless a government mandates dividend payments, majority shareholders can retain earnings, reinvest profits, or shift profits to offshore subsidiaries or other related parties, thereby lowering dividends on state equity.
NMCs can also play a role in production-sharing arrangements if a government chooses to receive its share of production in kind, taking physical delivery of the minerals. While production sharing has been rare in the mining sector, it is increasingly being considered, including by Uganda. Production sharing can help mitigate some transfer pricing risks; however, for some countries, it has generated new challenges related to transportation, warehousing and negotiating sales contracts.
A few NMCs invest further along the value chain in smelting, refining, and other downstream activities. However, many of their projects have been unprofitable and have failed to stimulate the establishment or expansion of other sectors. NMC involvement has generally not changed the reality that access and proximity to mineral deposits play only a small role in determining the feasibility of moving along the value chain.
The challenges faced by several NMCs have been compounded by investments in non-core activities without the requisite expertise, and by suboptimal funding models. NMCs often retain an excessive proportion of revenues and fail to distribute dividends to the government. Many NMCs are also overindebted or borrow on unfavorable terms, increasing state liabilities.
The global experiences of NMCs offer valuable lessons for UNMC on how it can contribute to growth of the minerals sector and sustainable development of the country. Based on these experiences, this report outlines ten recommendations for the Ugandan government and UNMC’s Board of Directors.
- Set a clear, limited mandate focused on addressing market failures to unlock Uganda’s mineral potential.
- Reconsider paying for non-controlling equity in a mine’s development and operational phases.
- Carefully consider production sharing, including UNMC’s capacity to do so.
- Invest in value-addition activities only where they align with a clear, evidence-based strategy.
- Limit non-commercial and non-core roles.
- Allocate start-up capital based on a realistic plan, budget and assessment of opportunity costs.
- Allow only the retention of revenue from own investments and set a high payout ratio to government.
- Engage experienced consultants to support setting up UNMC to align with its mandate.
- Ensure parliament reviews operations and finances and approves large investments, and that external auditors conduct annual audits.
- Require the highest standards of transparency.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Mining And Minerals: Why production sharing agreement is bad for Uganda
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Institutional capacities for a just transition in coal regions: the case of La Jagua de Ibirico, Colombia

Since 2020, the Colombian department of Cesar – and specifically the municipality of La Jagua de Ibirico – has suffered serious social and economic consequences after one of the country’s most active coal companies halted operations.
These events aggravated the crises in an area already affected by armed conflict and social inequality.
This report explores the fallout of the coal industry’s departure and uses these lessons to recommend how other coal-dependent governments can avoid these problems and plan for a just transition that lessens the blow of coal’s decline.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Breaking Ground: Critical minerals, critical opportunities for women’s participation
GA Building CR-12, New York

The side event of the 69th Commission on the Status of Women (CSW69) allowed the discussion on women’s roles and opportunities related to the extraction, production, and beneficiation of critical minerals for the energy transition and related sectors, including strategies to ensure their equal participation at every step—from artisanal and small-scale mining to higher-value-added processes.
The event organised by the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development (IGF) and the United Nations Conference on Trade and Development (UNCTAD), featured industry experts such as Fernanda Ballesteros, NRGI's Country Manager for Mexico.
This event was designed to foster dialogue on strategies needed to ensure that women can benefit from the trade and employment opportunities in the expanding mineral sector, showcase policies to facilitate women’s equitable participation in the low-carbon energy transition, and discuss public and private policies to enhance finance, technology, and markets for women in the mineral value chain.
Fernanda Ballesteros
Mexico Country Manager
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Improving Mining Permits in Africa: Transparency and Reform
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Value Addition, Governance and Global Responsibility: A Roadmap for Equitable Mineral Supply Chains

NRGI’s Suneeta Kaimal spoke at the Mining Indaba 2025, where she discussed the role of governments in developing value chains for critical energy transition minerals with moderator Divyam Nagpal.
Divyam Nagpal, Principal Specialist – Renewable Enerfy, SEforALL:
You participated in the Secretary General’s Panel on Critical Energy Transition Minerals, which emphasized the centrality of advancing equity across the global supply chain. What are the most important steps that international institutions, private sector and researchers can take to ensure that investment in African supply chains is equitable and benefits Africa and Africans?
Suneeta Kaimal, President and CEO, NRGI:
Last year, the UN Secretary General convened a multistakeholder panel on critical energy transition minerals to help define principles and actions to ensure low- and middle-income producer countries are not left behind or made worse because of the energy transition. At the center of the panel’s work was the agreement that achieving justice and equity requires change. Change from the deep-rooted inequities that have long plagued the minerals sector and global supply chains. Change from the destructive, exploitative practices that have left too many countries with neither wealth nor resources. And a change from the pit-to-port model. In fact, in a 2023 survey by the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development, more governments named value addition as the main driver for their critical mineral strategy than any other factor.
Given that sense of urgency on value addition, the very first actionable recommendation of the UN Panel report launched last year focuses on advancing value addition, economic diversification and benefit sharing. In the coming months, the Secretary General will establish a new multistakeholder, high-level advisory group to advance these ambitions. To help ensure the success of these efforts, NRGI brought together representatives from governments, the private sector, international institutions, academia and civil society to develop a roadmap to increase value addition for low- and middle-income producers.
Three key recommendations emerged from our discussions to bring equitable, feasible value addition to life:
- First—all voices must be included. Too often, the ambitions of the consumer countries or the global north dominate the global dialogue on energy transition and energy security related to transition minerals. The UN Panel was a welcome step forward in placing the voices and needs of people in low- and middle-income countries at the center of the dialogue. It brought together wealthy and consumer countries with low- and middle-income producers, civil society experts, industry and finance leaders in the same room, at the same table. However, meaningful multi-stakeholder participation shouldn’t be something remarkable, it should be the norm.
- Second—the required international financial support has to be on the table. In the last few years, including here at past Indabas, we’ve heard the likes of the US, EU and Saudi Arabia talk about the importance of win-wins and seen them dangle the prospect of significant financial support to enhance supply chain equity. But without delivering. Take the Lobito Corridor. A project that has the potential to generate benefits for Africans but also carries many environmental and social risks and could end up just reinforcing the pit-to-port model if it’s not accompanied by critical, additional steps to help African governments link these opportunities to broader economic ambitions that contribute to sustainable development for all Africans. For example:
- Support to increase government planning capacity, to enable procurement of the necessary models and data.
- Support in the form of concessional financing to governments that can realistically help address feasibility constraints, including by crowding in more private investment.
- Support to target value addition facilities directly or address bottlenecks in areas such as local skills and transport and energy infrastructure.
Third—global leadership is needed to strengthen governance. Good governance is a critical driver of change in mineral supply chains. It supports strong environmental and social protections. It makes sure that laws are enforced, communities have a voice, and businesses operate responsibly. Without good governance, corruption, weak enforcement, and short-sighted policies pave the way for environmental destruction and social injustice. Now, more than ever, countries committed to responsible mineral supply chains must ramp up efforts for global action that supports stronger governance. But good governance isn’t just a moral imperative—it’s a smart business strategy. The only way mining companies can attract the level of investment needed to meet soaring demand for transition minerals is by reducing the risks that scare investors away. Disputes with governments or communities create uncertainty, drive up costs, and make the entire sector less attractive to capital. By fostering trust, ensuring fairness, and addressing the concerns of all stakeholders, good governance benefits communities and governments, but also the private sector.
Good governance is also a shared responsibility. Our research identified more than 50 cases of corruption in the licensing and contracting of transition minerals projects alone, with cases found in 10 African countries. The companies involved are often based in the world’s wealthiest or most powerful countries, including Australia, Canada, China, Russia, Switzerland, the UK and the US. Each is a signatory to the U.N. Convention Against Corruption, which requires countries to criminalize foreign bribery and—except for China—signatories to the OECD Anti-Bribery Convention. Yet, Transparency International’s latest Exporting Corruption report found that only 2 of 47 countries analyzed are actively enforcing foreign bribery laws (the U.S. and Switzerland). Unless wealthier countries do more to hold companies based in their jurisdictions to account for wrongdoing, African countries will continue to suffer the consequences and we will not reach the fairer, greener world that current and future generations deserve.
The UN Panel on Critical Energy Transition Minerals is an opportunity for catalytic actions that bring together the voices, the resources and the global leadership necessary for Africans and Africa to at last see benefits from their minerals.
Nagpal:
How can African governments move along the value chain given the persistent challenges such as energy and infrastructure bottlenecks? What role should regional cooperation and global actors play in ensuring that value addition can advance?
Kaimal:
From our work with governments and citizens all over the world, we’ve seen the challenges of building new visions that move beyond the traditional mining model and deliver economic value, along with social and environmental benefits.
A key takeaway from our work is that the root of successful value addition is a clearly articulated strategy. Such a strategy helps inform government decision-making on the amount of political capital, time and money to spend, or what trade-offs to accept. It also attracts investment by signaling that a government has a plan that accounts for economic realities and the current impediments and how to overcome them.
A successful value addition strategy must be rooted in the goals of the national development plan, account for economic feasibility, market outlook, rigorous cost-benefit analysis, and include robust, transparent, public engagement. The strategy must also consider individual minerals and stages of the value chain. While Indonesia has learned the hard way, its differentiated approach to value addition—focusing on nickel given its dominant position and taking a more gradual approach with bauxite and copper—is the type of nuance that is required.
Understanding, assessing, and, where possible, increasing the feasibility of value addition is critical to ensure that value addition is more than hype. Governments must consider key drivers of feasibility such as the size of the mineral supply, the transport costs, availability of competitively priced, reliable, clean energy, competing capacity elsewhere, and good governance.
To return to the example of Ghana—in the absence of a clear competitive advantage, most of the gold refineries constructed in Ghana are lying largely idle due to a combination of profitability constraints. Or take Australia, where the government has had to provide subsidies for several decades to keep the country’s aluminum smelters operating.
There are ways to increase the feasibility of value addition—this is where regional cooperation matters. Cooperation between countries can increase economies of scale for value addition facilities, enable specialization of different components to support the production of more complex products and increase the size of the end market. The possible collaboration between DRC and Zambia on the battery value chain provides an example of what the continent needs.
But we know that cooperation is not easy. It must navigate an array of economic and political dynamics. Successful coordination in Africa’s mining sector has yet to materialize. One of the key drivers of future progress will be the capacity of regional and subregional bodies like the African Union’s African Minerals Development Centre, African Development Bank’s African Natural Resources Management and Investment Centre to plan, advocate for and support the implementation of coordination projects. These entities are doing important work with their limited resources, but those resources are insufficient for achieving transformative regional coordination.
This is where international actors can help. African governments and regional bodies must do the legwork to pave the way for fundable, beneficial projects, including by having a clear, evidence-based value addition strategies in place. However, development partners and governments seeking Africa’s minerals must finally step up and put real money on the table. This will support planning and policymaking capacity of African governments and regional bodies, and address the feasibility constraints. It’s in everyone’s interests that they do.
Managing tradeoffs is at the crux of any value addition strategy. For example, Indonesia’s downstream strategy has succeeded at dramatically increasing the percentage of nickel processed in country, but it also brings potential risks in terms of public health impacts in producing regions. As the government assesses the next steps in its downstream strategy, it needs to balance these factors carefully and ensure protections against harm.
Take Ghana—Its aluminum value chain ambitions bring with them the potential to increase the economic returns that the country generates from its mineral endowments. But the plans would require almost all the country’s hydropower capacity. Without other new competitively priced electricity capacity coming online, that will increase electricity costs for other businesses and households.
Unlocking Value Addition
Equitable value addition in mining can drive economic growth and prosperity for mineral-producing countries.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781