
National Dialogue on GNPC Today: Mandate, Delivery, and the Road to Operatorship in the Context of Energy Transition
Accra, Ghana

For more than four decades, the Ghana National Petroleum Corporation (GNPC) has occupied a central position in Ghana’s petroleum sector and broader energy system. Established under the Ghana National Petroleum Corporation Law, 1983 (PNDC Law 64), the corporation serves as the state’s vehicle for the exploration, development, production and disposal of petroleum, and continues to be the anchor partner in Ghana’s petroleum agreements.
The context in which GNPC operates, however, has changed significantly. Production from Ghana’s three producing fields has declined from a peak of 81.7 million barrels of oil equivalent in 2020, while significant resources in frontier basins remain undeveloped and the Keta and inland Voltaian basins remain underexplored.
GNPC has articulated an ambition to transition from a carried participant into a technically capable and commercially oriented national oil company. This includes deepening partnerships with experienced national and international oil companies and pursuing its commitment to drill its first well in the onshore Voltaian Basin by the end of 2026. Gas has also emerged as a strategic anchor, placing GNPC at the heart of Ghana’s energy security and industrial policy.
At the same time, GNPC faces significant constraints. These include tightening fiscal space, scrutiny of capital allocation and corporate social responsibility spending, and growing expectations around transparency, accountability and commercial discipline. Global energy transition dynamics, price volatility and geopolitical shocks are also increasing the risks associated with fossil fuel investments.
Against this backdrop, NRGI, in collaboration with GNPC, will convene a national stakeholder engagement to examine GNPC’s evolving mandate, performance and transformation ambitions at a critical moment for Ghana’s petroleum sector and energy future.
The dialogue will:
- Facilitate an informed discussion on GNPC’s evolving mandate, strategy and role in Ghana’s energy future.
- Examine operational and governance challenges, including fiscal sustainability, subsidiary structures, accountability and progress toward operatorship.
- Consider how GNPC’s transformation can align with Ghana’s energy transition, fiscal realities and long-term development priorities.
- Generate stakeholder perspectives to inform the ongoing operational and legal assessment of GNPC.
Interested in attending?
Individuals interested in attending the national dialogue are invited to indicate their interest by sending an email.
Featuring NRGI's
Nafi Quarshie
Africa Director
Patrick Stephenson
Ghana Country Manager

Angela Puplampu
Ghana Program and Administrative Associate

Damilare Ogunmowo
Africa Communications Officer
How South–South Learning Is Shaping Mineral Value Addition Strategies

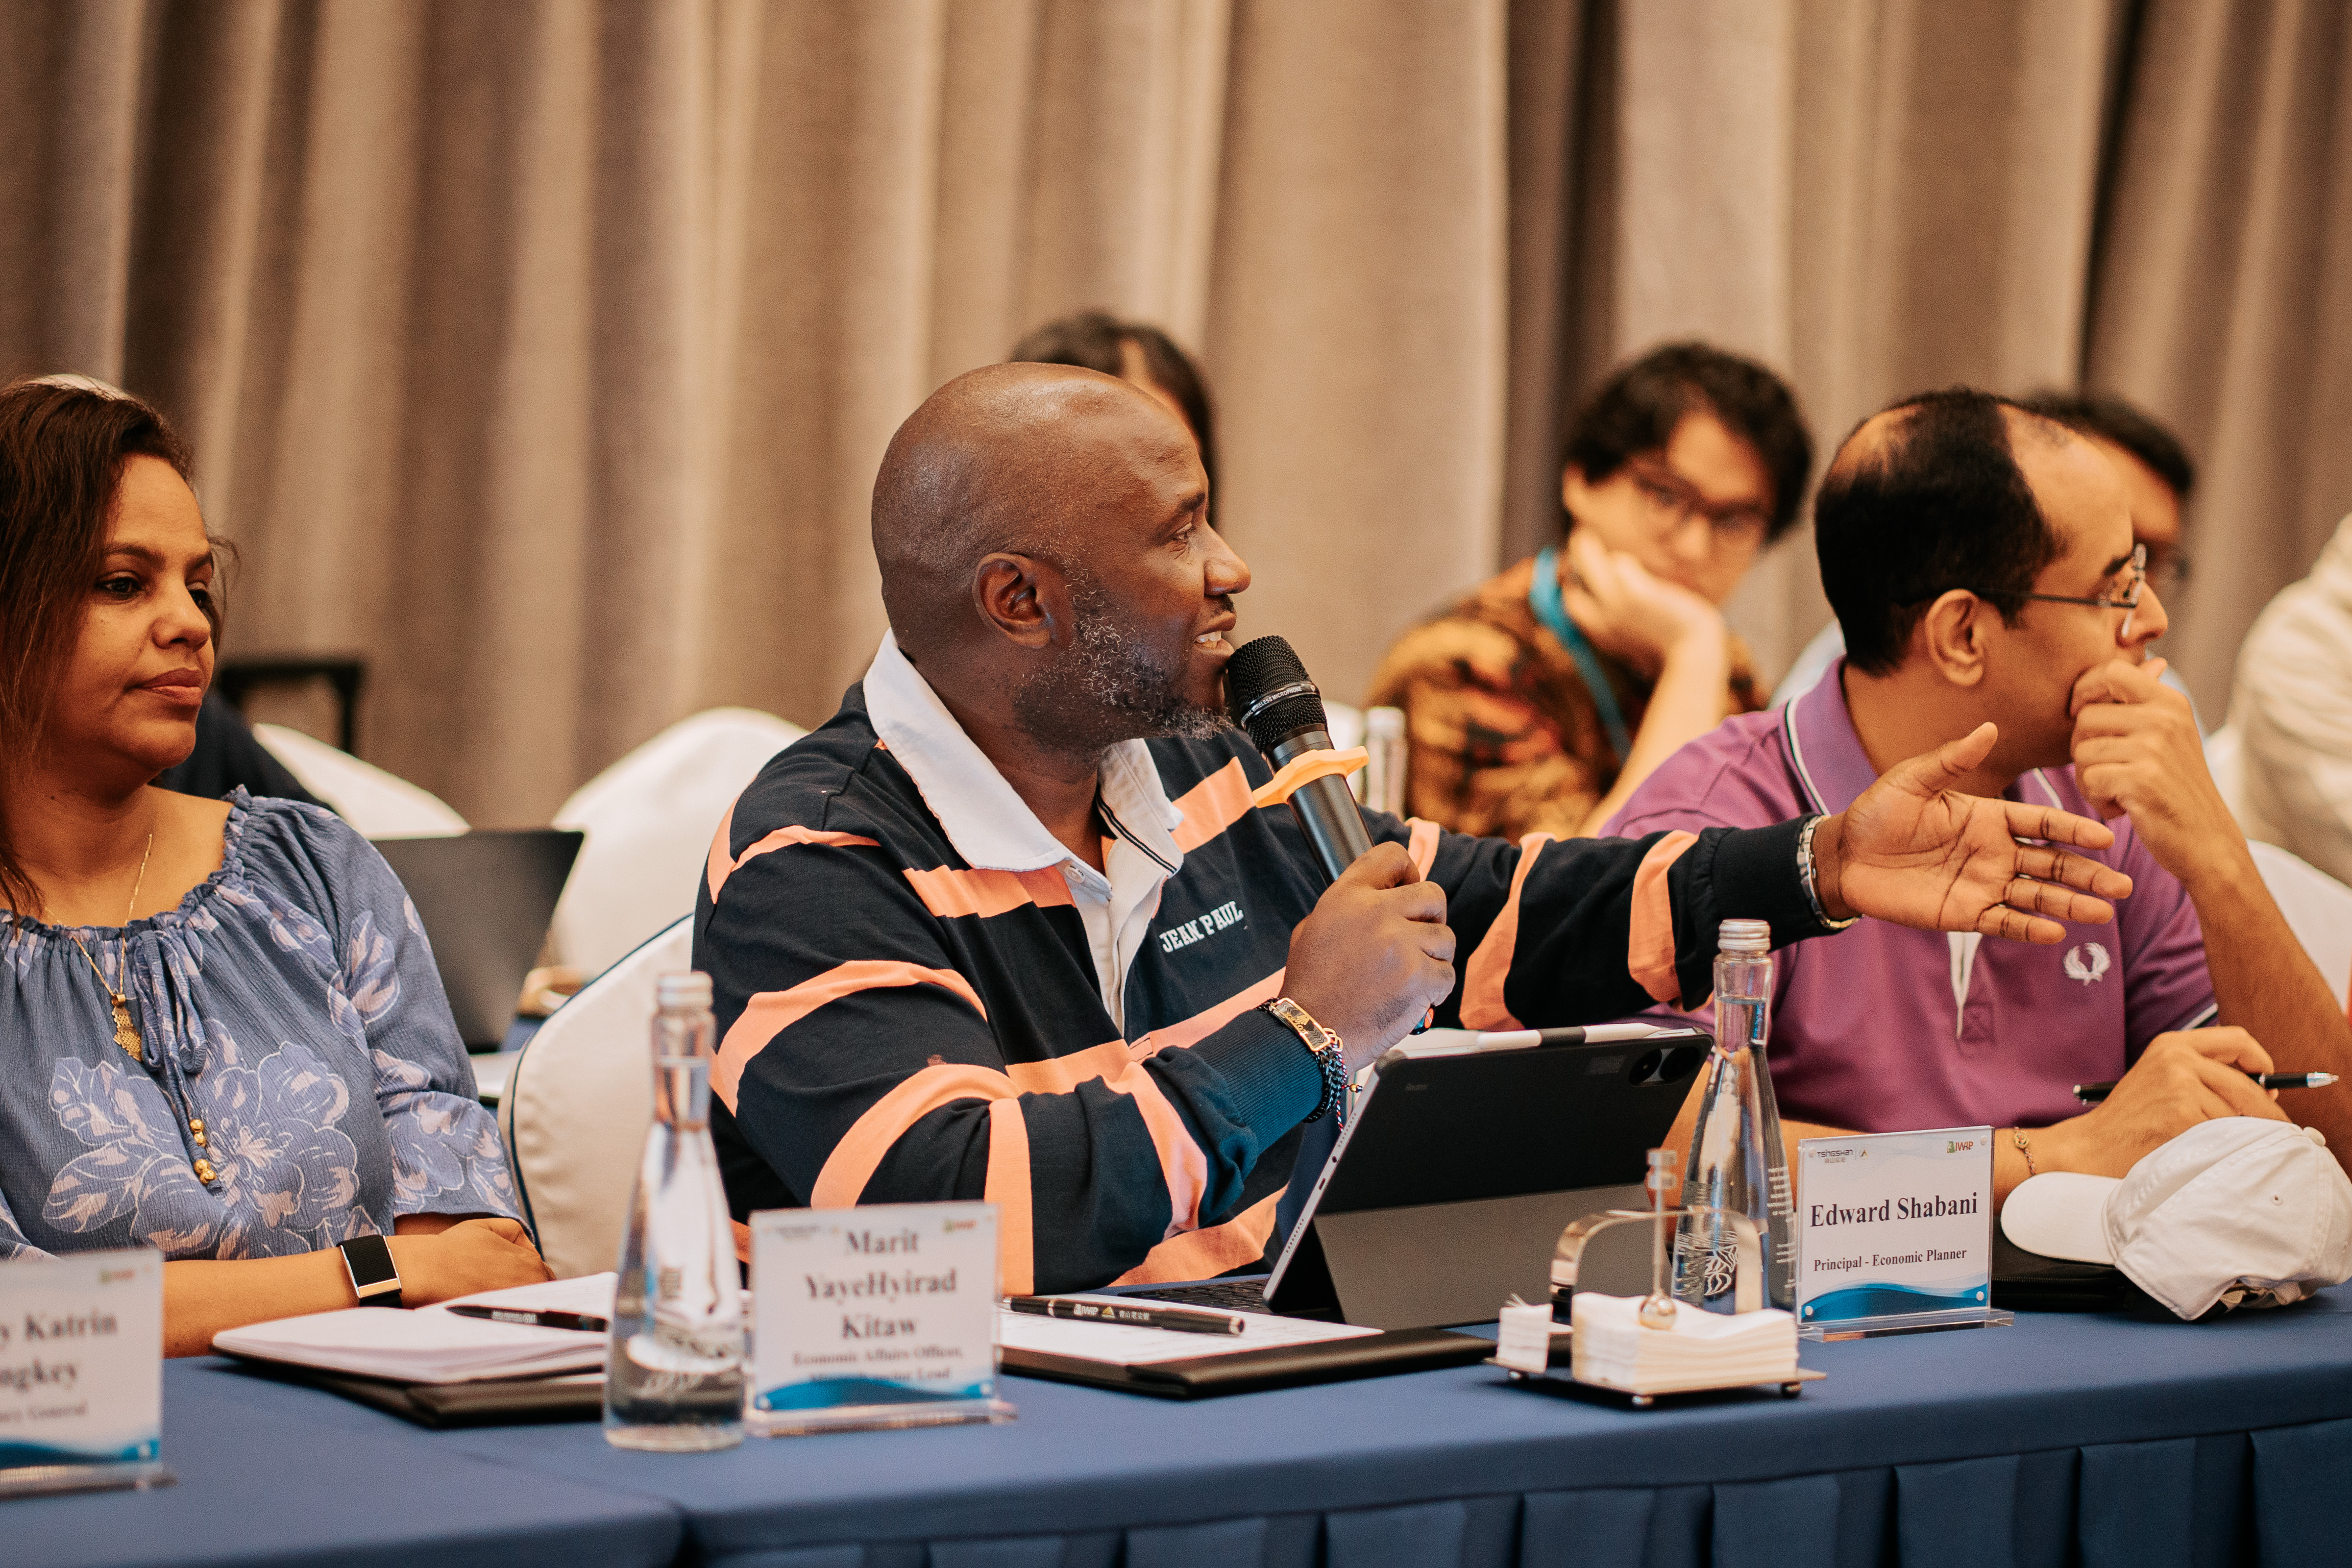
As governments across the Global South seek to increase the benefits derived from their mineral resources, questions about how to move along mineral value chains, and at what cost, have become increasingly urgent. Against this backdrop, government officials from Africa, Asia and Latin America gathered in Indonesia in early December for a South-South intergovernmental dialogue on unlocking equitable mineral value addition.
The dialogue was co-organized by Indonesia’s National Economic Council and the Natural Resource Governance Institute (NRGI), with support from ViriyaENB. Officials from 10 countries—including Chile, the Democratic Republic of the Congo, Ghana, Indonesia, Mexico, Mongolia, Morocco, the Philippines, Zambia and Zimbabwe—participated alongside representatives from intergovernmental organizations, research institutions and development agencies.
Throughout the week, participants exchanged experiences, ideas and lessons on how Global South countries can use their minerals to drive sustainable development, including by moving along mineral value chains. The dialogue opened with government officials reflecting on how shifting global markets and geopolitics are reshaping opportunities and constraints for value addition, and how these dynamics are influencing national strategies. Participants also discussed the role of external partnerships and international public finance in translating strategy into practice.
These conversations were informed by a two-day site visit to the Indonesia Weda Bay Industrial Park (IWIP) in North Maluku, which offered a first-hand look at one of the country’s most significant mineral-processing hubs and the practical complexities and trade-offs involved in industrialization.
The final day broadened the lens further. Engagements with a wider group of Indonesian policymakers, industry representatives, academics, civil society organizations and development partners highlighted both the economic potential of value chain development and the environmental, social and governance (ESG) challenges that accompany it. Officials from other countries reflected on which aspects of Indonesia’s experience might be transferable to their own contexts and what forms of cross-country learning and adaptation could most effectively inform policy development. These conversations fed into deeper exchanges on strategy and industrial policy, investment attraction and partnerships, ESG and community impacts, and the institutional and political arrangements that underpin implementation.
Amid these rich discussions, six key takeaways emerged.
1. An increasingly complex global landscape for value addition
With global demand for minerals booming and the push for diversified supply chains intensifying, a window of opportunity has emerged for establishing value chain activities in new locations. Yet mineral-rich countries in the Global South face mounting obstacles to realizing their value addition ambitions. China continues to dominate critical stages of many mineral value chains and is increasingly deploying export controls on technologies, manufacturing equipment and key materials. In response, other major economies are channeling large amounts of public finance into their own industries while—particularly in the case of the United States—seeking to narrow the policy space available to Global South countries, including by pushing back more aggressively against export bans and partnerships with geopolitical rivals.
2. Different value chains, different strategies

This complex landscape reinforces the need for value addition strategies tailored to the specific opportunities and constraints of each value chain. Discussions reflected a shared recognition that not all forms of value addition are feasible, desirable or a priority in every context. Participants highlighted how differences in global market share, infrastructure requirements, technology risk, environmental and social impacts and broader economic needs shape government approaches—including how countries distinguish between near-term, “no-regret” opportunities and longer-term, higher-risk bets.
“The event has increased my awareness of the breadth of the industry policy toolkit and how its use should reflect the idiosyncrasies of individual countries.” - Martin Latorre, University of Chile
3. Long-term visions that are ambitious but iterative
Discussions underscored the importance of anchoring value addition strategies in long-term national visions that can survive political cycles and provide confidence and predictability for investors. Participants noted that countries which have made progress have sequenced investments and policy reforms—such as value addition requirements and local content targets—over time, while recognizing uncertainty and learning as inherent features of industrial transformation. This calls for governments to adjust course as markets, technologies and domestic conditions evolve. Close and sustained engagement with the private sector emerged as a critical success factor, highlighting the role of trust, transparency and open communication between governments and investors.
“The field visit was an eye-opener, reinforcing how much strategic focus and discipline matter for advancing equitable value addition.” - Marit Kitaw, U.N. Economic Commission for Africa
4. Intra-governmental coordination is vital but often elusive
Designing and implementing effective value addition strategies requires close alignment across multiple ministries and agencies, yet many countries struggle to achieve this in practice. Participants highlighted how fragmented responsibilities, overlapping mandates and inconsistent communication often undermine coordination across mining, energy and industrial policies, as well as sufficient integration of environmental and social considerations into decision-making. Successful approaches combine clear chains of command with formal mechanisms for interagency collaboration, backed by sustained political support.
“This event will help me advocate for institutionalizing coordination among key ministries in my country to have one voice and be on the same page.” - Shorai Kavu, Ministry of Energy and Power Development, Zimbabwe
5. A multistakeholder approach and clear communication are key
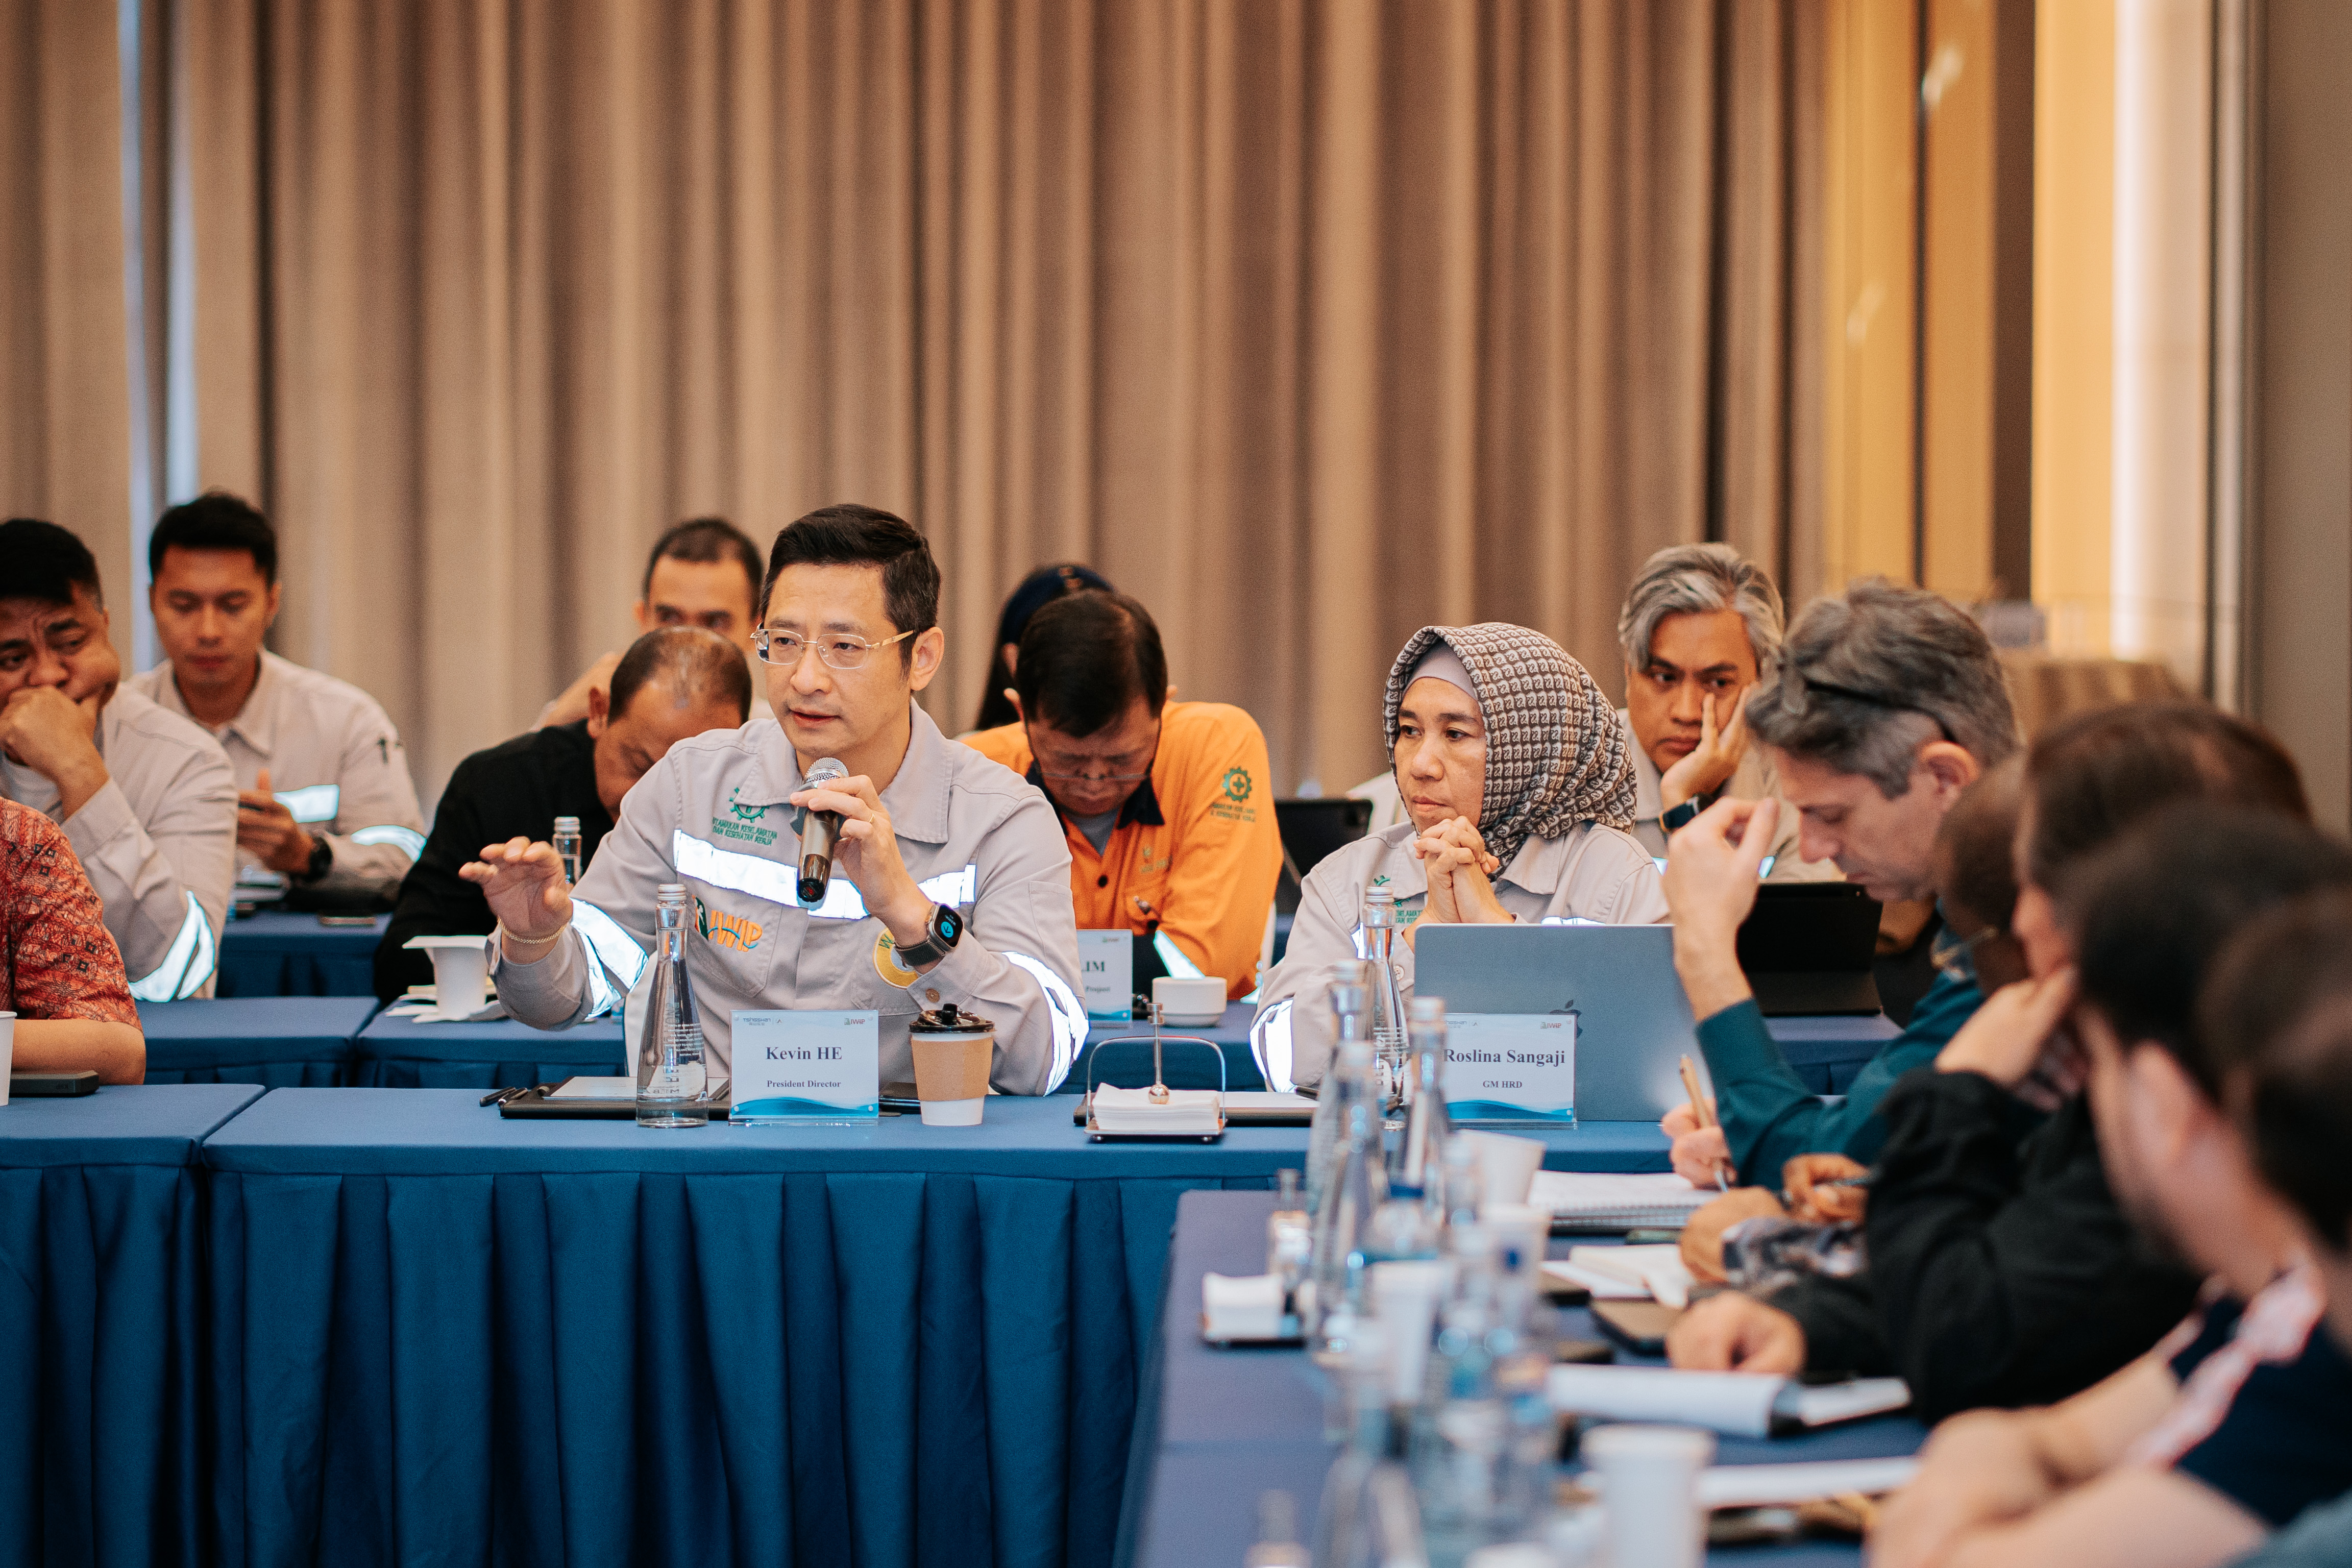
Value addition strategies involve trade-offs, take time to deliver results and, even then, may not fully meet public expectations. Participants noted that even well-designed strategies can falter if governments fail to bring citizens along, leaving policies vulnerable to pressure and reversal. Meaningful consultation and sustained engagement with a broad range of stakeholders are therefore essential. Governments need to clearly communicate objectives, timelines and expected benefits to build public trust—particularly in countries with histories of unfulfilled resource promises. Transparent, data-driven narratives presented in accessible language can help sustain political support across electoral cycles and strengthen the credibility of long-term policy commitments.
6. Strategic neutrality and the potential of South-South collaboration
In the face of intensifying geopolitical manoeuvring, many Global South countries are pursuing strategic neutrality through diversified partnerships that preserve policy autonomy rather than alignment with any single bloc. Participants discussed South–South cooperation as a key mechanism for enabling such neutrality. By coordinating rather than competing, countries can strengthen their bargaining power, reduce vulnerability to external pressures, and explore collaboration on standards, skills development, regional infrastructure and continued mutual learning. Cross-country learning was seen as particularly valuable for confronting shared challenges, reducing information asymmetries with major consumer countries and collectively exploring policy innovation.
“This event showed that South-South collaboration on critical minerals is possible—turning economic fragmentation to mutual benefits across the Global South.” - Niwa Rahmad Dwitama, Ministry of Foreign Affairs, Indonesia
Participants explored opportunities for continued dialogue and action—including a South–South Transition Minerals Learning Platform to be piloted by officials and researchers from a subset of participating countries, alongside future iterations of the broader intergovernmental dialogue. Through these mechanisms, South-South learning can support governments to make informed choices on mineral value addition.
Quotes have been lightly edited for clarity and length.
From Minerals to Development: New Connections for a New Era

As leaders gather in New York to discuss how the UN can advance the principles and recommendations of the Secretary General’s Panel on Critical Energy Transition Minerals, Lisa Sachs, of the Columbia Center on Sustainable Investment, shares why now is the time for long-term resource governance practioners to ask new questions, be honest about where we have fallen short, and join our work with other, related sectors.
For twenty years, those of us working on resource governance have been making the case that mining sits at the heart of sustainable development, and that resource-rich countries can convert their mineral wealth into broad-based development. A robust field grew to tackle the multidimensional challenges of resource governance with increasingly sophisticated tools: open fiscal models, contract databases, model laws, global multi-stakeholder initiatives, consolidated industry standards, and many trainings. In doing so, without quite noticing, those working on resource governance built a field with its own terms, boundaries, and sense of itself as complete. And yet, despite steadily better tools, the trajectory for resource-rich countries has not changed as we hoped.
Better tools, familiar challenges
Minerals are more central to the global economy than ever, and we are still asking many of the questions we asked two decades ago. Conflicts over land, fiscal promises that go unmet, environmental damage, projects stalled by mistrust; both the headlines and the framing questions at conferences are reminiscent of two decades ago. Few mining communities are meaningfully better off, and a quarter century into the era of transparency (of contracts, payments, and budget), we often cannot say how value is divided. From what we can see, wealth has not meaningfully improved the lives of the citizens of many resource-rich countries. Two years ago, the UN Secretary-General convened a multi-stakeholder panel on critical minerals, framed around not repeating the patterns of extraction and exploitation; a call to action that reflected concern from low and middle income countries that two decades of effort had not bent the curve. The panel worked admirably (and swiftly) to produce a report that consolidated twenty years of recommendations. But it did not grapple with why those efforts had fallen short.
Part of the answer is that resource-based development is genuinely hard. A single project involves multiple companies, a national government, local and regional authorities, the communities on the land, financiers, off-takers, and the home governments of the investors, each with its own interests, time horizon, and leverage. Geography compounds the challenge: value chains are spread globally: the mine in one country, processing often elsewhere, and the market in yet another country, with value and impacts unevenly distributed. And much of what determines the outcome happens behind closed doors.
Even when the terms are known, we are not agreed on what a ‘good deal’ looks like. For some, a fair outcome is one where the state captures the bulk of the value and the project advances the country’s own development strategy. For others, the measure is whether communities who bear the impacts negotiate their own terms. There is no agreed standard for decisive terms like shared-use infrastructure, dispute settlement, closure liabilities, audit rights, or the corporate structuring behind a deal's tax and legal exposure.
The benefits and the costs of mining fall unevenly by their nature: revenue accrues to the capital while the disruption lands on the community, gains arrive over decades while costs arrive at the start, one generation consents and another lives with the result. A deal can be fair to the state and unfair to the people nearest the mine; fair at signing and unfair twenty years on. While those of us in the field have at times recognized some of the inherent tensions and trade-offs, we have rarely found a framing that holds all of these elements in view at once. Part of the reason is that the field is divided along the same lines as the trade-offs: experts often specialize in one area: fiscal terms, community benefit, environmental and legal safeguards, dispute settlement, corruption.
When we do come together to talk about these intersectional components, we continue to do so within the framing of the natural resource sector as its own field, with its own technical features, institutions, standards and debates. But treating resource governance as self-contained is precisely what has kept it from working. We have become very good at governing the mineral and have left the system that gives the mineral its value to others. In reality, resource governance is a challenge inseparable from the larger fields of development, geopolitics, and international finance. Whether a mineral endowment becomes development is decided by the capital that builds power systems and ports, by the energy planning that determines where processing is viable, and by the international financial architecture that determines fiscal space and borrowing costs, and by geopolitics with its ever-powerful carrots and sticks. Resource governance is inherently part of all of this, and shaped by it at every turn. Yet the field has built its standards, its contracts, and its transparency mechanisms largely apart from the international financial institutions, the energy planners, and the fiscal, financial, and public-investment decisions that set the result.
This is a rare moment of attention for a set of issues that spent years at the margins. Minerals are in the news daily, capital and political attention have returned, and new actors who have never worked on resource governance are shaping the agenda. Many arrive as if there had never been a field at all, which risks discarding two decades of hard evidence about what works and what does not. But it is also telling that these new actors are finding the field largely the same as we found it twenty years ago.
Why now is the time to rethink
For those of us who have been working in the field for decades, there are two powerful reasons that now is the time for a rethink. First, several of the most physical constraints to resource-based development have shifted. Clean power can now be produced affordably and locally where the planning is done to support it. Markets that were assumed to be global and centralized are becoming more regional, as more regions move to build their own capacity and secure their own supply. And the recognition that integration and regional coordination are necessary has grown. And second, supply-security concerns and the return of industrial policy have opened real room for integrated, development-oriented strategies that were politically unattractive a decade ago. The barrier to integrated, development-oriented resource strategies is now mainly institutional and architectural: whether the field organizes itself to work across the systems it has always been part of.
The most valuable thing twenty years of work leaves us with is not fixed answers but a set of hard-won learnings, including, most importantly, the limits of the approaches we have tried. Those who have spent decades in this field should not cling to what we have been trying this whole time; that would be misreading both the evidence and the moment. Defending a position we have held for so long risks entrenches an old framing even as its assumptions prove flawed and the systems beneath it move.
But the depth of experience is critical: we know what was tried, what mattered, and why earlier efforts fell short. When the same questions are asked anew, the institutions and individuals who have engaged deeply in that work are best placed to reflect on how to think differently about the questions and the answers, so that we do not repeat the patterns of the past. Doing so requires a level of reflection and reckoning that may be uncomfortable to longstanding leaders in the field. And yet, knowing the terrain well enough to reframe the question – and push the conversation forward, rather than defend or replay the past, is an essential contribution two decades in this field can offer.
The task now is to foreground the interconnections, where the outcomes are actually decided. A processing facility is viable when the energy system has been planned to power it affordably. A mineral corridor pays off when the transport and the industrial capacity around it are sequenced together rather than negotiated piece by piece. Shared water infrastructure can serve the mine, the farms, and the cities downstream when it is planned at the basin level rather than built in parallel. An endowment becomes development when its financing is tied to a costed investment plan inside a national or regional strategy. A larger government take and a tangible community benefit become less of a fight over a fixed sum when the project is built into a development strategy that enlarges what there is to share. Affordable power, regional markets, and secured demand come together when they are sequenced as one. Seen as one system, the trade-offs that looked fixed start to give.
This matters to the people who fund the work as much as the people who do it. The opportunity is to back new thinking—including interdisciplinary work that does not fit neatly in any one silo. To draw on the people who carry decades of experience, not to ask them to defend what they built, but to ask what it taught. That work matters now in a way it has not before, with the questions open again and the moment ready for different answers.
Lisa Sachs is the Director of the Columbia Center on Sustainable Investment (CCSI). She is a globally recognized expert and leading voice on climate finance, sustainable investment, and natural resource governance, and a leading voice on how laws, policies, and financial architecture shape global investment flows in support of development and climate objectives. She advises governments around the world along with multilateral development banks, UN agencies, and intergovernmental organizations, and works closely with companies, investors, and civil society to translate research into practical policy and investment reforms. Lisa contributed this piece as part of NRGI's 20th anniversary thought piece series on the future of resource governance.
New Challenges, Enduring Lessons: The Future of NOCs in Sub-Saharan Africa

Nicolas Lippolis is Founder and Executive Director of the Centre for Energy, Finance and Development (CEFD) and contributed this piece as part of NRGI's 20th anniversary thought piece series on the future of resource governance.
The accelerating global energy transition has placed national oil companies (NOCs) under growing scrutiny. NRGI, among other civil society organizations, has extensively documented NOCs’ exposure to transition risks, including potentially stranded assets, long-term demand contraction, and tightening access to external finance. At the same time, it is increasingly acknowledged that NOCs can also play a constructive role in the energy transition by leveraging their capabilities to support decarbonization and broader economic transformation.
To unlock their potential to deliver both economic transformation and just energy transitions, African NOCs require tailored, nuanced analysis. Unlike in many other regions, NOCs in Sub-Saharan Africa function primarily as sector regulators rather than integrated operators. Their historical mandate has been to maximize state revenues and ensure domestic energy supply, including through the development of mid- and downstream sectors—but not necessarily to lead technological innovation efforts. This difference is essential for understanding how these companies have responded to the sector’s transformations and what paths lie open before them.
Today, African NOCs find themselves at the intersection of several powerful trends. Governments across the continent continue to face urgent development priorities, including expanding energy access, supporting industrialization, and generating fiscal revenues. These pressures help explain why many governments continue to view hydrocarbons as part of their development pathway, even as the global energy transition accelerates and questions are raised regarding the long-term viability of hydrocarbon-based development strategies.
At the same time, many international oil companies (IOCs) have been retreating from African upstream assets due to declining basin attractiveness, portfolio reassessments, and, in some cases, challenging operating environments. This changing landscape makes the strategic choices facing African NOCs more consequential than ever.
Financing choices in reaction to a changing global energy landscape
Recent IOC divestments from mature hydrocarbon assets in Sub-Saharan Africa have produced two broadly distinct classes of response, depending on the size and institutional maturity of producer countries.
In smaller producers, NOCs have been mobilized to take over oil blocks vacated by IOCs. The risks here are considerable and, in some cases, already materializing. A notable case is that of the Gabon Oil Company’s (GOC) US$1 billion acquisition of six oil blocks from Assala Energy. The deal was financed through an oil-backed loan from commodity trader Gunvor that granted the trader unusual latitude over pricing and cost calculations, and has added further financial stress to a state already allocating over half its expenditures to debt service.
In a smaller but structurally similar arrangement, in the Republic of Congo, the SNPC (National Petroleum Company of Congo) has reportedly contracted a US$200–300 million loan from Geneva-based trader Mercuria to acquire Eni’s rights over the M’Boundi oil field. The transaction has attracted criticism—observers argue that SNPC is assuming control of a mature and potentially declining asset despite lacking the technical and financial capabilities needed, meaning the acquisition could prove more burdensome than profitable.
An even more brazen transaction was avoided in Ghana in July 2021, when a coalition of civil society organizations successfully opposed the Ghana National Petroleum Corporation’s proposed US$1.65 billion acquisition of Aker Energy’s offshore assets after uncovering a Bank of America appraisal valuing the oil field at just US$300 million. The asset was eventually reverted to Ghana at no cost, further underscoring the potential harm of the proposed deal.
Senegal, a new producer, has so far not replicated this approach, despite some signs of increased NOC ambition. Following the exit of BP and Kosmos Energy from the Yakaar-Teranga gas field, Petrosen has expressed interest in taking over the project. However, the financial commitments and technical requirements involved appear to exceed the Senegalese state’s current capabilities, particularly considering its worsening sovereign debt crisis. Its delicate financial situation has, however, not held it back from announcing ambitions to engage in onshore exploration or to build a new refinery. Supporters of a greater role for Petrosen argue that increased national participation could help secure domestic gas supplies, support gas-to-power ambitions, and capture a larger share of future project revenues.
Responses in mature oil economies: Nigeria and Angola
Responses differ in Sub-Saharan Africa’s two largest producers, which possess the region’s most mature oil sectors. While some companies are pursuing corporatization and commercial restructuring, others remain primarily regulatory entities with limited operational responsibilities and very different reform priorities.
In response to declining production and subdued IOC investment, the Angolan and Nigerian governments introduced legislative reforms—in 2019 and 2021, respectively—that established more arm’s-length relationships between NOCs and oil sector policymaking. This was a deliberate effort to reduce the conflation of regulatory and commercial functions that had historically characterized both Sonangol and NNPC (formerly “Nigerian National Petroleum Corporation”). Besides improving the credibility of oil sector reforms, the “corporatization” of the two NOCs is intended as a first step toward eventual access to domestic stock markets and international private capital.
The results have been uneven. In Nigeria, the NNPC was restructured into a limited liability company (“Nigerian National Petroleum Company Limited”) in 2022, though it remains entirely government-owned, with no set date for the proposed stock market listing. NNPC’s corporatization has nonetheless been accompanied by improvements in corporate disclosures and the creation of a new Sustainability Department, which, together with a strengthened NNPC New Energy Limited (NNEL) subsidiary, is leading efforts to respond to the decarbonization of the global economy.
In Nigeria, natural gas sits at the center of energy transition policy. Accordingly, NNPC has recently published a Gas Master Plan intended to support the government’s Decade of Gas agenda through gas commercialization, infrastructure development, power generation, gas-based industrialization, liquefied petroleum gas (LPG) expansion, and the elimination of routine gas flaring. However, upstream hydrocarbon production has been disappointing, leading to a wholesale change in the company’s leadership and board in 2025.
The corporatization of Angola’s Sonangol, largely considered the region’s most competent NOC, has also faced some hiccups. Sonangol’s role in Angola’s oil economy was significantly downsized following the creation of a new regulatory agency in 2019 and the divestment of most of its assets in non-core areas of activity, allowing the company to focus on obtaining better value from core commercial operations. Yet while Sonangol’s profitability has improved, the promised domestic listing of 30 percent of its shares has been repeatedly postponed, with the latest date set for 2027. The listing process has been complicated by the challenges of advancing corporate governance reforms, rationalizing an oversized workforce, and reconciling commercial objectives with Sonangol’s continued involvement in strategic public investment projects such as refineries and oil storage terminals. Together, these activities underscore the company’s enduring role as a central instrument of state policy (Heller, 2011).
Sonangol’s strategic role is also reflected in its growing involvement in the new “green economy.” The company has built two solar power plants, in partnership with Azule Energy (a BP–Eni joint venture) and TotalEnergies, respectively. It has also acquired licenses to explore for critical minerals, reflecting Angola’s growing ambitions for the sector. These initiatives reflect a broader trend among some African NOCs to explore opportunities beyond traditional oil and gas activities, although the commercial viability and strategic coherence of such diversification efforts remain uncertain.
The Way Forward for African NOCs
Variations in the recent trajectories of African NOCs suggest that the way forward is not uniform, but is best conceived as a gradient that tracks the institutional development of each company. Any assessment of African NOCs should recognize that the continent faces a dual challenge: managing transition-related risks and opportunities while simultaneously addressing persistent energy poverty and infrastructure deficits. Effective reform strategies will therefore need to balance long-term climate considerations with near-term development and energy security objectives.
As shown by questionable investments in Gabon, Ghana, and Congo, the classic transparency agenda promoted by NRGI remains essential for less institutionally consolidated NOCs, where companies must increase the transparency of their oil sales, improve oversight of their activities, and strengthen corporate governance.
Tackling the NOC-commodity trader nexus could also go a long way toward preventing some of the most harmful transactions. Reform programs could address areas such as procurement, contract management, and revenue administration. In particular, it is important to strengthen regulatory and legal frameworks related to the selection of buyers, terms of sale negotiations, and contract awards for the sale of host states’ equity oil and the oil allocated to them in production sharing agreements. Rather than aspiring to wide-ranging governance reform, such targeted interventions would directly tackle sources of fiscal and illicit financial flow risk.
The challenges look quite different in the larger oil economies such as Angola and Nigeria, where IOC divestments have been relatively limited in the former or mostly taken over by domestic private operators in the latter. For both Sonangol and NNPC, the main challenge is to deliver on the mandates set by oil sector reforms and advance in their corporatization. This will entail introducing rigorous reporting standards, enhancing transparency and disclosure requirements, strengthening corporate governance mechanisms, and securing greater operational autonomy from political authorities, while reducing the influence of patronage structures that have historically shaped both companies. Here, African NOCs can draw valuable lessons from other NOCs that have undergone partial stock market listings, including Brazil’s Petrobras, Colombia’s Ecopetrol, and Norway’s Equinor.
At the same time, Sonangol and NNPC face the unique challenge of advancing their corporatization while still playing limited roles as operators and, in the case of Angola, facing projected declines in oil and gas production. Moreover, they are reforming at a time of heightened awareness of the risks posed by climate change and the global energy transition, which threaten their core business while also creating new opportunities for diversification.
In conclusion, there is no “one-size-fits-all” path to harness the full potential of African NOCs. Further nuanced research is essential, and could deepen comparative analysis across African producers, identifying lessons from both successful and unsuccessful reform experiences and examining how different institutional models affect transparency, financial performance, and resilience to energy transition risks.
Beyond research, the continued engagement between policymakers and civil society groups at national, regional, and global levels will be critical for progress. With its 20-year track record of combining robust analysis with trusted engagement, NRGI will no doubt remain an important source of comparative knowledge and a model for other civil society organizations seeking to promote the management of natural resources in the service of shared and sustainable prosperity.
U.S.-Iran Deal: How Africa Must Prepare for the Next Global Energy Shock

With the deal setting the stage to bring an end to hostilities, hopes across Africa are high that some of the worst impacts may soon subside. Already, oil prices have fallen to their lowest levels since the early days of the conflict, and stock markets across Asia and Europe have responded positively.
A distant crisis that hit home
The agreement may signal the end of a period of uncertainty. But for millions of Africans living in countries that rely on imported fuels to power their economies, the conflict has already created severe and long-lasting impacts. And even those in oil and gas-producing nations were not immune. Nearly 600 million people across the continent still lack access to electricity, and the World Economic Forum noted that energy bottlenecks and power shortages cost Africa an estimated 2 to 4 percent of GDP annually. As such, any crisis that disrupts energy supply compounds an existing deficit that holds back growth, jobs and investment for many Africans.
The conflict made that burden heavier for households and businesses, and extremely challenging for policymakers to manage. Higher energy prices drove up transport and food costs, forcing governments to choose between passing those costs on to citizens or absorbing them through measures that placed additional strain on already stretched public finances.
Ghana, where around two-thirds of electricity comes from gas-fired power plants and almost all refined fuel is imported, felt the shock when pump prices rose by 10-26 percent, threatening the government’s budget assumptions of 4.8 percent growth and a 13-month disinflation streak. The government introduced fuel subsidies, initially for a month, which were later extended for two additional months. While this partially cushioned the impact on Ghanaians, the full impact will only become clear over time, as this use of public funds for fuel subsidies will mean tough choices need to be made around essential public services.
Nigeria's experience was more mixed. Higher oil prices boosted export earnings, but despite the Dangote Refinery reducing fuel import dependence from around 90 percent to 40-50 percent, the country still saw a cost-of-living crisis worsen by approximately 17 percent.
If anything, the crisis has shown that while the impacts differ, both African producer and consumer countries are vulnerable to disruptions beyond their borders. But the vulnerability did not begin with the Middle East conflict. It reflects deeper structural realities of fiscal systems built around oil revenues, energy systems that rely on imported fuel and limited capacity to absorb shocks without passing costs to citizens.
Building resilience through economic and energy diversification
The immediate response to the crisis focused on managing its effects. But one important lesson African governments must take from this episode, as they plan their energy and fiscal future, is that subsidies, tax reductions and emergency interventions can cushion the immediate impact of higher oil prices, but they do little to address the underlying vulnerabilities that make such crises disruptive. Ghana’s subsidies were short-lived; Nigeria, despite significantly reducing its import dependence, still saw pump prices feed into a deepening cost-of-living crisis. Partial solutions to a structural problem only go so far.
The path to genuine resilience in the medium term lies in diversification at every level: away from fiscal dependence on crude exports, away from reliance on imported refined products and away from an energy mix dominated by fossil fuels. Decentralized renewable energy through solar and storage can reduce exposure to future oil price shocks while advancing energy access ambitions across the continent. Ghana’s push toward expanded gas-to-power investment and renewables points in the same direction — a recognition that for many African countries, energy transition and energy security are not competing priorities but part of the same resilience agenda.
Diversification alone, however, is not enough without better management of the revenues that flow from natural resources. Governments must ensure that windfall gains are saved in sovereign buffers rather than used for recurrent expenditure, and that stronger fiscal rules and transparent revenue management are in place to ensure genuine resilience.
There is also a need for stronger regional energy cooperation. The fragmented energy systems across the continent leave individual countries more exposed than they ought to be. Governments and regional bodies must ensure greater use of regional power pools and cross-border gas networks to enable flexibility when global supply chains are disrupted again.
Preparing for the next global energy shock
This week’s deal will ease pressure on global energy markets and that matters for Africans who have spent the past four months absorbing high energy, transport and food costs. But it is also a reminder of the vulnerabilities that African economies face.
The countries that emerge stronger will be those that use moments like this to make longer-term changes. That means investing in domestic energy capacity and renewables, building fiscal buffers during good times, managing resource revenues wisely and strengthening regional systems that can help countries support one another during a period of disruption.
There is an old saying “never waste a crisis”. The next energy crisis may not come from the Middle East. But it will come from somewhere. The lesson over the past four months is that resilience cannot be built during a crisis. It must be built before one arrives and the window to act on that understanding is now.
One Crisis, Seven Lenses : MENA’s Energy Transition at a Crossroads
What the 2026 energy shock means for the future of transition in MENA

In early 2026, the U.S.-Iran war and the closure of the Strait of Hormuz triggered the most severe energy supply shock in decades — disrupting global hydrocarbon flows and exposing just how fragile and interconnected energy markets are. In the Middle East and North Africa (MENA), the shock carried different meaning for fossil fuel producers trapped by the Hormuz closure, for other fossil fuel exporters, and for energy-importing countries. But for every government in the region, it landed on territory where energy is already a daily household concern, and where the transition to cleaner, fairer energy was only beginning to gain momentum.
The crisis pushed energy security to the top of every policy agenda in the region, while simultaneously raising new questions about the future of the transition itself. The same shock is pulling policymakers, investors, and communities in multiple directions at once. Which path prevails will depend on the choices made now.
That is why we set up the NRGI MENA Just Energy Transition Platform, as a space for knowledge production, dialogue, and advocacy among those committed to a transition that is not only faster but fairer, anchored in strong governance foundations. Among the community of experts, we work with an Advisory Expert Group to support and guide us — leading voices on energy, governance, and transition from across the region. In the weeks following the crisis, we put one question to this group: What does this moment mean for the future of energy transition in MENA? Each responded from a different vantage point. Read together, they converge on the same central tension.
The reflections below are short excerpts from longer contributions by members of the NRGI MENA Just Energy Transition Platform Advisory Expert Group. You can read their full analyses in the briefing available for download at the end of this page.
The Strategist's Lens — Dr. Manal Shehabi — Senior Research Fellow, University of Oxford; NRGI MENA Advisory Board
The crisis cuts both ways for MENA's energy transition. Gulf exporters, unable to reap their usual windfalls, are cutting long-term transition spending first. Oil importers like Jordan, Egypt and Morocco have the strongest incentive to accelerate — but the least fiscal room to do so. The same shock that makes the transition more urgent is also what makes it hardest to fund.
The Resilience Lens — Dr. Mohammed Al-Breiki — Head of Industrial Studies and Policies, Gulf Organization for Industrial Consulting (GOIC)
For the Gulf, the crisis is not a choice between hydrocarbons and transition — it is a push to manage both. Higher revenues are being directed toward resilience, economic diversification and deeper regional integration: energy grids, the GCC railway, strategic reserves. Hydrocarbons remain the source of stability while the longer-term shift is built.
The Trade-offs Lens — Sarine Karajerjian — Program Director, Environmental Politics Program, Arab Reform Initiative
The crisis forces fragile MENA governments to navigate five trade-offs at once: security vs. transition, centralized vs. decentralized power, fiscal stability vs. social protection, speed vs. governance, and diversification vs. geopolitical alignment. How they balance these competing pressures — not whether they transition — will decide whether the shift is fair or deepens existing inequalities.
The Gender Lens — Myriam Sfeir — Executive Director, Arab Institute for Women
The energy crisis hits women hardest: more unpaid work, less income, and deeper inequality. Yet policy continues to treat all households alike. Effective responses require gender-sensitive energy policy that sees who is actually absorbing the cost — and designs support accordingly.
The Civil Society Lens — Dr. Pierre Saade — Head of Middle East and North Africa, Resource Justice Network
Civil society's role is to bring big energy decisions back down to lived reality — the cost of cooking, transport, and electricity — and to ask who benefits and who bears the risk as pipelines and corridors return under the banner of energy security. As energy access grows more conditional and contested, democratic oversight and community accountability matter more than ever.
The Opportunity Lens — Dr. Jauad El Kharaz — Co-Chair, Mediterranean Clean Energy Network (MEDCEN)
What if the crisis is the opening, not the setback? A Mediterranean remade not as a fossil gas corridor, but as a global green energy hub — 1 TW of renewables by 2030, powering local industry, not just exporting to Europe. The political and financial momentum created by this crisis may be exactly what makes that ambition achievable.
The Media Lens — Roula Mikhael — Executive Director, Maharat Foundation
Media coverage of the crisis stays fixed on prices and shortages, missing the bigger story of structural transition — held back by limited access to energy data and varied editorial pressures across the region. Stronger technical expertise among journalists and a more constructive journalism approach could shift coverage from reactive reporting toward informed, accountable, and forward-looking public debate.
Seven lenses. One crisis. One central tension: whether the energy transition can survive a shock that makes it both more necessary and harder to fund.
The energy transition has become an energy-security argument, not only a climate one. The resilient path runs through renewables, grids, and decentralized systems — but it only holds if the people bearing the cost stay at the center, and the governance of fast deployment keeps pace with ambition. That is what the NRGI MENA Just Energy Transition Platform exists to ensure.
Read all seven perspectives in full — download the briefing: One Crisis, Seven Lenses
Beyond Oil and Gas: Regional Perspectives on a Transition Under Pressure

As more than 50 countries gather in Santa Marta for the first conference dedicated to transitioning away from fossil fuels, NRGI's regional directors share how governments are navigating competing pressures, and what this means for economies and communities
The energy transition is happening. It is also, depending on your perspective, too slow, too fast, too expensive, or something else entirely. As the governments of Colombia and The Netherlands convene the first-ever conference dedicated to transitioning away from fossil fuels in Santa Marta, that ambition is running up against a charged reality: oil price spike, land grabs, geopolitical jockeying for resources and mounting debt in many producer countries.
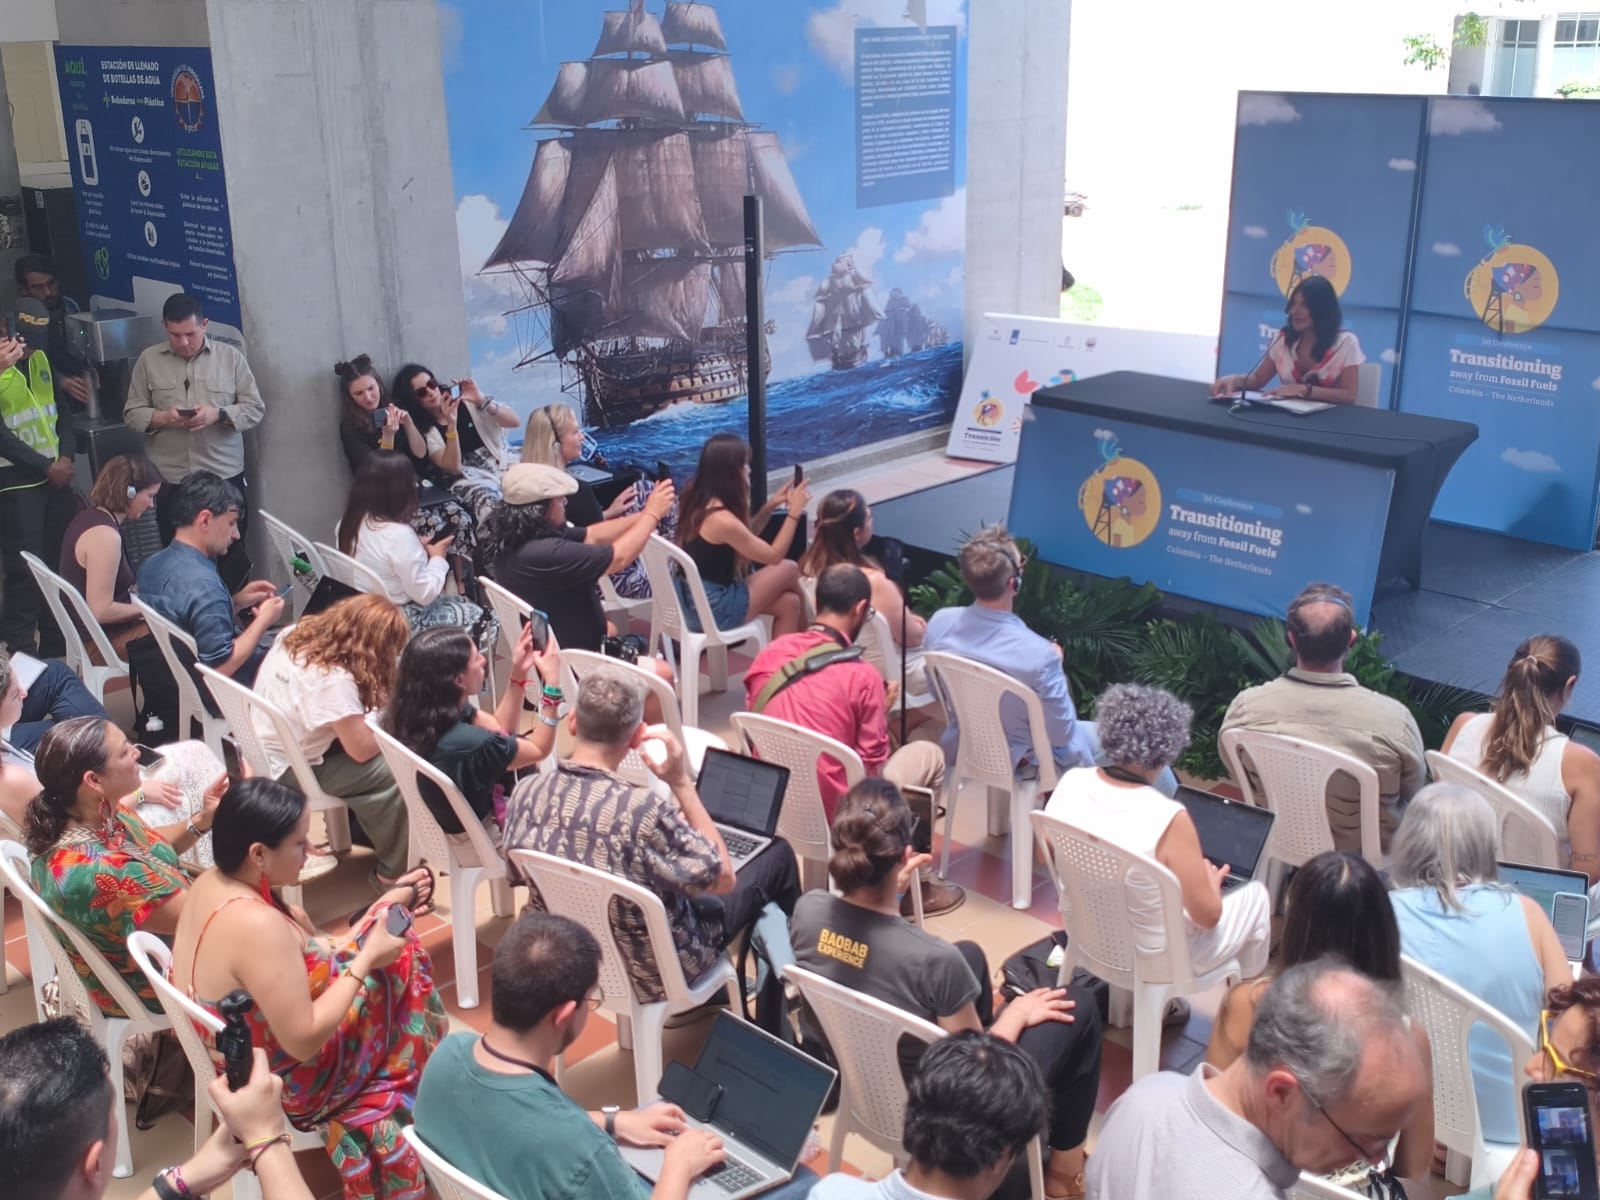
NRGI’s work is grounded in the recognition that how the transition unfolds—and how quickly—will determine whether it contributes to fair, inclusive and more prosperous societies, while acknowledging that communities that have contributed least to the climate crisis too often stand to lose the most. There is not one transition. There are transitions—shaped by very different starting points, economic realities and development priorities. Those gathering in Santa Marta must consider these diverse perspectives, including from communities, countries and regions that are not always fully represented in these debates.
Three of our regional directors reflect on how the transition is unfolding in practice, drawing on two decades of work on resource governance.
How are governments approaching the transition in the current context?
Santa Marta's organizers argue that current conflicts reinforce rather than sideline the case for transition. For governments navigating oil price uncertainty, rising energy demand and immediate security pressures, however, the picture is more complicated.
Africa—Nafi Quarshie, Africa Director
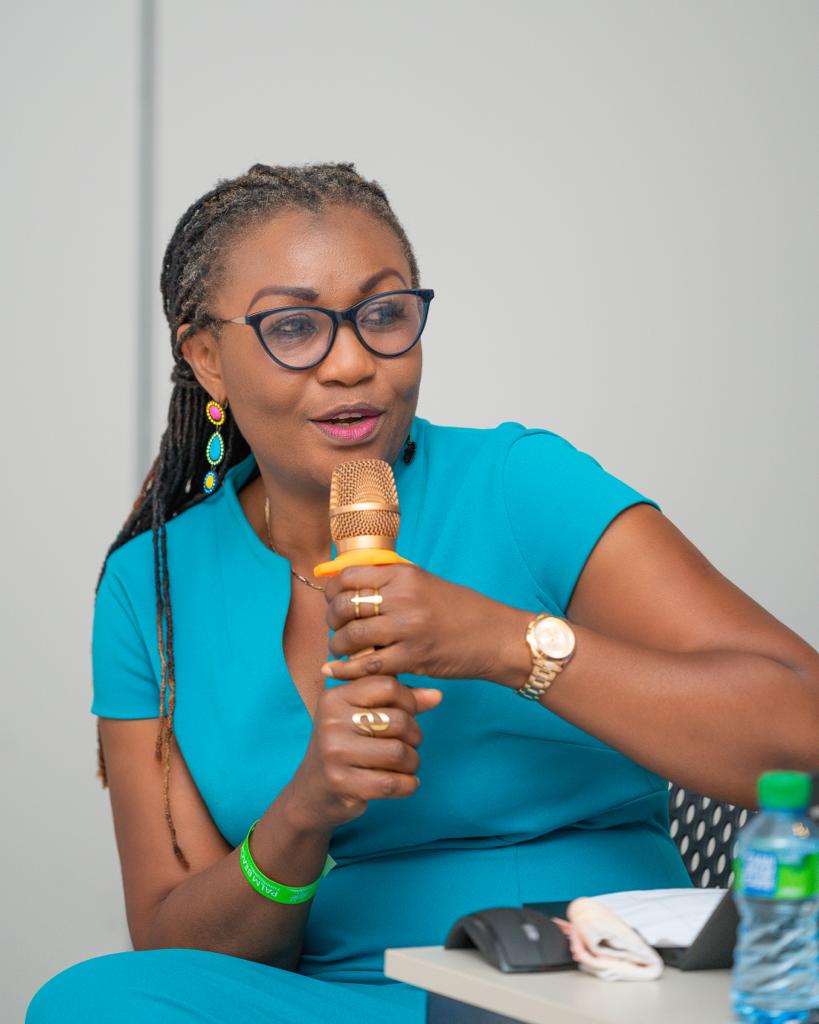
Latin America—Ana Carolina González Espinosa, Latin America Director and Senior Director for Programs
MENA—Laury Haytayan, MENA Director
The Price of Instability: Oil Shocks, Energy Transitions and MENA's Economic Future

The ongoing conflict in Iran, Lebanon and across the region is devastating lives and livelihoods, and driving significant uncertainty across the Middle East and North Africa (MENA). While much remains unclear, it is certain there will be far-reaching implications for economic stability, energy markets and policy trajectories—particularly in the Gulf Cooperation Council (GCC) countries and Iraq.
While much attention has focused on immediate effects, less explored are the medium- to long-term structural impacts on regional economies and energy strategies.
This webinar brings together leading experts from the worlds of business, politics and civil society to examine the "price of instability"—how the conflict may reshape oil and gas markets, fiscal stability, investment patterns and energy transition pathways across MENA. It will also explore how governments, especially in the GCC and Iraq, may adapt their policies in response to evolving risks and opportunities.
The discussion will combine energy market analysis, macroeconomic perspectives and geopolitical insights to provide a forward-looking view of the region’s resilience and strategic choices in a more volatile environment.
Speakers:
- Carole Nakhle, CEO, Crystol Energy
- Rola Dashti, Kuwaiti economist and senior public leader
- Lina Khatib, Associate Fellow, Chatham House
Moderator:
- Laury Haytayan, Regional Director, Natural Resource Governance Institute
This webinar will be conducted in Arabic with simultaneous English interpretation.
Corruption in Mineral Value Addition: Why It Matters

Many mineral-producing countries are pursuing value addition to capture more economic benefits from mining and strengthen their position in global supply chains. This briefing examines how corruption can undermine those ambitions—making value-addition efforts less fair, less reliable and more costly—and outlines practical steps to manage the risks.
Key messages
Value addition can make mineral supply chains fairer and more reliable—if decisions are made with integrity.
Corruption in mineral value addition is occurring across a wide range of countries, minerals and technologies, yet anticorruption is missing from many current initiatives. In some contexts, it is being actively weakened.
Politicians and companies in many countries are promoting value-addition projects that are unlikely to happen or to be economically viable. These claims deserve scrutiny.
Corruption in value addition undermines fairness by funneling wealth and opportunities to a privileged few, while harming vulnerable communities.
Corruption can also make mineral supply chains less reliable, delaying projects, discouraging investment and cutting output.
Governments, companies, investors and international initiatives can take concrete steps to mitigate corruption risks in mineral value addition.
This briefing explores how corruption can undermine efforts to promote mineral value addition, a growing priority for mineral-producing countries amid the energy transition and shifting geopolitical dynamics. Using real-world examples across regions, minerals and processing stages, it examines how corruption distorts policy choices, project selection and implementation, with consequences for fairness, public revenues, investment and supply-chain reliability. The briefing concludes with practical recommendations for governments, companies, investors and multilateral organizations.
Can climate action beat geopolitical headwinds in 2026?
Online

What can we expect in 2026 as countries enter the second half of this critical decade for climate action?
Speakers
Tulio Andrade - COP30 Chief Strategy and Alignment Officer
Tulio Andrade is the COP30 Strategy and Alignment Officer. Career diplomat since 2009, with postings in London and Tokyo. Served as Head for Climate Negotiation at Brazil's Foreign Ministry from 2023 to 2025, including at the 2023 Dubai Climate Summit (COP28), COP29, and the 2024 G20 Task-Force on a Global Mobilization against Climate Change (TF-CLIMA).
Jennifer Morgan - Senior fellow, Center for International Environment and Resource Policy and Climate Policy Lab, Tufts University.
Jennifer Morgan is currently a senior fellow at the Center for International Environment and Resource Policy and Climate Policy Lab at Tufts University. As State Secretary and Special Envoy for the Federal Foreign Office of Germany, she led the development and implementation of the groundbreaking Climate Foreign Policy strategy, which was approved by the Cabinet. Besides leading Germany’s delegation to the UNFCCC negotiations, she focused her time on building partnerships with developing countries and pursuing an all-of-society public diplomacy approach. She is a leading voice in the conversation on how foreign policy must evolve to address the urgent climate challenges of our time.
Erica Westenberg - Governance Programs Director, Natural Resource Governance Institute (NRGI)
Erica Westenberg is the Director of Governance Programs at the Natural Resource Governance Institute (NRGI). She is a lawyer and provides policy advice on transparency and good governance in resource-rich countries worldwide. Prior to joining NRGI, she was in the energy and infrastructure group at Skadden Arps, where she advised clients on energy, natural resource, and infrastructure projects and public-private partnerships in Asia, Latin America, the Middle East and the United States.
Alex Rafalowicz – Executive Director at the Fossil Fuel Non-Proliferation Treaty Initiative
Alex Rafalowicz has worked as a policy analyst, campaigner, organiser and strategist for climate justice for 15 years including with the Global Campaign to Demand Climate Justice, the Climate Action Network, and 350.Org. He has worked on digital and electoral campaigns across the Americas, Europe, and Australia. He has a first class honours degree in law from the Australian National University and Masters in Economics from the Indira Gandhi Institute for Development Research. He lives in Bogotá, Colombia with his family.