
The Connective Fabric of Natural Resource Governance: Reflections from UNGA and Climate Week

Last week, a delegation from NRGI attended the UN General Assembly and Climate Week NYC. Below are our reflections from across more than 20 sessions, side events, our 20th anniversary convening and meetings, with partners from government, civil society, Indigenous Peoples, multilaterals, philanthropy and industry.
Natural resources rarely dominate the headlines at the UN General Assembly, yet they underpin almost every item on its agenda. Whether conversations centered on climate, economic development, trade or geopolitics, the governance of oil, gas and minerals ran through many of them.
That role, however, too often remains implicit. Elevating resource governance as a priority is essential if global efforts on climate, development and security are to deliver equitable outcomes for producer countries and their citizens, and a healthy, sustainable future for all of us.
Security and trade have reframed the journey, but not the destination
Energy security has displaced energy transition as the dominant lens for energy policy, with decisions increasingly driven by geopolitics and cost of living rather than decarbonization. While the end goal of sustainable energy and economic futures remains, this marks a structural shift in the narratives that shape policy and in how influence is exercised.
In the minerals sector, a trade lens now dominates, even during a “Climate Week”. Green industrialization was a central theme, welcomed by some and viewed with skepticism by others. At a UN-hosted Solutions Dialogue on the subject, producer countries, particularly those from Africa, stressed that high costs of capital and limited fiscal space must not constrain their economic and trade ambitions. African participants were clear that the gap is now implementation, not strategy: frameworks such as the African Mining Vision and the Africa Green Minerals Strategy already exist. Because no single country holds every mineral, energy source, skill and market, enabling countries to achieve more value requires regional integration. The African Continental Free Trade Area (AfCFTA) serving as an industrial platform rather than only a trade agreement. Success, many argued, should be measured by the jobs, skills and productive capabilities retained on the continent, not by processing capacity alone. In our remarks, NRGI emphasized the need for additional financing and technical support so that producer countries can design, implement and monitor value addition and diversification strategies that truly meet the needs of their people, and enforce high human rights, environmental and governance standards.
Green industrialization could serve as a bridge that brings mineral trade and climate policy closer together. We are looking forward to further progress at COP31 in November, as green industrialization is a key priority on the Action Agenda launched by Türkiye last week. Looking to next year, NRGI is also supporting a shared agenda on equitable mineral partnerships across the COP32 and UK-led G20 processes, where African countries have an opportunity to connect their climate positions with their leverage as producers of critical minerals.
"Critical for who?": equity and the governance gap
With “critical minerals” being used so often, the question "critical for who?" recurred throughout. Across discussions, there was a unifying call for a new and more equitable economic and political paradigm, but how this plays out in practice remains highly uncertain. There were multiple calls (including from NRGI) for critical minerals to underpin just, country-led transitions that serve producer countries' development aspirations, respect the free, prior and informed consent of Indigenous Peoples and frontline communities, and remedy legacy environmental harms. Several sessions went further, asking not just how much revenue extraction generates but whether it preserves national wealth across generations. Without this, producer countries risk exchanging finite mineral wealth for limited revenues while leaving depleted assets and environmental damage to future generations.
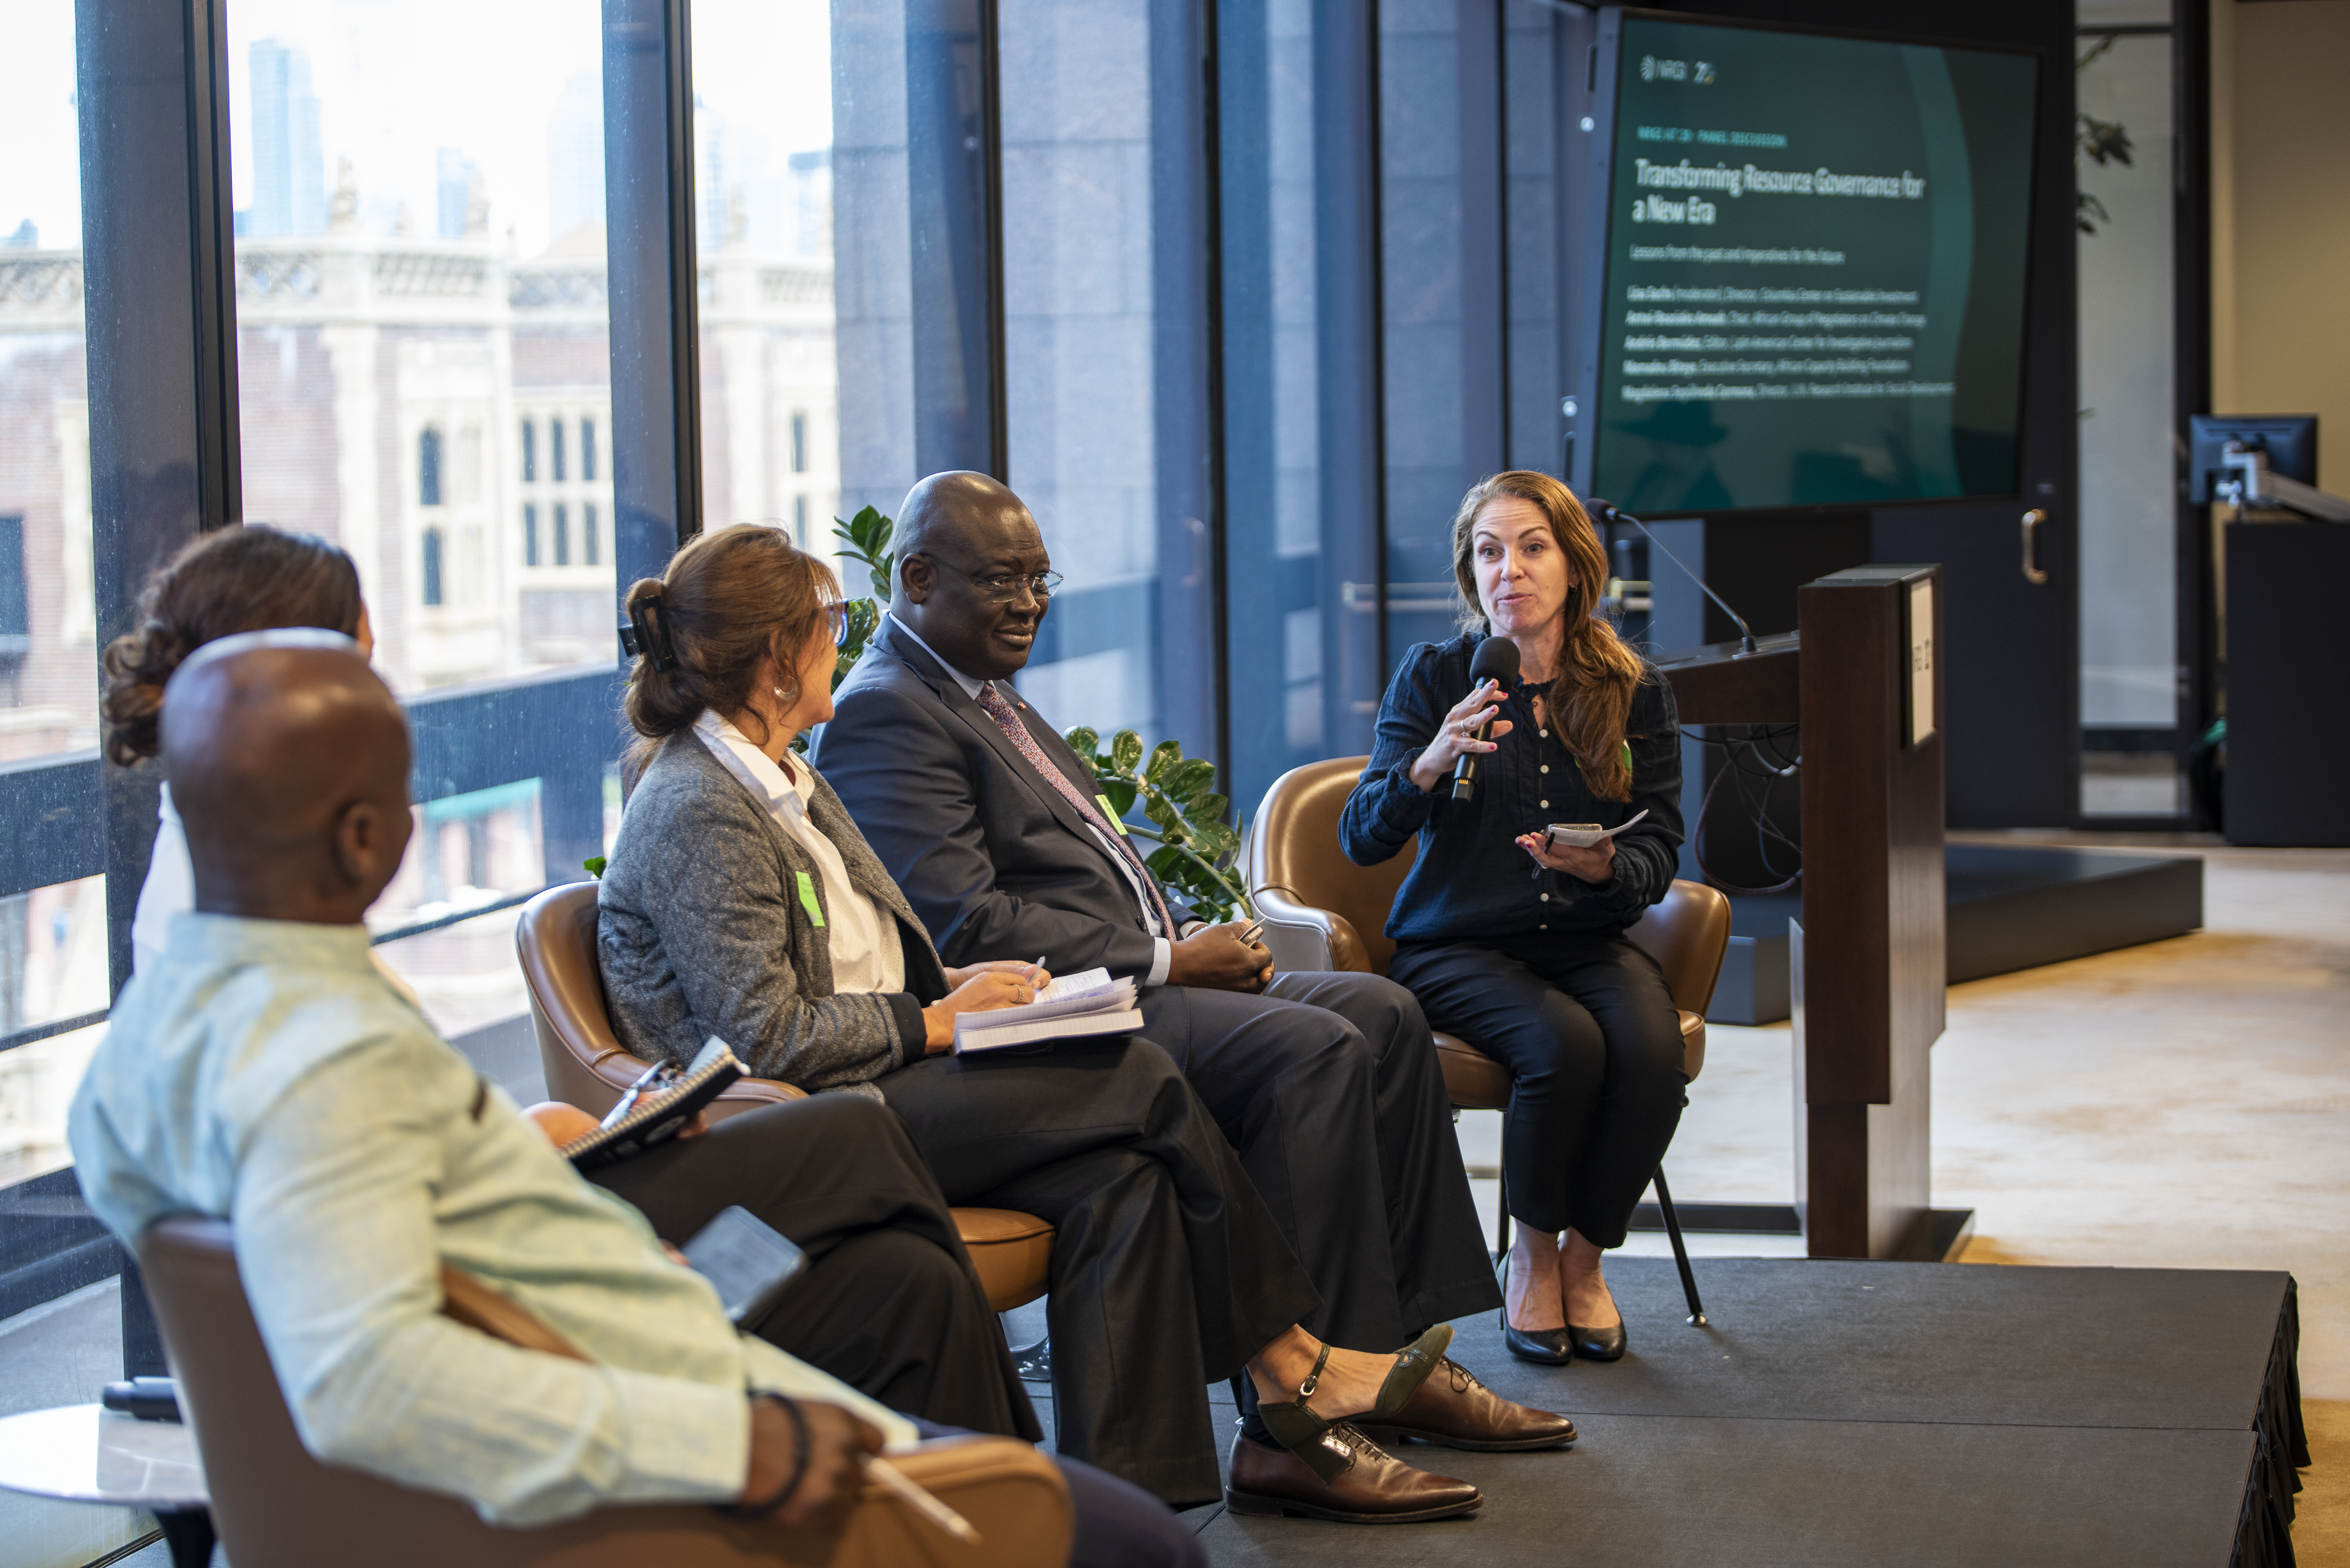
While critical minerals are the focus, the obstacles to fairer and more prosperous societies are structural and systemic – a theme that echoed throughout including in NRGI’s 20th anniversary event. Low- and middle-income countries remain underrepresented in setting new standards and paradigms, despite bearing their costs.
Encouragingly, the discussion has moved from what must change to how. Reformers shared approaches ranging from multi-stakeholder engagement and narrative storytelling to strategic litigation, the quantification of decommissioning liabilities and evidence on the financial materiality of community engagement. Each aims to ensure that community rights are respected and that polluters remediate the harm they cause. A recurring message was that affected communities need agency, not simply better consultation: access to information, the capacity to negotiate and the ability to speak for themselves with governments, companies, investors and financiers. These “unbankable” elements often determine whether supposedly bankable investments succeed.
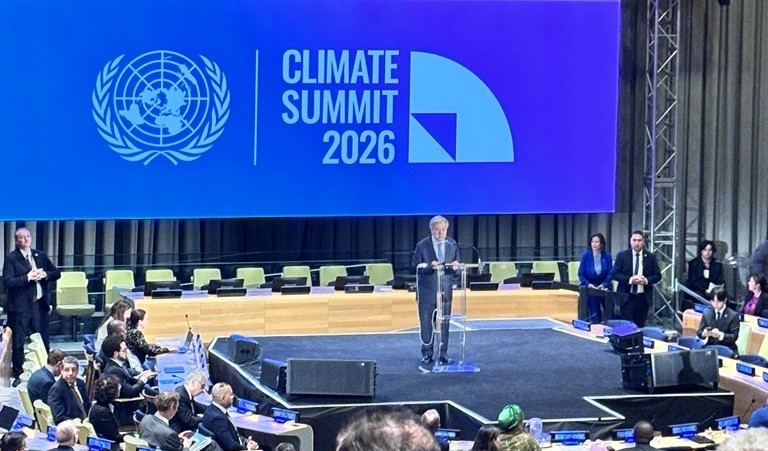
Concrete openings exist to keep making progress. At the UN Climate Summit, the Secretary-General announced a new country support mechanism for six mineral-rich developing countries to implement the recommendations of the UN Secretary-General's Panel on Critical Energy Transition Minerals. Having served on the panel, NRGI and our partners have pressed for this follow-through, including in this joint letter last July. We welcome the mechanism. Connecting with technical assistance partners outside the UN to deliver tailored, demand-led support will be critical to its success. (Learn more: See our video and press statement released during the week). The push for an International Panel on Inequality and next year’s planned SDG Summit offer further entry points to center producer countries in debates on the future economy. The ongoing review of the IFC Performance Standards is another, as these standards shape the practices of commercial banks, export-credit agencies and mining companies well beyond the IFC itself.
Artificial intelligence and the resources beneath it
Some described this as the "AI UNGA". Technology leaders addressed the Security Council, many world leaders mentioned AI in their speeches, and there were countless AI-focused side events. Yet beyond limited discussion focused on data centers, few conversations linked AI development to the minerals that build and power it. This is a gap that policymakers, companies and civil society alike must close.
A notable exception was a discussion convened by the government of the Democratic Republic of the Congo, entitled “AI and the New Geopolitics of Peace and Security”, in which NRGI participated. It followed a July Arria-formula meeting, held during the DRC's Security Council presidency, which called for a global normative framework reconciling peace, security, transparency and sustainable development. NRGI has provided technical input to that process, and this intersection is emerging as a key policy space.
The DRC's leadership is itself both noteworthy and an opportunity. It shows how low- and middle-income countries can shape emerging global norms on minerals, security and AI, rather than simply adopt rules set elsewhere.
A fragmented landscape demands trusted brokers
While emerging coalitions and new opportunities are being born of the current upheaval, fragmentation and polarization remain a challenge. Progress will depend on trusted brokers who can navigate contradictions to unite diverse groups, and on building new, action-focused coalitions.
For NRGI, we see this as a challenge and an opportunity. We will seek to leverage the trust, credibility and knowledge we have built over two decades, while holding a nuanced, independent position in a multi-polar world.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Senegal: Governing Natural Resources at a Pivotal Moment

As Senegal enters a new era as an oil and gas producer, the third National Forum on Extractive Sector Governance offers an opportunity to reflect on the governance choices that will shape how the country's natural resources contribute to long-term development.
On 30 June and 1 July, Senegal's Ministry of Energy and Petroleum, EITI Senegal and NRGI will bring together government, parliament, civil society, affected communities, the private sector and international partners in Dakar for the third National Forum on Extractive Sector Governance. The forum comes at a defining moment in the country's development: Senegal is now an oil and gas producer. At the same time, the country faces the challenge of developing its oil and gas resources while advancing its energy transition and long-term development goals.
Stakeholders from across the sector will meet to discuss the priorities that should shape this next phase. The governance choices made today will determine whether Senegal's natural resources translate into quality public services, stronger fiscal resilience and a just energy transition that supports sustainable and inclusive development. Through its Senegal Vision 2050 agenda, the country aims to turn extractive revenues into sustainable public investment, reduce its vulnerability to commodity price cycles and build accountable institutions that endure beyond political transitions. The forum provides an opportunity to advance that conversation.
Senegal has been producing oil since June 2024 and liquefied natural gas since February 2025. The country's legal framework is now in place, including a hydrocarbons revenue management law, parliamentary oversight mechanisms and stronger transparency requirements. But the context in which those rules must now operate has changed significantly. Public debt, revised to 132 percent of GDP by the Court of Auditors, has reduced the country's fiscal room for maneuver. PETROSEN has taken on a larger operational role in developing the country's gas projects, while the government has launched a process to review oil, gas and mining contracts. At the same time, Senegal must balance the development of its gas resources with expanding renewable energy and meeting its climate commitments.
At a time of fiscal pressure and high public expectations, what distinguishes a new producer is not just the size of its resource base. It is the strength of its governance institutions and their ability to ensure transparent, effective and equitable management of natural resources over the long term. Those are precisely the questions that stakeholders will address in Dakar.
NRGI has worked in resource-rich countries for more than 20 years, including five years of engagement in Senegal. Together with public institutions, EITI Senegal, civil society, affected communities and other partners, NRGI has contributed to several of the reforms and debates that have shaped this period, from strengthening the legal framework for extractive revenues to supporting the establishment of the government's grievance mechanism in the hydrocarbons sector, as well as advancing public debate on methane emissions, supporting affected communities and contributing to the creation of the Platform of Civil Society Actors for a Just Energy Transition (PACTEJ). A more detailed review of these five years of work will be published soon.
An agenda for the next phase
The National Forum is not an endpoint. It is a starting point for the next phase of Senegal’s resource governance, offering a chance not only to take stock of progress and identify remaining gaps, but to set clear priorities and build momentum for the work ahead. Discussions will focus on revenue management, contract transparency, PETROSEN's role, the trade-offs between hydrocarbon development and the energy transition, critical minerals and the participation of communities and local authorities. These are complex questions that will require difficult choices and sustained collaboration across government, civil society, industry and communities.
The discussions in Dakar matter beyond Senegal. Since 2021, the country has shown that a well-designed governance framework can be brought to life through sustained dialogue, capacity development and evidence-based approaches, resulting in tangible gains in transparency and accountability. The next phase will test whether those rules can be put into practice as Senegal seeks to develop its natural resources, protect its communities and build a more sustainable, resilient and inclusive energy future. Ultimately, the country's future will be defined not only by production, but by whether Senegal can turn its natural resources into lasting benefits for its people. The National Forum is an opportunity to help shape that next chapter.
The authors thank Amir Shafaie and Papa Daouda Diene for their contributions.
Senegal National Forum on Extractive Sector Governance
On June 30 and July 1, key extractive sector stakeholders will gather in Dakar to discuss the challenges and priorities shaping natural resource governance in Senegal.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
How Can Governments and Miners Build Partnerships that Deliver Long-term Value? (Mining Indaba)
Sahara Stage (CTICC2 - Level 2), Cape Town International Convention Centre

Minerals offer multi-generational development opportunities for the communities where they are mined. But has the balance of responsibility for delivering that development become too one-sided? If mining companies feel they are carrying an outsized share of the development burden, will they scale back investment or exit certain regions altogether? And if governments push harder for local value addition without the right enabling conditions, could projects become unviable?
This event will take a closer look at how governments and mining companies can rebalance their roles to create partnerships that are commercially viable, socially legitimate and development-oriented. It will examine practical approaches to sharing responsibilities for infrastructure, skills, local content and community development; the policy and regulatory conditions needed to unlock sustainable value addition; and how trust, transparency and long-term planning can help ensure mineral wealth translates into lasting benefits for host countries and communities.
Speakers
- Kirsten Hund, Sustainability Expert, Mining Indaba Ambassador
- Alex Khumalo, Head: Social Performance, Minerals Council South Africa
- Ibrahima Aidara, Deputy Africa Director, NRGI
- Jito Kayumba, Special Assistant to the President, Republic of Zambia
- Werner Duvenhage, Managing Director, Richards Bay Minerals
Featuring NRGI's
Ibrahima Aidara
Deputy Africa Director
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Trust Before Transition: Tunisia’s Lessons on Community Power

Tunisia’s story is specific, but the lesson is universal: energy transitions fail when trust is missing.
Tunisia’s deep south—Tataouine and Kebili—holds a paradox. For decades, they’ve been among the country’s richest in natural resources. Oil wells, gas fields and, now, massive renewable energy projects mark the landscape.
But these are also politically symbolic. Since the 2011 revolution, Tataouine and Kebili have led some of Tunisia’s most sustained social movements. Protesters have repeatedly halted oil and gas production, demanding not only jobs, but dignity, justice and a voice in decisions that shape their future.

From margins to the frontlines of transition
Today, as Tunisia embarks on its energy transition journey, Tataouine and Kebili are again at the forefront, but this time, not just as sites of extraction or protest. They are becoming testing grounds for a new kind of energy future—one rooted in participation, trust and local ownership.

For NRGI, this shift embodies our core mission: supporting energy transitions that center equity, local agency and lasting accountability. When communities move from the margins to decision-making spaces, transitions become not only fairer, but more durable.
The Trust Gap: Why Energy Transitions Can’t Be Top-Down
This isn’t just a Tunisian story. Across the world, transitions risk deepening distrust when driven from the top down. Without trust, energy reforms fail—no matter how ambitious or well-funded.
People have grown tired of promises of “development” that never reach them. They’ve seen plans drawn up without their input, resources extracted without benefits returning, and decisions made behind closed doors.
“If they keep deciding everything from the capital, they’ll never know what our people really need. We must be at the table, not outside the door.” Fatiha Amairi, activist from Tataouine
In Tataouine, after the 2017 El Kamour sit-in, the government promised 80 million TND annually and 4,500 local jobs in oil, environment, and plantation sectors. By 2020, only around 2,500 jobs had materialized, and key funding and hiring provisions stalled—sparking renewed protests, strikes and roadblocks around regional oil infrastructure.
Trust isn't a soft issue. It's the foundation that everything else rests on. Without it, even solar panels and wind farms can symbolize exclusion.
NRGI’s People-First Approach: Strengthening Capacity, Rebuilding Trust
Many projects focus on big goals and short timelines but miss the core that actually holds it all together: trust.
NRGI took a different path in Tunisia—by listening. In Tataouine and Kebili, that meant sitting with communities in familiar spaces: cafés, homes, tents, and not conference rooms. It meant speaking in Arabic, sometimes in local dialects, and taking the time to understand what people really wanted from the energy transition.
Building on that foundation, NRGI has supported civil society partners and local stakeholders to engage more confidently with authorities, better understand project timelines, and advocate for meaningful consultation, ensuring that communities are not only heard but also equipped to shape the decisions that affect them.
What we heard was clear. People weren’t asking for glossy transition plans. They want to know: “Will this create real jobs, or is it just another project on paper?” One local youth leader asked whether renewables would finally bring transparency—or simply repeat the same extractive logic. Farmers shared fears about solar projects taking over their land without consultation. Others spoke of the deep fatigue of being promised development without ever being part of the conversation.
“We don’t need another top-down plan. We need guarantees: jobs, justice, and a seat at the table.” Anouer Belhabib, activist from Kebili
Since 2020, we’ve taken a people-first and process-led approach: no pre-written agendas or imposed timelines. Instead, we co-designed each step with local actors, adapting language, formats and expectations.
At its core, this wasn’t just about participation. It was about restoring dignity to a process where people too often feel spoken about, but rarely spoken to.
The Shift: When Communities Lead
The change in Tataouine and Kebili didn’t happen overnight. It took three years of steady investment in local leadership through mentoring, technical training and ongoing collaboration.
Capacity development efforts were key—not just transferring technical knowledge, but equipping local actors with the tools, confidence and institutional know-how to engage as equals in governance processes. Whether analyzing budgets, navigating legal frameworks or speaking in policy forums, communities needed more than passion—they needed preparation.
When we began, more than 40 civil society organizations (CSOs) across Tataouine and Kebili were still emerging, fragmented and often reactive. Step by step, they grew into informed, coordinated actors who could analyze policies, interpret budgets, negotiate with ministries and speak with confidence in national spaces. Their transformation made them harder to ignore. The consistency of their engagement, combined with the credibility they built in locally, slowly shifted how government actors saw them. In some cases, ministries even reached out first—not out of obligation, but out of recognition.
Our support focused not just on technical skills, but on legitimacy:
- Providing safe, culturally appropriate spaces for women and youth
- Helping activists expand from protest, which remains vital, to constructive advocacy strategies that bring them into policy conversations
- Encouraging formats that communities trusted from tent meetings to café debates
Real change didn’t come from a single event. It grew from patient, persistent investment in local leadership. Today, these CSOs are no longer just calling for a seat at the table. They are proposing reforms, pushing for more equitable energy policies, and hold both local authorities and national energy institutions accountable, not from the margins, but as essential voices in Tunisia’s energy future.

Turning Point: When Dialogue Replaced Confrontation
Tunisia’s shift from protest to partnership is marked by key moments. In 2022, civil society groups sat with the Ministry of Energy to discuss reforming the Hydrocarbon Code—a topic long seen as off-limits. Just a few years earlier, such a meeting would have been marked by tension or simply dismissed altogether. But this time, there was no confrontation. Just dialogue — cautious, quiet, but real.
For the first time, civil society wasn’t outside the room demanding change—they were inside, helping shape it.
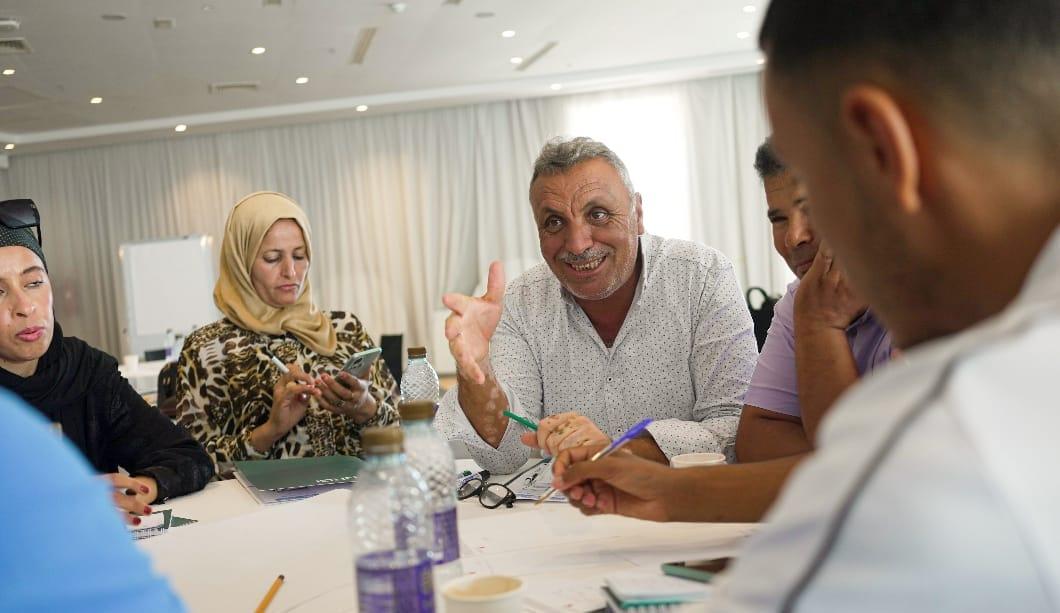
By 2025, that dialogue had deepened. During a national workshop on the energy transition, organized by NRGI, CSOs from Tataouine and Kebili sat across from senior government officials. In a context where such engagement is rare, the event stood out for its openness, mutual respect and what it revealed: civil society had become a credible actor and trust was starting to replace tension.
Beyond Tunisia: Why This Story Matters Everywhere
Tataouine and Kebili might not headline global energy summits. But they reflect a truth that resonates far beyond Tunisia: transitions fail when people are treated as obstacles rather than partners.
All over the world, communities in resource-rich regions are asking to be more than just hosts to infrastructure. They want a voice in how their resources are managed and how benefits are shared.
If we want the energy transition to succeed—and to be just, not just fast—we need more than solar panels and updated policies. We need trust. We need legitimacy. And we need to build both with the people whose lives and lands are most affected.
That’s the real work.
Building trust isn’t just about good intentions. It takes investment—in time, in relationships and in capacity. Around the world, communities most affected by extractive projects or energy reforms are too often under-resourced to engage effectively in decisions. If we want just transitions, we need to fund not just infrastructure, but people—to ensure communities have the knowledge, tools and institutional muscle to co-lead the future of energy.
A Just Transition Starts by Slowing Down and Listening
It’s easy to talk about megawatts, investment flows and net-zero targets. But if we skip people—ignoring their knowledge, their fears, their hopes—we miss the point.
A truly just transition isn’t about who builds what, it’s about who gets to decide.
- For policymakers: Slow down. Make space. Legitimacy isn’t a given—it’s earned.
- For donors: Fund the process, not just the outcome. Trust-building takes time.
- For civil society: Keep centering the voices that have been pushed to the margins. That’s where real leadership is growing.
Tataouine and Kebili remind us: when communities move from the sidelines into real decision-making roles, transitions gain not just momentum but meaning.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Six Keys to Unlocking Equitable Value Addition in Mining

Key messages
- Governments and civil society actors in low- and middle-income mineral-producing countries are calling for more domestic value addition to boost exports, create jobs and provide inputs for their economies. Governments of consumer countries and multistakeholder initiatives are also acknowledging the inequity in global mineral value chains caused by the limited value addition in producing countries.
- The keys to translating this recent focus into viable value addition projects that meaningfully benefit people in producing countries are:
- Governments should clearly define their strategic objectives, which should be specific to individual minerals and stages of the value chain, and based on national development plans, economic feasibility, market outlook and rigorous cost-benefit analysis.
- Governments should place the principle of doing no harm at the core of their value addition strategies, with moving along the value chain not coming at the expense of environmental and social wellbeing.
- Governments should tailor fiscal, industrial and trade policy mechanisms to their value addition strategies, with a consistent focus on equitable distribution of benefits.
- Governments and companies should address the corruption risks associated with value addition, including those related to policy capture, licensing and permitting, financial incentives, infrastructure development and socio-environmental harms.
- Development partners and consumer country governments should provide financial and technical assistance, while ensuring that this assistance is not undermined by other support that inequitably benefits their own industries.
- Governments should ensure a transparent approach involving citizens at every step. Accountability actors should evaluate the plans of government and companies.
Introduction
Governments and civil society actors in low- and middle-income mineral-producing countries are calling for more domestic value addition of their minerals to increase export revenues, generate jobs and support development of other sectors.
Historically, minerals have typically been extracted and exported with little processing from low- and middle-income countries (except for China). This imbalance has limited the benefits that the mining sector has generated for people in producer countries.
Producer countries have therefore long prioritized moving along the value chain to undertake mineral processing and the manufacturing of semi-finished and finished products. Many countries increased value addition ambitions in the past couple of decades. Expectation of a transition mineral boom has further reinforced this trend. In a 2023 survey by the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development, more governments named value addition as the key driver for their critical mineral strategy than any other factor.
Value addition also occupies an important place in the broader rhetoric around mining in the context of energy transition. For example, the United States-initiated Mineral Security Partnership (MSP)—a collaboration of primarily consumer countries aiming to catalyze public and private investment in supply chains and reduce their dependence on China—has committed to support only projects that promote local value addition. Multistakeholder initiatives, such as the United Nations Secretary-General’s Panel on Critical Energy Transition Minerals (“UNSG CETM panel”), have also identified the importance of low- and middle-income countries moving along the value chain for economic equity. The World Bank has launched the Resilient and Inclusive Supply-Chain Enhancement (RISE) Partnership, with initial funding from Japan, to support low- and middle-countries in this area.
This international recognition is likely a result of various factors. These factors include geopolitical competition, with consumer countries and companies competing for access to minerals by offering more benefits to producer countries; a growing realization that value addition is important for the social license to operate and that this social license is critical for ensuring secure, undisrupted supply; and a genuine recognition that “this time must be different” and the inequities that have historically characterized the mining sector cannot be repeated.
This heightened focus is welcome and overdue, and can help push things forward. However, it can also create unrealistic “hype”, increasing the likelihood of value addition being pursued for political rather than socioeconomic gains, and leading to unsuccessful or counter-productive policy making. Translating this focus into value addition projects that provide meaningful benefits to people in producer countries will require clearer strategy, reforms of policies and practices by a range of actors, and changes in public awareness.
As part of our broader work on minerals governance, NRGI is committed to supporting low- and middle-income countries to maximize economic benefits, including through equitable value addition. We continue to research and develop ideas in this area, which will enable us to contribute to initiatives such as the UNSG CETM panel actionable recommendation 1 on benefit sharing, value addition and economic diversification.
Below are six keys to unlock equitable value addition, building on work we and others have done in this area. We hope such a framework can help stakeholders, including governments and civil society in low- and middle-income producer countries, to soberly assess value addition plans and rhetoric and set parameters for taking forward value addition ambitions.
1. Define a clear strategy based on the national development plan, economic feasibility, market outlook and rigorous cost-benefit analysis
The term “value addition” is used inconsistently. Governments, among others, use the term to describe a variety of goals and processes, for which the feasibility and benefits differ considerably between countries and value chains. Yet, it is not uncommon for strategy and policy documents to reference value addition ambitions in vague terms that take a blanket approach to a country’s mining sector. (Skeptics who reflexively write off the chances of an increase in mineral value addition in low and middle-income countries often similarly lack nuance.)
Governments should evaluate whether value addition is the most effective strategy to reach national development goals. To do this, they should clearly define their strategic objectives. These objectives should be specific to individual minerals and stages of the value chain, and based on economic feasibility, market outlook and rigorous cost-benefit analysis. This clarity is critical for informing government decision-making on the amount of political capital, time and money to spend, trade-offs to accept, and risks to take in attempting to progressively move along the value chain—and which value chains, and parts of these chains, to pursue.
Articulate goals
Governments often target value addition in pursuit of one or more goals. They aim to create jobs; strengthen the public finances through higher government revenues, more foreign exchange and less exposure to commodity market volatility; support development of other sectors (including for diversification purposes) through cheaper inputs, and the transfer of knowledge and skills; improve infrastructure; or support social development in the locality of mining and value addition operations. Governments may also have geopolitical motivations, such as reducing their dependence on other countries or increasing their ability to influence others.
The likelihood of achieving these goals depends on a range of factors which are usually specific to the mineral and the stage of the value chain that is targeted. For example, in the nickel value chain the nickel ore price makes up only 40 percent of the price of mixed hydroxide precipitate (one of the possible next stages in the nickel value chain).1 So for a country such as Indonesia, nickel processing is conducive for achieving a goal of greater government revenue since doing so can add 60 percent of value to the product being taxed in-country. However, this is not the same for all minerals. For example, Indonesian plans to move along the copper value chain and process more copper concentrate into copper cathodes will not yield the same government revenue outcome given that processing copper into cathodes tends to only add 4-6 percent of value.
Similarly, how far along the value chain a country can move will impact whether some goals, such as stimulating the development of other sectors, are likely to be achieved. For example, the Democratic Republic of the Congo (DRC) increasing copper refining may not, on its own, be a significant catalyst for the development of other sectors given that the know-how utilized in refining has limited transferability to other potential economic activity. However, if the country can go further along the value chain and start large-scale manufacturing of products such as copper wires and rods, it would not only result in inputs for other sectors but also the development of know-how that could enable entry into other forms of manufacturing.
Moving several stages along a value chain takes time. China has taken several decades to progress along the value chains it dominates today. Governments may accept limited payoffs from initial measures if these develop capabilities that enable subsequent moves with greater payoffs. However, to ensure optimal decision-making, governments must clearly define this long-term vision from the start.
Clear goals are therefore critical to inform assessment of whether and how the envisaged value addition can achieve them, and how that achievement would support the national development plan.
Assess feasibility
Governments must base their value addition strategy on a clear-eyed view of their country’s current and longer-term potential comparative advantage in a given value chain, and the feasibility of moving along it if this advantage does not exist. Whether a country has a comparative advantage will determine its ability to attract investment. If the government decides to invest public resources or provide incentives, it will determine the ability of new activity to be competitive and therefore sustainable without sustained government support. For example, in the absence of clear competitive advantage, most of the gold refineries constructed in Ghana are lying largely idle due to a combination of profitability constraints. In Australia, the government has had to provide subsidies for several decades to keep the country’s aluminum smelters operating.
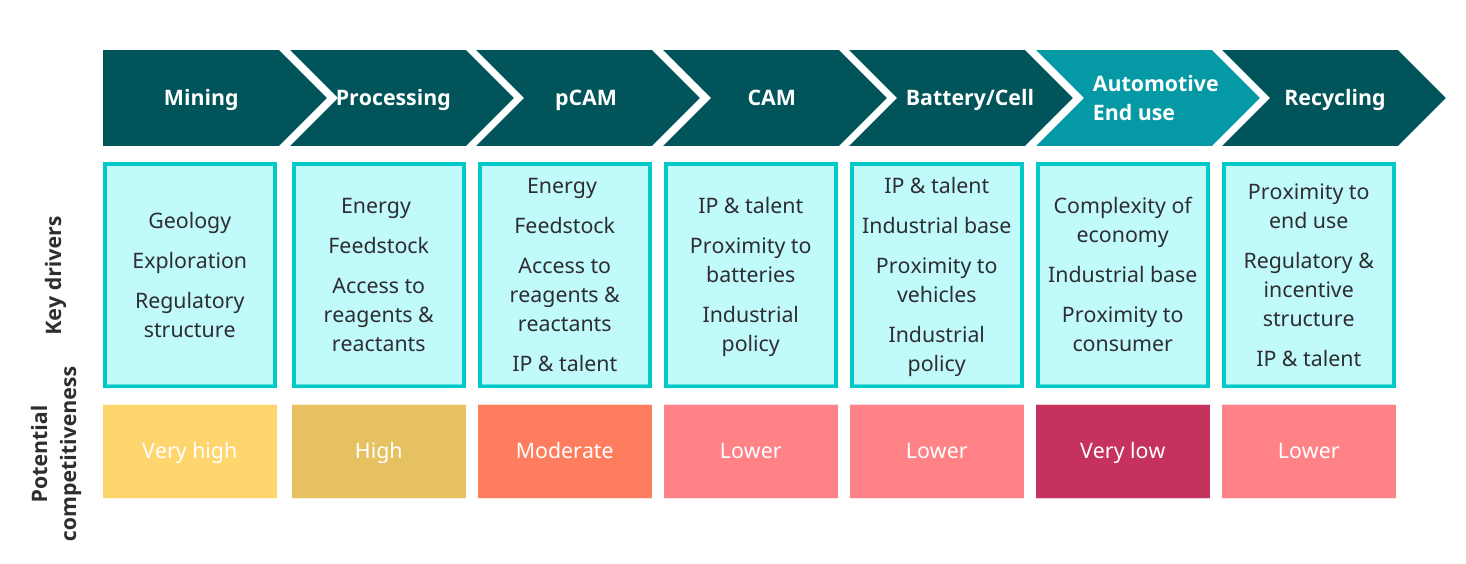
The economics of processing certain minerals make it likely that some value addition will occur at or near the mine site even without a significant government push to do so.2 However, as many countries have already experienced, proximity to mineral deposits plays only a small role in determining the location of stages in value chains. A country’s competitiveness further along a value chain depends on multiple factors. These factors, and their importance, depend on the mineral, value chain and stage of the value chain. For example, Figure 1 sets out some of the drivers that determine competitiveness at different stages of the automotive battery value chain.
Figure 1. Comparative advantage drivers and potential competitiveness of low- and middle-income producer countries across the automotive battery value chain
Source: Wood Mackenzie
Typical value addition success factors
In general, the most important success factors for mineral processing are:
Size of mineral supply. Scale is a critical determinant of a processing facility’s economic viability. The size of mineral supply also affects a country’s bargaining power. The differing size and market share of Indonesia’s nickel and bauxite reserves are the main reasons why its bans on unprocessed exports of these minerals—first imposed in 2014—have had different impacts. Companies have constructed 42 nickel smelters in Indonesia since 2014. The country is the world’s largest nickel ore producer, has the largest reserves, and has high-quality nickel. This meant that smelters in China would struggle to find an alternative to Indonesia’s nickel in both the short and long term, and therefore had to acquiesce to the Indonesian government’s insistence that China construct smelters in Indonesia instead. In the bauxite sector, however, Indonesia lacked similar leverage, and the main impact of the 2014 ban was a reduction in bauxite production. Indonesia was the world’s second-largest bauxite producer on the eve of the ban but its reserves are only the sixth largest (according to the U.S. Geological Survey). These smaller reserves made the profitability of alumina refining uncertain, and it was easier for China and other bauxite importers to source bauxite from other suppliers. The government lifted the bauxite ban in 2017, then reimposed it on bauxite ore exports in 2023, but is reportedly considering easing it again.
Transport costs. Processing can significantly reduce the weight of the minerals that are transported. The further away the customers, the greater the saving in costs from processing before export. For example, Zambia’s copper belt is 11,000 kilometers from China’s industrial zones. It therefore makes economic sense for companies to smelt their copper in Zambia even if smelters in China are more efficient, to save on transporting the heavier unrefined ore and concentrate. A large proportion of Zambia’s copper is smelted domestically as a result.
Availability of competitively priced, reliable, clean energy. Mineral processing tends to consume large amounts of energy. Producing countries with expensive, limited or unstable energy supply therefore face a significant obstacle to moving along the value chain. Some processing is particularly energy intensive: for example, energy accounts for around 40 percent of aluminum production costs. When energy prices rose in 2021-22, 50 percent of the European Union’s aluminum production capacity was forced offline. How clean the energy is also increasingly matters. For example, manufacturers of batteries using Indonesian nickel, and manufacturers of the electric vehicles using those batteries, may find it difficult to access the European market once the EU implements its battery passport in 2027. This mechanism—which will require companies operating in the European market to report on carbon footprint among other information—will likely penalize the high emissions from Indonesia’s nickel smelters’ use of coal.
Competing capacity elsewhere. The availability and cost of processing capacity elsewhere affects how important the above success factors are for a country’s prospects. For example, Guinea’s alumina refining ambitions, and Chile’s plans to construct new copper smelters, are complicated by excess capacity in China. The source of this competition is increasingly dynamic. Governments in many countries, such as the U.S., EU member states and Gulf states, are increasingly supporting to their domestic mineral processing industries to compete with China (and each other). This could further alter the economics of value addition prospects in low- and middle-income producer countries (see Key 5).
Good governance. Most value addition projects have large upfront construction costs and take a long time to make a profit. Predictable and transparent policymaking—in relation to both the broader mining sector (to reduce the risk of mineral supply disruptions) and for individual value addition projects—is therefore critical for investor confidence. As discussed in keys 2 and 4, investors are increasingly considering broader environmental, social and governance issues in their decision-making.
Additional success factors are relevant to value addition further along the value chain. In particular:
Proximity to downstream markets. As products get more complex, manufacturers tend to benefit from being close to their markets so they can capitalize on quicker, more flexible delivery to customers. Proximity can also help manufacturers to avoid difficulties in transporting specific products. For example, battery cathodes are chemically unstable. Cathode production therefore tends to be located close to battery manufacturing, as shown in Figure 1. Battery manufacturers benefit from being close to electric vehicle (EV) manufacturers, who in turn benefit from being close to large EV markets. This has implications for Congolese and Zambian plans to develop a nickel-manganese-cobalt (NMC) battery value chain. The African market for the types of cars that use NMC batteries is likely to remain small. As a result, despite the region’s large nickel, manganese and cobalt reserves, it will likely only be able to produce NMC battery precursors and then export them. Lithium-iron-phosphate (LFP) batteries, on the other hand, are used in the electric two- and three- wheelers and stationary power storage increasingly in demand across Africa. This value chain could therefore be both more beneficial for the region and more viable.
Existence of an industrial base. An existing industrial base helps to reduce the costs and risks of more complex processes. It enables investors to leverage existing infrastructure, a pool of companies and workers with similar know-how, local supply of inputs and a proven business environment for industrial activity. Partly because of these agglomeration effects, Wood Mackenzie predicts that battery production will largely coalesce in high- and middle-income economies in Asia, North America and Europe.
A country may have these success factors in place for some minerals but not others, and for some stages of the value chain and not others. As discussed in Key 3, governments can use a range of policies to fill gaps. However, they face limits in what policies can achieve, with several factors outside of governments’ control. If few of these success factors are in place, government incentives or penalties may be insufficient to encourage value addition, and may carry considerable costs. Governments should therefore ensure their strategies account for feasibility, and target value addition that leverages their comparative advantages. Governments with strategies centered on developing capabilities that provide new comparative advantages in the longer term, such as an industrial base, must be clear on the required steps and realistic about the prospects for—and costs of—taking them.
Countries’ own sector-level feasibility assessments should be informed by rigorous, independent project-level feasibility studies as part of the mine licensing process.3 Project-level feasibility studies can help governments, and other actors such as development partners, to identify missing success factors and the actions necessary to address them, and to manage expectations if filling these gaps appears insurmountable. Governments increasingly require license applicants to conduct some form of scoping of value addition feasibility. For example, the Ghanaian government has required a scoping study for a possible refinery in the license conditions for the country’s first lithium mine. However, these assessments are often ill-defined, lack clear timeframes and are rarely publicly disclosed. Producer country governments and citizens may also have limited trust in them given the companies involved in the project typically procure and pay the contractor conducting the assessment. Governments should therefore consider delinking procurement and payment for feasibility studies from the companies involved.4
Analyze the market outlook
Governments must account for the market outlook in their strategies. Value chains are dynamic. Changes in technology can result in large shifts in demand for products and therefore affect the benefit of attempts to move along value chains.
Some minerals and value chains are more exposed to technology risk than others. For example, long-term demand for copper and steel is likely to remain robust given their role in both the energy transition and wider global economy. Battery value chains, on the other hand, face significant uncertainty. NMC batteries have dominated markets until now, but market share for NMC batteries is shrinking. As Figure 2 shows, the International Energy Agency (IEA), among others, expects LFP batteries to become the dominant battery chemistry within the next decade, before ceding market share to lithium-free sodium-ion batteries. However, given the amount of ongoing research on battery chemistries—to improve performance, reduce costs and strengthen geopolitical positions—the future could also differ considerably from such predictions.
Figure 2. International Energy Agency’s projected market shares of electric vehicle battery chemistries
Governments of dominant mineral-producing countries, such as the DRC (for cobalt) and Indonesia (nickel), can influence the market trajectory to some extent. For example, battery manufactures are shifting away from using cobalt partly because of persistent concerns over DRC’s license security, taxation, corruption, and the welfare of artisanal miners. By improving governance, the DRC government could slow this shift. However, it is unlikely that any one producing country could fundamentally change the long-term outlook for a commodity for which demand is ebbing due to technological innovation.
Governments should therefore be cautious about pursuing value chains that are highly exposed to technology risk. This is particularly the case for projects that are still many years from being developed and therefore likely to miss any existing window of opportunity.
Analyze trade-offs and costs, not just benefits
Governments should base value addition strategies on rigorous cost-benefit analysis. This is particularly important given that many governments are not only pursuing value addition for socioeconomic gains, but also political ones: demonstrating the authorities’ capacities to “prioritize” national interests and actors, over international and corporate ones.
Even if a government realizes socioeconomic benefits from value addition, these benefits may not always outweigh the direct and indirect costs of the plan. These costs include environmental and social harm after the implementation of any anticipated avoidance and mitigation measures (see Key 2). For example, incorporation of the environmental and social impacts in an economic model used by one study of Indonesia’s nickel smelting operations found that continued smelting growth in three regions would have a positive economic impact in the first few years. However, the study found within ten years, the industry’s impact on the environment and public health would begin to negatively affect the regions’ overall economic output, including through reduced agricultural and fishing output.
Value addition can also have opportunity costs such as the diversion of public funds or electricity away from other productive or social needs. For example, Ghana’s aluminum value chain ambitions would require almost all the country’s hydropower capacity, which, without other new competitively priced electricity capacity coming online, would likely increase electricity costs for other businesses and households.
Governments must also consider the potential trade-offs between value addition and other ways that citizens can benefit from their mineral wealth. For example, if a government achieves value addition through instruments such as export bans, discounted mineral prices or downstream subsidies, it might create jobs, but in some cases weaken the public finances and therefore reduce spending on other development priorities. Similarly, governments must consider how the political capital, time and money spent on pursuing value addition, and the impact on the economics of mining operations, affect the potential to develop local suppliers of products and services to these mining operations. The procurement of goods and services usually amounts to 50 to 70 percent of all money spent by mining companies in producing countries. Local procurement by mine operators is therefore also a considerable opportunity for countries to increase government revenue, create jobs and develop new sectors.
A government’s cost-benefit analysis of value addition plans must also account for the distribution of costs and benefits across the population. It must ensure there is not only a net benefit nationally but also that benefits are equitably distributed across regions and for low- and middle-income as well as marginalized groups, including women, children, youth and communities living near value addition sites. The costs and benefits of value addition will not automatically accrue equitably within a country or even in the producing region within the country. For example, while Indonesia’s nickel activity has increased government revenue nationally and economic growth within the nickel-producing regions, poverty in those regions has increased, counter to the national trend.
2. Do no harm
The principle of doing no harm must be at the core of any government value addition strategy. Value addition, like mining, can cause significant environmental and social harms. It can lead to large swathes of forest being destroyed, create significant amounts of toxic waste, cause local air pollution as well as contribute to global carbon emissions, cause water stress and contaminate waterways and soil. The resulting impact on the health, livelihoods and general wellbeing of communities living near value addition facilities has been documented in countries including Brazil, China, Indonesia, Namibia and South Africa. The Chilean government closed two copper smelters in 2023-24 partly because of their impact on the environment and public health.
Governments should prohibit mining and value addition in areas of particularly high environmental and social sensitivity. Laws often provide governments with the authority to declare “no-go zones.” However, governments rarely utilize such provisions, and when they do, they sometimes fail to robustly enforce them or use them to cover all areas of environmental and social sensitivity. Company commitments, such as that by International Council of Mining and Metals (ICMM) members to not explore or mine in UNESCO world heritage sites, are also insufficient.5 They fall short, for example, of protecting forests of high conservation value inside and outside of protected areas. Mining concessions currently overlap with nearly 27 percent of the Congo Basin’s and more than 33 percent of the Amazon Basin’s intact tropical rainforests—areas that are critical for both resident communities and the planet.
To create the incentive for governments to establish and enforce no-go zones, development partners and other climate finance providers should offer conservation financing. Governments often undervalue the environment due to pressure to prioritize short-term revenue and jobs. This risk is potentially even greater for value addition projects. Public support for value addition ambitions means that governments are increasingly under pressure to deliver value addition at all costs. Conservation financing—building on lessons from projects such as the Central African Forestry Initiative through which the U.S., South Korean and several European governments provide financing to Gabon to maintain its forests—could change this calculus.
Governments should also not proceed with value addition activities when Indigenous peoples and local communities have not been meaningfully involved in decision making, or the right to free, prior and informed consent (FPIC) has not been respected.
For value addition projects outside of no-go zones and that have received the necessary consent, governments must account for potential environmental and social costs when granting permits to operators. Governments will have to overcome common technical and political economy challenges in incorporating these costs in permitting processes, however. They should implement existing guidance on good practice, such as that from the International Finance Corporation. Similar to value addition feasibility studies, to reduce the risk of corporate influence on the outcome of environmental and social impact assessments, governments should consider delinking procurement and payment for assessments from the companies involved in the project. Governments must also manage internal power dynamics to ensure effective cooperation between the authorities responsible for assessing projects’ environmental risks and their economic viability and benefits.
Governments also need to prevent risks from materializing once a value addition project proceeds. In doing so, governments should involve communities in environmental monitoring. Community involvement often leads to better and more cost-effective outcomes. Countries such as Argentina, Bolivia and Peru have introduced participatory environmental monitoring committees—though such practices can only achieve so much without addressing the growing government and corporate hostility toward, and violence against, environmental defenders and community leaders.
Addressing environmental and social impacts is critical first and foremost for reducing harm to the people in mining countries. However, it is also increasingly important for attracting investment and therefore achieving government value chain ambitions. For example, auto maker Mercedes-Benz will now only work with suppliers who purchase minerals from mines audited by the Initiative for Responsible Mining Assurance (IRMA) and who comply with OECD due diligence guidelines.
3. Design policy mechanisms tailored to the value addition strategy and consistently focused on equitable distribution of benefits
Governments can use a range of instruments—including fiscal, industrial and trade policy—in pursuit of value addition. Governments should select their policy approach based on the goals, economic feasibility assessment, market outlook and cost-benefit analysis set out in the value addition strategy, as well as their capacity and geopolitical leverage. Given the impact of the policy approach on the costs and benefits of value addition, governments should ensure a feedback loop between the strategy and policy approach and recalibrate as necessary.
Typical value addition policy approaches
Most policy instruments can be broadly categorized as restrictions and penalties, incentives or enablers.
Restrictions and penalties. Some governments impose a domestic supply obligation on mining companies to ensure that a portion of their minerals are processed domestically. China used a quota system to help develop its rare earth value chain. Chile’s lithium mining companies are required to sell a portion of their production at preferential prices to domestic value addition facilities. Several governments, including Tanzania, restrict licenses to companies that commit to value addition. Other governments prohibit the export of some or all unprocessed minerals. Indonesia has banned the export of nickel and bauxite ore, as noted in Key 1, and is planning to reimpose a copper concentrate export ban at the end of 2024. Other countries such as Namibia and Zimbabwe have also instituted various forms of export bans. Some governments do not restrict the volume of unprocessed exports and charge higher taxes on them instead. China does not refund value-added tax on rare earth exports but provides refunds for rare earth magnet exports. Mongolia charges higher royalty rates on ore and concentrate exports than refined copper exports.6
Incentives. Governments often offer tax incentives to reduce value addition costs and/or make value addition more attractive to investors. Indonesia offers a corporate tax holiday, import duty and VAT exemptions and lower local government taxes to value addition projects. Western Australia limits the royalty amount due on lithium hydroxide and carbonate to that payable on the lower value concentrate feedstock. Several governments subsidize inputs, such as South Africa’s electricity subsidies to its aluminum smelters and other processing plants. Another incentive is discounted mineral prices. This discount could result from government requiring mining companies to offer lower prices, such as in Chile, or government direct or indirect subsidization of the price. Some governments provide direct financial support in the form of equity stakes, grants, concessional loans and sovereign guarantees. The U.S. recently announced a $2.3 billion low-interest loan to support construction of a domestic lithium carbonate refinery. As discussed in Key 5, governments can also sign agreements with other countries that provide a source of incentives in addition to any that they offer themselves. Morocco’s free trade agreement with the U.S. unlocks access to the Inflation Reduction Act’s tax credits for minerals processed in Morocco.
Enablers. The EU intends to streamline permitting processes for “strategic projects” selected under its Critical Raw Materials Act to increase the attractiveness of such projects to investors. Several governments are investing in infrastructure improvements, either unilaterally or in collaboration with industry, to reduce operating costs within a value chain. For example, Canada’s Critical Mineral Strategy sets out investment in energy and transport infrastructure. Some governments actively coordinate the development of industrial clusters—through infrastructure provision, tax incentives and regulation—to generate agglomeration benefits for companies. Much of Indonesia’s processing takes place in industrial parks, while DRC and Zambia are planning to establish special economic zones to support their battery value chain ambitions. Some governments, such as Australia’s, are funding training programs and apprenticeships, while others have reduced restrictions on foreign workers to fill skills gaps.
Another key enabler can be regional coordination when it helps governments to overcome individual country constraints. For example, combining feedstock volumes from several countries can help achieve economies of scale. DRC and Zambia's planned battery precursor project requires coordination between the two countries, and minerals and other inputs from others. However, regional coordination must navigate a range of economic and political dynamics, and grapple with the inherent tension between cooperation and competition among participating countries.
Different policies will be optimal for different countries and value chains. As noted in Key 1, if feasibility constraints are considerable, most policies are likely to be insufficient to encourage value addition and may have significant costs. In this context, the main impact of penalties risks companies reducing their mining activity. Feasibility challenges also increase the risk that incentives, such as subsidies or direct financial support, not only divert government resources away from other development objectives but are used to benefit specific individuals or companies without meaningfully increasing value addition (see Key 4).
Governments should also base their policy approach on their value addition goals. For example, if a government’s main goal is to generate more revenue, authorities must use tax incentives carefully to ensure they do not eliminate most of the potential revenue from a value addition project.7 They must also calibrate instruments such as export bans, downstream subsidies and discounted mineral prices to avoid reducing overall government revenue from the sector. If the government is aiming for “shared-use” infrastructure—for example, a railway that transports both minerals and other cargo or paying passengers—then officials may need to primarily use incentives to mitigate the higher costs (provided these incentives do not outweigh the overall benefits).8
Governments should also account for their financial, technical and regulatory capacity, as well as geopolitical leverage, in their policy approach. For example, fast-track permitting raises the risk that a government might make mistakes or miss environmental, social or corruption red flags. However, this risk is higher for countries with lower regulatory capacity. Governments with scarce financial resources should be particularly cautious about pursuing value chains that are highly exposed to technology risk given the considerable opportunity costs. Governments should also weigh the risk of trade disputes, and their ability to challenge or withstand them when choosing a policy approach: for example, in choosing between imposing an export ban or quotas, which can be challenged under World Trade Organization rules, or export taxes, which tend not to be.
Finally, governments must integrate the distinct experiences, needs and contributions of different marginalized groups into their policies. Ensuring that these groups are unharmed by value addition is critical but insufficient. Governments must also ensure that such groups receive a more equitable share of the benefits than has often been the case in the mining sector. For example, shared power generation capacity should benefit local communities as well as supply the national grid; government skills development policies should be designed specifically to reach women and facilitate their participation in the value chain.9
Irrespective of which policy approach a government takes, the approach should be clear and applied in a consistent and transparent way. Failure to do so could undermine any positive impact that government policy would have otherwise had.
4. Address corruption risks
Value addition policies are always, on paper, officially designed to benefit the citizens in producer countries. However, by creating economic opportunities and incentives, these policies are exposed to corruption risks. The extractive sector is particularly prone to corruption.In the context of a transition minerals rush—characterized by geopolitical competition and ambitious value addition agendas—various corruption risks are likely to increase further.
Tackling corruption will be essential for designing fundable value addition projects that provide a net benefit for people in producer countries. While NRGI is working on these issues and will soon publish detailed analysis, we have already identified—building on previous work—some of the main risks that governments must address.10
Policy capture. Like all policies, value addition policies can be influenced by private interests seeking to shape their design for personal gain, often at the expense of the country’s wider population (though these interests can sometimes align). For example, actors who have the capital, knowledge and connections to develop domestic processing—and to be the first movers to do so—will have a strong incentive to push or support an export ban. The risk of policy capture has been documented across many policy areas: from environmental regulation in the Chilean lithium sector and cost assessment rules in the Indonesian nickel sector to local content rules in several countries including the US.
Licensing and permitting. The licensing and permitting phases have some of the highest corruption risks. Examples abound of corruption in mining licensing and permitting, from Portugal to Namibia. The risks appear to be similar for licensing and permitting of processing facilities. For example, Indonesia’s nickel smelter permitting process has been accused of a mix of favoritism, nepotism and bribery. Questions have been raised about the beneficial ownership of a Ghanaian gold refinery that has been granted an advantageous permit to refine gold purchased by the Bank of Ghana. Similar corruption cases have been documented in the awarding of government contracts for goods and services.
Financial incentives. Value addition policies often rely on financial incentives, as described in Key 3, which can increase corruption risks. The design, negotiation and granting of tax breaks, subsidies, grants or loans are all decision points where government officials can favor certain companies or actors: companies to which they are connected in different ways (e.g., companies they own or those owned by relatives or allies). These are also moments where companies’ representatives might try to bribe decision-makers for unfair access to these incentives. Such incentives can have unintended consequences, particularly if accessed through corrupt means. For example, if the same or related companies own both a mine and the refinery it supplies, a lower tax level for the refinery could lead to transfer pricing abuse. If not monitored carefully, discounted mineral prices could provide owners of value addition facilities with a cheap source of minerals that they then export with minimal further processing.
Infrastructure. Many low- and middle-income countries will likely require a considerable amount of new infrastructure to move along the value chain, with governments overseeing and sometimes providing direct support to its construction. Construction is one of the sectors most prone to corruption across the world. Infrastructure projects are often large, complex and involve many different actors. Corruption risks arise from undue influence in project selection to favoritism in the award of contracts. For example, corruption has been one of the reasons why the Sicomines “resources for infrastructure” deal in the DRC has resulted in delayed, low-quality infrastructure.
Socio-environmental harm. Corruption is one of the worst aggravating factors that can enable the socio-environmental harm described in Key 2. It can undermine the integrity of environmental and social impact assessments, manipulate community consultations and FPIC, and distort land access negotiations. Corruption can also enable companies to conceal socio-environmental damage or operate with unsafe and unfair conditions for workers, as seen in the rare earth mines of Myanmar.
Industry players, such as automakers, entering new parts of the value chain due to the rush for transition minerals could heighten these corruption risks.11 Such companies likely have less experience and knowledge of mining sector practices and challenges, particularly in the geographies where mineral reserves are located, making them more vulnerable to sector-specific corruption risks.
Failure to address the above risks would not only reduce the benefits from value addition in the short term but would likely deter investment in both mining and value addition projects in the long term. Some of these risks are broader than mineral governance; for example, the challenge of policy capture interacts with a country’s political system. Nevertheless, governments can mitigate many of these risks by having a clearly defined, evidence-based value addition strategy to inform policy approaches (see Key 1) and by equipping their value addition policies and projects with strong integrity safeguards. Based on NRGI’s experience, these safeguards include measures to: enhance transparency; increase consultation and participation in decision-making; strengthen oversight actors; reform regulatory processes; improve rule enforcement; and address foreign enablers.
5. Acquire any additional finance and support needed to make projects viable and beneficial
Governments of low- and middle-income producer countries must do the legwork to pave the way for fundable, beneficial projects. However, development partners and consumer country governments have a critical role in enabling more value addition in low- and middle-income producer countries and ensuring it provides a net benefit for their people.
Development partners and consumer country governments should increase funding and technical support to authorities in these countries. Many low- and middle-income country governments do not currently have sufficient resources or information to develop, implement and monitor detailed value addition strategies and policies. These constraints also hinder their capacity to conduct rigorous cost-benefit analyses of potential projects and effectively regulate their operation.
Based on their value addition strategies, low- and middle-income producer country governments should coordinate with companies and development partners to identify where concessional financing to governments can also realistically help address feasibility constraints, including by crowding in more private investment. Support could target value addition facilities directly or address bottlenecks in areas such as local skills and transport and energy infrastructure. Infrastructure support can be particularly impactful when designed to maximize spillover benefits. By reducing the cost of shared-use infrastructure for companies involved in value addition projects, development support can also help governments avoid offering tax breaks and other concessions in exchange (see Key 3). Development partners and consumer country governments should consider how to configure this range of financial and technical assistance to overcome political economy challenges and incentivize high environmental, social and governance standards in producer countries.
Consumer country governments have mooted this type of support—through the MSP and other state-state partnerships—as they attempt to secure the minerals of low- and middle-income producer countries. However, whether they will “put their money where their mouth is” remains to be seen. The MSP’s recently announced support for a nickel project in Tanzania is the first to a lower-income country that has a (previously planned) value addition component. Meanwhile, the EU is expected to announce its first tranche of “strategic projects” in the coming months.
Consumer country governments must also ensure they do not counteract any proactive support to value addition ambitions with other measures that hinder greater international equity around mineral value addition opportunities. As noted in Key 1, government support to domestic industry in China, U.S. and other higher-income countries is increasing. This not only intensifies the competition faced by low- and middle-income countries; some of this support—in the form of trade restrictions, subsidy regimes and sustainability requirements—could also impede their value addition ambitions in other ways.
The EU signed a new trade agreement with Chile in 2023 that prevents restriction of exports or disadvantaging of EU access to Chile’s minerals, for example. It also limits Chile’s ability to offer preferential prices to domestic value addition facilities by requiring that prices not be set below the export price of the previous year. The U.S. Inflation Reduction Act provides electric vehicle tax credits only for minerals processed in the U.S. or a country for which it has a free trade agreement. While this provision has benefited some low- and middle-income countries, such as Morocco, it likely reduces the potential for value addition investment in others. Sustainability requirements can also have unintended consequences for potential investment in low- and middle-income countries. For example, the EU Carbon Border Adjustment Mechanism will tax products such as aluminum and steel that have a large carbon footprint. If this mechanism is not accompanied by the necessary support to help countries such as Ghana and Mozambique reduce their emissions, it could lock their exports out of the European market.
As low- and middle-income producer governments account for the myriad of agreements, frameworks and mechanisms in their value addition strategies, they must also navigate the complex and evolving geopolitical landscape. For example, Indonesia has so far been unsuccessful in negotiating a free trade agreement with the U.S. to qualify for the Inflation Reduction Act’s incentives due to Chinese dominance in the Indonesian nickel sector. As a result, the Indonesian government is currently attempting to reduce Chinese investment in new projects. How low- and middle-income producer countries leverage this geopolitical competition while managing the associated complexities will be critical for successfully moving along the value chain.
6. Ensure a transparent approach involving citizens every step of the way
Having increased their calls for, and promises of, more value addition, governments of low- and middle-income producer countries are under growing pressure to deliver for their citizens. Establishing value addition projects is also becoming increasingly important for the social license to operate for mining companies. For example, the Ghanaian government’s ambition to establish lithium refining in the country has broad public support, including from civil society groups, which have described it as a “red line.” However, as this brief has set out, value addition will not always be viable for a country, nor will it always generate a net benefit for its people.
Governments and companies must therefore engage the public in value addition planning. Transparency and trust are essential to manage public expectations and to avoid governments pursuing value addition at all costs, for the benefit of only a happy few, or a backlash against the mining sector. Governments and companies must disclose and consult with the public on feasibility studies, environmental and social impact assessments and cost-benefit analyses for value addition projects. Governments should also encourage informed debate about the trade-offs involved, especially when opportunity costs are considerable. Governments and companies must ensure these processes are inclusive, in which marginalized groups are not only included but actively engaged in shaping decisions. Accountability actors—such as parliamentarians, civil society organizations and media—must also play an active role and rigorously evaluate government and company plans.
Failing to involve the public in navigating these complex decisions could leave a country with the worst of both worlds: no or costly value addition, and even more public frustration and disruption of mining projects.
Conclusion
Governments and civil society actors in low- and middle-income producer countries are calling for more domestic value addition of their minerals to increase government revenues, generate jobs and support the development of other sectors. Consumer countries and multistakeholder initiatives are also belatedly acknowledging the inequities of global value chains. However, significant work is needed to translate this focus into viable value addition projects that provide meaningful benefits to people in producer countries including marginalized groups. Time is of the essence. Addressing the historical inequities of the mining sector is critical for meeting the urgent needs of people in producer countries. By reducing the risk of public frustration in these countries, and therefore helping to derisk investment in mining and encourage global cooperation, it is also essential for tackling the climate crisis.
Acknowledgements
The authors thank colleagues across NRGI, in particular Alex Malmqvist, Amir Shafaie, Ana Carolina González Espinosa, David Sefa Adjei, Dorjdari Namkhaijantsan, Erica Westenberg, Lee Bailey, Moise Liboto Makuta, Patrick Heller and Pedro Zapata for providing valuable support, perspectives and advice, as well as the fundraising and operations teams for making this brief possible.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Value Addition, Governance and Global Responsibility: A Roadmap for Equitable Mineral Supply Chains

NRGI’s Suneeta Kaimal spoke at the Mining Indaba 2025, where she discussed the role of governments in developing value chains for critical energy transition minerals with moderator Divyam Nagpal.
Divyam Nagpal, Principal Specialist – Renewable Enerfy, SEforALL:
You participated in the Secretary General’s Panel on Critical Energy Transition Minerals, which emphasized the centrality of advancing equity across the global supply chain. What are the most important steps that international institutions, private sector and researchers can take to ensure that investment in African supply chains is equitable and benefits Africa and Africans?
Suneeta Kaimal, President and CEO, NRGI:
Last year, the UN Secretary General convened a multistakeholder panel on critical energy transition minerals to help define principles and actions to ensure low- and middle-income producer countries are not left behind or made worse because of the energy transition. At the center of the panel’s work was the agreement that achieving justice and equity requires change. Change from the deep-rooted inequities that have long plagued the minerals sector and global supply chains. Change from the destructive, exploitative practices that have left too many countries with neither wealth nor resources. And a change from the pit-to-port model. In fact, in a 2023 survey by the Intergovernmental Forum on Mining, Minerals, Metals and Sustainable Development, more governments named value addition as the main driver for their critical mineral strategy than any other factor.
Given that sense of urgency on value addition, the very first actionable recommendation of the UN Panel report launched last year focuses on advancing value addition, economic diversification and benefit sharing. In the coming months, the Secretary General will establish a new multistakeholder, high-level advisory group to advance these ambitions. To help ensure the success of these efforts, NRGI brought together representatives from governments, the private sector, international institutions, academia and civil society to develop a roadmap to increase value addition for low- and middle-income producers.
Three key recommendations emerged from our discussions to bring equitable, feasible value addition to life:
- First—all voices must be included. Too often, the ambitions of the consumer countries or the global north dominate the global dialogue on energy transition and energy security related to transition minerals. The UN Panel was a welcome step forward in placing the voices and needs of people in low- and middle-income countries at the center of the dialogue. It brought together wealthy and consumer countries with low- and middle-income producers, civil society experts, industry and finance leaders in the same room, at the same table. However, meaningful multi-stakeholder participation shouldn’t be something remarkable, it should be the norm.
- Second—the required international financial support has to be on the table. In the last few years, including here at past Indabas, we’ve heard the likes of the US, EU and Saudi Arabia talk about the importance of win-wins and seen them dangle the prospect of significant financial support to enhance supply chain equity. But without delivering. Take the Lobito Corridor. A project that has the potential to generate benefits for Africans but also carries many environmental and social risks and could end up just reinforcing the pit-to-port model if it’s not accompanied by critical, additional steps to help African governments link these opportunities to broader economic ambitions that contribute to sustainable development for all Africans. For example:
- Support to increase government planning capacity, to enable procurement of the necessary models and data.
- Support in the form of concessional financing to governments that can realistically help address feasibility constraints, including by crowding in more private investment.
- Support to target value addition facilities directly or address bottlenecks in areas such as local skills and transport and energy infrastructure.
Third—global leadership is needed to strengthen governance. Good governance is a critical driver of change in mineral supply chains. It supports strong environmental and social protections. It makes sure that laws are enforced, communities have a voice, and businesses operate responsibly. Without good governance, corruption, weak enforcement, and short-sighted policies pave the way for environmental destruction and social injustice. Now, more than ever, countries committed to responsible mineral supply chains must ramp up efforts for global action that supports stronger governance. But good governance isn’t just a moral imperative—it’s a smart business strategy. The only way mining companies can attract the level of investment needed to meet soaring demand for transition minerals is by reducing the risks that scare investors away. Disputes with governments or communities create uncertainty, drive up costs, and make the entire sector less attractive to capital. By fostering trust, ensuring fairness, and addressing the concerns of all stakeholders, good governance benefits communities and governments, but also the private sector.
Good governance is also a shared responsibility. Our research identified more than 50 cases of corruption in the licensing and contracting of transition minerals projects alone, with cases found in 10 African countries. The companies involved are often based in the world’s wealthiest or most powerful countries, including Australia, Canada, China, Russia, Switzerland, the UK and the US. Each is a signatory to the U.N. Convention Against Corruption, which requires countries to criminalize foreign bribery and—except for China—signatories to the OECD Anti-Bribery Convention. Yet, Transparency International’s latest Exporting Corruption report found that only 2 of 47 countries analyzed are actively enforcing foreign bribery laws (the U.S. and Switzerland). Unless wealthier countries do more to hold companies based in their jurisdictions to account for wrongdoing, African countries will continue to suffer the consequences and we will not reach the fairer, greener world that current and future generations deserve.
The UN Panel on Critical Energy Transition Minerals is an opportunity for catalytic actions that bring together the voices, the resources and the global leadership necessary for Africans and Africa to at last see benefits from their minerals.
Nagpal:
How can African governments move along the value chain given the persistent challenges such as energy and infrastructure bottlenecks? What role should regional cooperation and global actors play in ensuring that value addition can advance?
Kaimal:
From our work with governments and citizens all over the world, we’ve seen the challenges of building new visions that move beyond the traditional mining model and deliver economic value, along with social and environmental benefits.
A key takeaway from our work is that the root of successful value addition is a clearly articulated strategy. Such a strategy helps inform government decision-making on the amount of political capital, time and money to spend, or what trade-offs to accept. It also attracts investment by signaling that a government has a plan that accounts for economic realities and the current impediments and how to overcome them.
A successful value addition strategy must be rooted in the goals of the national development plan, account for economic feasibility, market outlook, rigorous cost-benefit analysis, and include robust, transparent, public engagement. The strategy must also consider individual minerals and stages of the value chain. While Indonesia has learned the hard way, its differentiated approach to value addition—focusing on nickel given its dominant position and taking a more gradual approach with bauxite and copper—is the type of nuance that is required.
Understanding, assessing, and, where possible, increasing the feasibility of value addition is critical to ensure that value addition is more than hype. Governments must consider key drivers of feasibility such as the size of the mineral supply, the transport costs, availability of competitively priced, reliable, clean energy, competing capacity elsewhere, and good governance.
To return to the example of Ghana—in the absence of a clear competitive advantage, most of the gold refineries constructed in Ghana are lying largely idle due to a combination of profitability constraints. Or take Australia, where the government has had to provide subsidies for several decades to keep the country’s aluminum smelters operating.
There are ways to increase the feasibility of value addition—this is where regional cooperation matters. Cooperation between countries can increase economies of scale for value addition facilities, enable specialization of different components to support the production of more complex products and increase the size of the end market. The possible collaboration between DRC and Zambia on the battery value chain provides an example of what the continent needs.
But we know that cooperation is not easy. It must navigate an array of economic and political dynamics. Successful coordination in Africa’s mining sector has yet to materialize. One of the key drivers of future progress will be the capacity of regional and subregional bodies like the African Union’s African Minerals Development Centre, African Development Bank’s African Natural Resources Management and Investment Centre to plan, advocate for and support the implementation of coordination projects. These entities are doing important work with their limited resources, but those resources are insufficient for achieving transformative regional coordination.
This is where international actors can help. African governments and regional bodies must do the legwork to pave the way for fundable, beneficial projects, including by having a clear, evidence-based value addition strategies in place. However, development partners and governments seeking Africa’s minerals must finally step up and put real money on the table. This will support planning and policymaking capacity of African governments and regional bodies, and address the feasibility constraints. It’s in everyone’s interests that they do.
Managing tradeoffs is at the crux of any value addition strategy. For example, Indonesia’s downstream strategy has succeeded at dramatically increasing the percentage of nickel processed in country, but it also brings potential risks in terms of public health impacts in producing regions. As the government assesses the next steps in its downstream strategy, it needs to balance these factors carefully and ensure protections against harm.
Take Ghana—Its aluminum value chain ambitions bring with them the potential to increase the economic returns that the country generates from its mineral endowments. But the plans would require almost all the country’s hydropower capacity. Without other new competitively priced electricity capacity coming online, that will increase electricity costs for other businesses and households.
Unlocking Value Addition
Equitable value addition in mining can drive economic growth and prosperity for mineral-producing countries.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
How to Win the Race to Access Critical Minerals for the Energy Transition in a Sustainable and Equitable Manner?
Baku, Azerbaijan

Access to critical minerals is increasingly understood as a condition without which not to achieve the green transition and energy security. Ensuring the supply meets future demand requires that we work simultaneously on sustainability, equity and financing. In this session, we will hear from initiatives that are trying to strike that balance, what challenges and opportunities they face in the process, and what is required from policymakers and various stakeholders to address these.
Speakers:
- Antonio Hill, NRGI
- Tom Haslett, U.S. International Development Finance Corporation (DFC)
- John Lindberg, International Council on Mining and Metals (ICMM)
- Lisa Sachs, Columbia Center on Sustainable Investment (CCSI)
- Nour Amrani, FLS
Featuring NRGI's
Antonio Hill
Advisor
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Shaping Inclusive Narratives About Just Transition in Colombia

Narratives—the overarching frameworks that shape our understanding of issues—encompass a collection of stories, perspectives, and values that influence public perceptions and policy decisions. NRGI’s Alexandra Malmqvist spoke with Juliana Peña Niño about the crucial role of these narratives in Colombia's energy transition and why NRGI’s work in this area is more timely than ever before.
Why are narratives about the energy transition in Colombia so important?
Colombia has long relied on oil and mining, which account for more than half of the country's exports. Despite some progress on the energy transition away from fossil fuel, including Colombia's current president recently assuming leadership roles in international forums, there is still a lack of clarity at the national level on what this transition should look like and how economic, social, environmental and institutional change might happen.
This uncertainty has led to polarization and narratives opposing the energy transition—primarily led by powerful economic and political actors with vested interests in continued fossil fuel exploitation. These actors have shaped much of public opinion against the energy transition by framing it as unnecessary, arguing that the country is not a significant carbon dioxide emitter and that the transition is detrimental to economic stability and national development. This polarization has turned the discussion into a political debate about who supports or opposes the current government’s agenda.
Civil society organizations, citizens, local communities and Indigenous Peoples are not sufficiently represented in this debate. And among them perspectives are fragmented and scattered. There isn’t a unified alternative viewpoint in the public discourse that considers the energy transition as a desirable, possible, and all-embracing process. Without an alternative narrative that proposes a different vision, the energy transition itself may perpetuate the same historic inequality and inequity and imbalance of power that we see today.
So how has NRGI engaged on narratives in the country? What actions were taken, and what were the main findings or insights gained? Any surprising findings?
NRGI convened a diverse group of 30 individuals representing local communities, grassroots and Indigenous and women’s organizations, academics, and national and international civil society organizations (CSOs) to create a meta-narrative for a just transition as envisioned by various populations and civil society actors in Colombia.
This initiative empowered communities and civil society to contribute more effectively to a public discourse that supports the energy transition. Participants learned about the concepts of stories, narratives and meta-narratives, and their role in strategic communications. For example, a story describes a single fact, while a series of stories form a narrative. A meta-narrative, on the other hand, encompasses several specific narratives, including core values and worldview that underpin them, and explains how we understand our relationships with ourselves, others and the world.
A key objective was to connect emotionally with the participants, fostering empathy for how others are experiencing the energy transition, particularly in Colombia’s north, where coal mines were closed and wind projects established. This work was also inspired by philosopher Martha Nussbaum’s ideas on the role of emotions in shaping public culture and a renewed ideal of justice.
With an academic partner we also used artificial intelligence to analyze outputs in Colombian news media to identify dominant narratives, providing a baseline of how the energy transition was framed by the media. We used this to develop our meta-narrative and ensure it was grounded in evidence.
One of the biggest challenges was balancing different views and the inability to reach consensus on some topics. However, in other areas, we found alternative ways to approach our differences. For example, an Afro-Colombian woman supported the energy transition but opposed new projects in her community due to their negative impacts. As a result, we included the principle that justice entails avoiding overburdening energy-rich regions with large-scale energy transition projects.
Two key aspects of this initiative stand out: first, the diverse contexts and realities of populations across different regions were central to crafting the meta-narrative, which is unprecedented in the sector. Bringing such particularities into the national discussion is essential for fostering a more inclusive decision-making process. Second, the project strengthened social capital by uniting a diverse group of individuals who are now more aligned and eager to continue working collaboratively to influence a just energy transition agenda in Colombia.
How do you ensure that the narratives you promote are inclusive and represent diverse community voices?
The meta-narrative drew on the diverse perspectives, values and ambitions discussed by the participants of a country beyond fossil fuels, with renewable energy sources and a diversified economy. To ensure inclusivity, we actively engaged participants with differing views and experiences. For instance, one Indigenous woman expressed that her community did not want the energy transition, fearing it would increase copper mining, threatening their customary lands and an important water source for their community and the wider region. In response, we included a principle in the meta-narrative that Indigenous communities have the right to manage their own lands. This aligns with Colombia’s constitution, which grants Indigenous peoples’ jurisdiction over their territories, and with the International Labour Organization Convention No. 169, which supports free, prior and informed consent.
Building trust within the group was crucial from the start. We created a neutral, safe and inclusive environment where everyone felt comfortable, respected and valued. This approach was key to building consensus, so we made efforts to prevent and manage situations that could lead to feelings of competition, mistrust or power imbalances, particularly between national and local organizations. The exchange of different types of knowledge—including technical expertise, ancestral wisdom and lived experience—was highly valued and complementary.
As a result, the meta-narrative effectively captured the common goals identified by all members for a just energy transition, therefore supporting the collective efforts to position it in the public discourse.
Watch NRGI's video series from the narratives workshop featuring Colombian civil society's views on the energy transition and the framework for a just transition beyond fossil fuels.
Recently, we held an event aimed at "giving life to the meta-narrative," which provided capacity building on strategic communications and identified key political moments for its dissemination, such as COP16, COP29, and COP30. This event brought together 45 participants, including many from last year, fostering a growing network of individuals from various producing regions of the country who are now exchanging knowledge and strategies for advocacy to influence public discourse effectively.
NRGI is supporting civil society organizations and leaders to implement the meta-narrative in their communications and aiming to position this vision about just energy transition into the public discourse.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Enabling a People-Centered Energy Transition with Renewables and the Mining Industry
Baku, Azerbaijan

This event will explore the need for collaboration between the renewables and mining sectors to achieve the 1.5-degree climate target responsibly, focusing on sustainable supply chains that prioritize people. Following recent global commitments to triple renewables by 2030, the session will explore how these industries can jointly support a just and equitable energy transition, spotlight successful partnerships, and identify policy needs for sustainable growth in key markets.
Featuring NRGI's
Antonio Hill
Advisor
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781
Global Commitment to an International Agreement on Supply Chain Traceability: Lessons from the UN Minerals Panel

On 29 October 2024, NRGI president and CEO Suneeta Kaimal spoke at a Colombian government event at the Biodiversity COP16. These are her remarks.
When UN Secretary-General António Guterres launched the Panel on Critical Energy Transition Minerals he said, “As we reshape how we power our societies and economies, we cannot replace one dirty, exploitative, extractive industry with another dirty, exploitative, extractive industry.”
This is a challenge well known to all of us here at COP16.
Demand for minerals critical for clean energy technologies is set to quadruple by 2040. Most of the known transition mineral reserves are in countries with high biodiversity: Indonesia, the Democratic Republic of the Congo and, closer to home here, Brazil and Colombia.
We need only look to the gold sector to see the detrimental impacts on biodiversity and local communities. Illegal extraction of gold in the Amazon rainforest has led to over 1.9 million hectares of mining deforestation – and about half of that has occurred in just the past five years, according to estimates from the MAAP initiative.
We are also already seeing worrying impacts on the environment and on biodiversity in transition minerals. In Indonesia, rapidly expanding nickel mining has already resulted in the deforestation of an area of tropical forest the size of New York City.
Add to this, that about 40 percent of the mineral production needed will occur in countries with “weak, poor and failing resource governance.” We know from past commodity booms that the boom in demand risks unleashing large waves of corruption. The promise of soaring profits and fast-paced dealmaking increases the risk appetite of private and public sector actors alike – all while regulators struggle to keep up. These corruption risks are exacerbated by the fact that the countries where these minerals are mined rank in the bottom half of Transparency International’s corruption perception index and in countries where civic space is hugely constrained and environmental defenders fear for their lives.
The intersection of biodiversity at risk, poor governance, and the race for transition minerals is a volatile and potentially toxic combination. NRGI’s analysis has shown that industry actors have used bribery and corruption in mining licensing processes to avoid environmental and social impact assessment requirements and get around community land rights. This has contributed to deforestation and destruction of ancestral community land.
So, the question that confronts us, and that animated the work of the UN panel is: What will be the cost not of climate inaction, but of climate action? Will the pursuit of precious minerals and a mining-intensive energy transition leave economic, social and environmental destruction in its wake? Or can we seize the urgent quest to secure a stable supply of minerals and advance clean energy to also usher in a new, more equitable, more just paradigm for mining?
The Secretary-General asked that we, the panel members, design principles in response to the “urgent call from developing countries to ensure that they, and their communities, benefit from the production and trade of critical minerals; and that people and nature are protected.”
The heart of this call was a fundamental shift in the global discussion on critical minerals, which is privileging geopolitical tensions and consumer needs above considerations of environmental and economic equity, and risks replaying the same mistakes of the past.
Though we had only four short months to deliver, we drew strength from the tremendous diversity of the panel. My Colombian colleague Johana Rocha and colleagues from the OECD, expert representatives from the U.S., U.K., EU and China, as well as producing countries like Chile, Indonesia and the DRC. We benefitted from the voices of Indigenous Peoples, youth, trade unions, regional bodies, and multilateral institutions, industry and investors. And a brain trust of more than 300 civil society partners around the world. The multistakeholder nature of our work was a huge asset then – and it is essential to our success ahead.
Despite radically different agendas, the panel members quickly coalesced around seven principles for the governance of transition minerals: the centrality of human rights; the integrity of the planet, environment and biodiversity; the importance of justice and equity; development through value addition, benefit sharing and diversification; responsible fair trade and investment; transparency, accountability and anti-corruption; and international cooperation.
And while agreeing on principles was important progress, given the magnitude of the challenge before us, we knew we needed concrete actions. So our report culminates in five concerted actions reflecting the needs and ambitions of low- and middle-income resource-producing countries. What we heard very clearly from developing producer countries participating in the panel—and those we interact with every day—was a demand to be more in the driver’s seat and to create more spaces to bring forward their voices and leadership in shaping what truly equitable mining should look like. The recommended actions from the UN panel have tried to create that space and timeline for governments and civil society in key countries across Africa, Latin America and Asia to chart the course on how this mineral boom can be different from those of the past.
A critical action we specified in the report was the development of an expert-led, multistakeholder process to design a "global framework for traceability, transparency and accountability along the entire mineral value chain—from mining to recycling—to strengthen due diligence, facilitate corporate accountability and build a global market for critical energy transition minerals."
Traceability refers to tracking the origin and following the journey of a product through the various stages along its production and distribution chain. Traceability must be done holistically – not just about geographical information, but about the experience along the journey – the economic, social, governance, human rights dimensions. For that reason, in the discussion about the panel, we expressly called for traceability for accountability. But traceability is not a panacea, and it must be part of a broader swathe of actions that address economic and environmental equity at its root causes. Our vison as a panel was bolder than a framework, or working group, or report. It was about laying the groundwork for a new paradigm for mining.
But as American inventor Thomas Edison said: “Vision without execution is hallucination.” This is why today’s event is so important. The Colombian government has shown extraordinary leadership in seizing the Secretary-General’s call and executing the expert guidance of this diverse global panel.
NRGI is committed to bringing our experience and expertise to support this Colombia-led initiative. For nearly two decades, NRGI has accompanied reformers from government and civil society around the world to build a shared vision of good governance of the natural resource sector. To ensure that mining resources do not undermine, but rather enable more prosperous, sustainable societies and environments.
In Chile, NRGI is drawing on international research and peer learning, to help implement the country’s new lithium strategy. In the DRC, we are working with partners in government and civil society at the subnational level to ensure that mining translates into concrete benefits for the communities and to support value addition. Across Chile, Colombia, the DRC, Guinea, we are helping partners identify mining anti-corruption reforms in licensing and contracting, operations, revenue collection and management, and artisanal and small-scale mining. And we are working in close partnership with international institutions – whether the OECD, the International Energy Agency and the EITI, to bolster these country reform efforts. We have seen the power of such multistakeholder collaboration, across local, national, regional and international levels to center justice and equity in climate action.
Recommendations for the working group
While we’re here to support, we recognize it is producing countries like Colombia that have the deepest expertise and moral authority to change governance of mining for the benefit of humanity and nature alike. And we are eager for more producing countries to follow their lead. Together, we should all aim to set a high bar on 5 key issues to ensure that our ambitions translate into action. We must focus on comprehensiveness, credibility, consequences, coordination and community inclusion. Let me touch on each briefly.
1. Comprehensiveness
One of the defining elements of the UN Panel recommendation I mentioned earlier is that approaches on traceability for accountability must cover the entire mineral value chain—from mining to recycling. And they must encompass the interrelated issues that define responsible mining practices - ranging from human rights to environmental impacts to social practices and governance. This holistic approach is essential.
2. Credibility
If the aim is to strengthen responsible mining, traceability is only part of the solution; traceability refers to the ability to track the origin and follow the journey of a mineral through the various stages along its extraction, processing and integration into a final product. But traceability and supply chain transparency alone will have no impact without credible, independent scrutiny of industry actions and impacts against high standards of best practice.
3. Consequences
Credibility is intimately linked to meaningful consequences for the company and government entities being scrutinized in due diligence processes. A comprehensive approach to strengthen regulations is required and, as called for by the UN Panel, “support regulators and market actors to incentivize good performance and penalize bad or illegal practices.” These consequences should include measures requiring industry and government actors to compensate impacted stakeholders for environmental harm and social costs caused by their sub-standard policies and actions.
4. Coordination
There is a large constellation of international entities working on issues related to mining and accountability, and there are a number of relevant global frameworks, and industry standards. The development of any new global framework must account for and ensure greater coordination between them. Locating the framework squarely within existing debates and developments in the mining sector is essential. And any new initiative should support the goal of binding regulation and not create new voluntary or “best practice”-type initiatives.
5. Community inclusion
The development of any framework must ensure meaningful inclusion and participation of vulnerable groups in multistakeholder group discussions on the terms and scope, setting standards for industry and government, inputting into due diligence processes, and establishing adequate consequences in cases of poor performance. A truly multistakeholder effort requires equal participation, and meaningful representation from producer countries in the Global South.
Implementing these five Cs—comprehensiveness, credibility, consequences, coordination and community inclusion—will help translate the vision and ambition of the UN panel into concrete change for people and the planet. Building on the launch today, we have an opportunity to build a critical mass of supporting governments and civil society between now and COP29, when the Secretary-General will officially launch the recommendations of the UN Panel on Critical Energy Transition Minerals and then onward to COP30 to consolidate the work of this initiative.
And so today, we are standing together at a crossroads. In one scenario, the planet continues to burn without the critical resources to embrace a low-carbon future. Mineral-producing countries become less stable politically, lose public funds, and suffer environmental and biodiversity losses.
But there is another scenario in which we take steps closer to the Paris goals with a stable supply of minerals. Countries and communities with transition minerals and precious metals harness this demand and use the proceeds to emerge from poverty. The environment is protected, biodiversity thrives, and the rights of all people are respected.
As we stated in the panel report: “Justice requires change.” Building on the leadership of the Colombian government, let us all move one step closer to the change we need.
Notes
-
1
Mixed hydroxide product is primarily produced from laterite (limonite) ores using high-pressure acid leaching.
-
2
For example, copper oxide ore is often processed into copper cathode using hydrometallurgy at or near the mine site. Copper sulfide ore, on the other hand, is processed using pyrometallurgy, with the location of the smelter depending on a range of factors.
-
3
Governments should also consider requiring companies to conduct feasibility studies for mines that are already operating. However, if a company has already committed to exporting most of the production through long-term off-take or mineral or royalty streaming agreements, this may not be worthwhile.
-
4
Companies (along with development partners) could contribute to a basket fund, and a third party or multi-stakeholder panel would oversee the hiring of the feasibility study contractor from a roster of independent, accredited consultants. An example of this scheme in relation to environmental assessments is the Environmental Service of Salzburg (ESS), which is a joint initiative of the local government of Salzburg, the Chamber of Commerce of Salzburg, the Austrian Federal Ministry of Agriculture, Forestry, Environment and Water Management, and the Salzburg utility provider. ESS maintains and selects from a roster of independent, accredited consultants to perform environmental consultancies: https://developmentcorridors.org/wp-content/uploads/2023/06/Chapter-03-1.pdf
-
5
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
6
ICMM members have also committed to comply with the objectives of legally designated protected areas.
-
7
Some types of tax incentives carry a higher risk of significantly reducing government revenue than others. For example, corporate income tax holidays can lead to greater revenue loss than expected, as companies may adjust their operations to frontload profits and take fuller advantage of the incentive. Recent changes to international tax rules, including the establishment of a global minimum effective corporate tax rate, will also diminish the effectiveness of such profit-based incentives. See: https://www.igfmining.org/resource/tax-incentives-in-mining-minimising-risks-to-revenue/, https://www.oecd-ilibrary.org/taxation/tax-incentives-and-the-global-minimum-corporate-tax_25d30b96-en
-
8
Planning and effectively implementing shared use infrastructure is complex. However, successful examples exist. Vale developed a railway for its iron ore mine in Brazil that is also used by other freight and passengers. In Ghana, an aluminum smelter served as the anchor customer that enabled construction of a large hydropower dam in the 1970s that also supplies power to the national grid. The Lobito railway corridor, that will connect an Angolan port to mining activity in DRC and possibly also in Zambia and Tanzania, will hopefully provide further proof of concept.
-
9
The Feminist Natural Resource Governance Agenda, which NRGI co-developed, sets out 18 policy imperatives, including on participation in the workforce and revenue sharing, for centering the leadership and lived realities of women and frontline communities in natural resource governance: https://pwyp.org/feminist-natural-resource-governance-agenda/
-
10
Beyond the more specific risks mentioned in this section, other "classic" mining corruption risks exist for value addition projects: for example, in relation to the monitoring of operations, revenue collection, revenue management and state-owned enterprises.
-
11
For example, Mercedes-Benz has declared they are ready to invest in mining and Tesla has partnered with a nickel mine in New Caledonia. See https://www.reuters.com/business/autos-transportation/mercedes-benz-is-able-willing-invest-capital-mining-ceo-2023-03-30/, https://www.bbc.com/news/business-56288781