
The climate obstructionism of One: Pemex and the case of Mexico
Vitoria-Gasteiz, Spain

The ninth Global Summit of the Open Government Partnership (OGP) kicked off, bringing together more than 2,000 high-level representatives from governments, civil society leaders, and policymakers from around the world. Their goal was to share experiences, best practices, and progress on open government initiatives, and to evaluate their implementation on key issues.
As part of the summit's events, Fernanda Ballesteros, NRGI's Country Manager for Mexico, took part in the side event titled Undue Influence and Policy Capture in the Energy Transition: New Tactics, New Remedies, New Alliances.
The need to tackle climate change and speed up the energy transition is more urgent than ever. Yet, by 2025, the hijacking of transition policies has become a powerful phenomenon that demands immediate attention, in-depth analysis, and innovative solutions.
Fernanda contributed to the debate by explaining the governance challenges and complex interests involved in the case of the Mexican oil company Pemex, as well as proposals to strengthen accountability.
In this context, she addressed the coherence between Mexico's climate and energy policies, and explained how including Pemex in the country's new NDC (Nationally Determined Contribution) is an opportunity to build a more just and transparent future, aligned with the global call to leave fossil fuels behind.
Featuring NRGI's
Fernanda Ballesteros
Mexico Country Manager
Maximizing Opportunities and Managing Risks of Declining Demand for Oil and Gas-Dependent Producer Countries (Climate Week 2)
Addis Ababa, Ethiopia

Almost a decade after the adoption of the Paris Agreement, we remain far off course to meet our goal of limiting global temperature rise to well below 2°C. Most forecasters today, including the International Energy Agency, expect global oil and gas demand to peak before 2030 even in the absence of new climate policies. This decline is driven by new technologies (e.g. in wind and solar power generation) which, as they become more competitive, are replacing fossil fuels in their largest uses. Likewise, major importing regions like the EU and China aim to reduce fossil fuel consumption and imports based on climate and energy security concerns.
Africa plays an important role in this global energy ecosystem. Countries like Nigeria, Algeria, and Libya hold important oil and gas resources and rely on this sector to secure fiscal revenues and finance their economic development. The decline in oil and gas demand will create significant challenges for these economies and worsen pre-existing socioeconomic challenges related to fiscal deficits, debt, currency instability, and low energy access. This puts unprecedented pressure on these countries to not only shift their energy systems but also to transform their entire economies to prepare for this decline. As the energy transition unfolds, governments must take urgent and proactive steps to ensure a people-centered and justice-oriented transformation away from oil and gas dependency.
Leveraging the recent Policy Dialogue on Just Energy Transitions, this event will convene diverse stakeholders from research, policy, labour, civil society and finance sectors to explore the emerging risks and transboundary implications of oil and gas demand decline for (new) producer countries, with a special focus on African perspectives and experiences. The discussion aims to identify evidence-based policy solutions to this challenge, maximizing socioeconomic opportunities and enabling pathways to prosperity beyond fossil fuels.
Featuring NRGI's
Nafi Quarshie
Africa Director
Bridging the Gap Between Methane Policy and Implementation in Nigeria

NRGI’s Tengi George-Ikoli spoke with Nigeria Info FM about why Nigeria must act decisively to cut methane emissions from its oil and gas sector even as it seeks to grow its gas-based economy.
She said:
“Reducing methane emissions is about protecting our economy, health, and future. Nearly half of Nigeria’s oil goes to Europe, but new rules could block dirty fuels. If we don’t clean up how we produce gas, we could lose important buyers. We’ve made promises, but now it’s time to act. That means tracking emissions in real-time, enforcing the rules, and making data open to everyone. The government can’t do it alone. Companies, communities, and citizens also have a role to play. We must start with action to reach our energy and climate goals.”
Decarbonization of Oil and Gas in the Gulf Cooperation Council: The Way Forward

Key messages
- It is unrealistic to expect a complete phase-out of oil and gas overnight. History has shown that a transition from one energy system to another takes time, but COP28 created political momentum, especially in the GCC countries, to invest not only in technologies such as carbon capture and storage (CCS), but also in the energy transition.
- GCC countries each focus on the same four key areas of decarbonization: 1) maximizing energy efficiency while reducing emissions from operations 2) developing renewable and clean energies 3) investing in carbon capture technologies, and 4) institutionalizing the role of national oil companies in decarbonization efforts.
- Ensuring improved emissions reporting by companies will allow for better emissions management and greater reductions in emissions. Companies in GCC countries must follow international reporting guidelines and standards.
- It is important to establish clear, holistic and realistic priorities and action plans for investing in renewable energy, to avoid unproductive projects and financial waste. Detailed, actionable plans to reach net-zero targets in the region are also needed. Ambitious targets are meaningless without concrete steps to achieve them.
- There is also a need to acknowledge the limitations of CCS technologies. While these can play a role, they should not be treated as a primary approach to decarbonization.
Introduction
COP28 in the United Arab Emirates (UAE) will be remembered as the COP of transitioning away from fossil fuels. Weeks of negotiations led to what was named the “UAE Consensus,” which gave political blessing to action towards orderly transitions based on countries’ capacities. Oil and gas companies were also held accountable for their responsibilities in fighting climate change, with the launch at COP28 of the Oil and Gas Decarbonization Charter, in which companies pledged to accelerate decarbonization of their businesses. Signatories included national oil companies from the Middle East and North Africa (MENA) region, such as Abu Dhabi’s ADNOC, Saudi Arabia’s Aramco and Bahrain’s Bapco Energies.
For activists, scientists and campaigners who believe the only acceptable action to fight climate change is to end the production of fossil fuels now, the launch of the voluntary pledges by national oil companies constitutes greenwashing. This sort of criticism must be amplified to pressurize governments and companies to take serious action to reduce emissions. However, such pledges are also important to enable civil society organizations (CSOs), communities and citizens to monitor and hold governments and companies accountable.
The MENA region has historically contributed very little to climate change, but it is currently home to oil and gas giants, with the highest per capita carbon dioxide (CO2) emissions globally. It is therefore important for the MENA governments, NOCs and societies to contribute to fighting climate change. The global community particularly welcomes efforts by the financially rich MENA countries to contribute to decarbonization efforts, and by the giant NOCs of the region to deliver on their commitments.
The Natural Resource Governance Institute (NRGI) has been following the energy transition paths in MENA since 2023. We understand the differences in capacities and needs among the various countries of the region, and acknowledge the fear of transitioning away from oil and gas for countries dependent on these resources for their state revenues. Some countries in the region see opportunities to invest in clean energy for their power sector, in order to provide secure electricity and cut import bills. Fossil fuel-rich countries, such as members of the Gulf Cooperation Council (GCC), are investing in new technologies for clean energy and seeking a place on the global stage to influence the energy agenda.
NRGI has sought to bring these nuances of the energy transition to MENA populations, by creating a space for experts from the region to reflect on these developments and to develop recommendations for action to present to decision-makers and CSOs. To this end, we have organized webcasts in Arabic bringing together regional experts to discuss key topics related to the energy transition in MENA. We are also compiling the experts’ recommendations in a series of briefings, to be the base for actionable advocacy for a just energy transition. Part of NRGI’s just energy transition program, this publication is based on a webcast on the role of GCC governments and their NOCs in decarbonization efforts.
This briefing is part of contribution by the Natural Resource Governance Institute (NRGI) to the just energy transition debate in the Middle East and North Africa. The content is based on a webcast organized by NRGI, in which two guest experts from the region discussed the role of Gulf Cooperation Council (GCC) governments and national oil companies in decarbonizing the oil and gas sector.
Emissions, the oil and gas sector, and development
The Paris Agreement, adopted during COP21 in 2015, sets out global commitments to limit global warming to well below 2 degrees Celsius, preferably to 1.5 degrees Celsius, compared to pre-industrial levels. This requires all stakeholders to reduce and eliminate greenhouse gas (GHG) emissions. Fossil fuel combustion is the primary source of these emissions, via the processes involved in burning coal, oil and natural gas, which release significant amounts of CO2 and other GHGs, such as methane, into the atmosphere. Global climate change frameworks such as the United Nations Framework Convention on Climate Change (UNFCCC) highlight that fossil fuels are the leading contributor to GHG emissions caused by humanity, leading to around 90 percent of all CO2 emissions and almost a third of methane emissions. Within this context, debates and commitments around decarbonization emphasize reducing the average carbon intensity of primary energy sources over time. Five of the top ten oil producers in the world are in the MENA region, in the GCC states. For example, Saudi Arabia, the world’s second largest oil producer after the USA, is responsible for 11 percent of the global share of produced oil. Decarbonizing the oil and gas sector therefore becomes a crucial priority for countries relying on the sector for development and the well-being of their citizens.
Voices in developed countries argue for delinking oil and gas from economic development, but this does not resonate with populations in the MENA region who still depend on their governments to provide jobs and meet their basic needs. The emphasis for resource-rich countries—especially in the Gulf—is on making their oil and gas products the cleanest possible while the world is still economically reliant on oil and gas.
The actions of the oil giants in the region are especially critical, given estimations by the Intergovernmental Panel on Climate Change that limiting global warming to 1.5 degrees Celsius will require global GHG emissions to peak before 2025 at the latest and be reduced by 43 percent by 2030. The substantial oil revenues of the GCC nations position them uniquely not only to lead their own decarbonization efforts, but also to support other MENA countries in their energy transitions, to ensure the whole region is politically and economically more stable than at present.
NRGI’s webcast guest Dr Charbel Moussa of KPMG believes that the political momentum and government buy-in for work on decarbonization technologies and an orderly energy transition was launched at COP28. Dr Moussa stated that, “Today, politically, there is a domino effect, and governments cannot say that we are only going to invest in technology. There also has to be an investment in the gradual transition from oil and gas to other sources of energy.”
GHG emissions can be categorized into three groups, as defined in the Greenhouse Gas Protocol, which is widely adopted across industries, including the oil and gas sector:
- Scope 1 Emissions: Direct GHG emissions from sources owned or controlled by a company. For oil and gas companies, these include emissions from combustion in their boilers, furnaces and vehicles, and emissions from chemical production in their processing equipment.
- Scope 2 Emissions: Indirect GHG emissions from the generation of purchased electricity, steam, heating and cooling consumed by a company. For the oil and gas sector, this primarily involves the emissions associated with the electricity used in extraction, refining and distribution processes.
- Scope 3 Emissions: All other indirect emissions that occur in a company’s value chain, both upstream and downstream. In the oil and gas industry, this includes emissions from the use of sold products (e.g., combustion of oil and gas by consumers), transportation and distribution, and investments, among other activities.
GCC countries and NOC decarbonization policies and commitments
As previous NRGI research highlights, despite their vast financial capacities and low-cost reserves, GCC NOCs face significant financial risks as the global energy transition accelerates. The structural decline in oil demand, driven by decarbonization efforts, may lead to stranded assets and diminished revenues, as global capital continues to shift away from fossil fuels. NOCs such as Saudi Aramco are attempting to diversify into downstream industries such as refining and petrochemicals. However, over-investment in these sectors risks becoming a liability if the global demand for oil and its byproducts declines faster than expected. Thus, while these NOCs are better positioned than many smaller regional players, the need to mitigate financial risks through strategies that do not rely on oil and gas remains urgent.
Against this backdrop, GCC countries signalled their commitment to a greener and more sustainable future by developing and marketing holistic short- and medium-term strategies: Saudi Arabia’s Vision 2030, Oman’s Vision 2040, Qatar’s National Vision 2030, the UAE’s Vision 2021 and its related Energy Strategy 2050, Bahrain’s Economic Vision 2030 and Kuwait’s Vision 2035.
As of 2022, all GCC countries bar Qatar had set a net-zero target for 2050 or 2060. UAE and Oman committed to net zero by 2050, while Bahrain, Kuwait and Saudi Arabia set their net-zero objectives for 2060. For instance, the UAE has committed to reducing its GHG emissions by 40 percent by 2030, compared to “business as usual” levels, by focusing on five key emitting sectors. While these visions are cross-sectoral, the energy sector is the most critical priority for decarbonization across GCC countries. According to NRGI’s webcast guest Dr Mohammed al Breiki from the Gulf Organization for Industrial Consulting, despite the plurality of energy sector decarbonization paths and targets among these countries, they each focus on four key areas:
1. Maximizing energy efficiency while reducing emissions from operations
Due to their high financial capacities, GCC countries are able to lead on and champion technologies and innovative concepts to maximize efficiency in oil and gas operations, while preventing and reducing potential CO2 emissions. For instance, Saudi Arabia has implemented the concept of the circular carbon economy. As Dr Breiki explained, this is “a concept that enables the recycling of carbon coming from different sources by using or capturing it.” Saudi Arabia’s NOC, Aramco, has adopted this concept, operationalizing its principles of “reducing, reusing, recycling and removing” CO2 emissions.
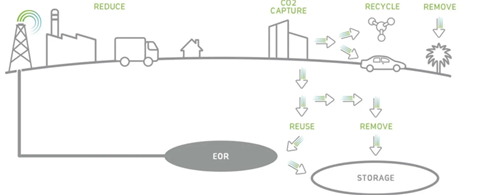
Implementing this concept involves the roll-out of an array of measures and approaches, including investing in technologies to improve the efficiency of internal combustion engines in transport, and planning afforestation efforts. Three NOCs in the GCC have announced or started implementing plans to plant millions of efficient carbon-capturing trees. The Abu Dhabi National Oil Company (ADNOC) has announced the planting of 10 million Avicennia trees, Aramco has announced plans for several million mangroves trees, while Petroleum Development Oman (PDO) has announced it is planting sugarcane to help with the desalination of water that will be used to be injected in the oil wells. The sugarcane bagasse, a byproduct of the plant, will be used as a renewable energy source to power the desalination process, replacing traditional electricity typically generated from oil and gas. This approach not only supports water injection but also contributes to reducing CO2 emissions by using a cleaner energy alternative.
The GCC countries are also advancing innovative and pioneering technologies aimed at reducing CO2 emissions in their oil and gas extraction. For instance, PDO’s “Miraah” project is one of the world’s largest solar thermal facilities, harnessing the sun’s energy to produce steam for use in oil production. According to Dr al Breiki, this technology has enabled the company to save or reduce about 300,000 tonnes of CO2 a year. ADNOC’s Centralized Predictive Analytics Diagnostics (CPAD) initiative uses artificial intelligence and machine learning to analyze data related to operations across the company, to improve operational efficiency and reduce emissions. Qatar is seeking to reduce emissions in the transport of oil and gas through purchasing ships which use liquified natural gas (LNG) or clean fuels such as ammonia and methanol, rather than heavy fuel.
2. The development of renewable and clean energies
GCC countries have established ambitious overall targets for renewable and clean energy production and integration into their domestic energy mixes. For instance, Saudi Arabia aims to have 50 percent of its energy mix from renewable energy by 2030, while Oman and the UAE aim to derive 30 percent of their electricity from renewables or clean energy by the same year. Bahrain aims for 20 per cent of its energy to be renewable by 2035, while Kuwait and Qatar aim for 15 percent and 20 percent respectively by 2030.
Achieving these targets will require GCC countries to increase their renewable energy capacity tenfold by 2030 compared to the 2022 installed capacity of about 5.7 gigawatts. Fortunately, abundant and high-quality solar resources, coupled with the very large scale of solar photovoltaic (PV) projects, mean that the GCC countries are able to produce renewable energy at a very low coast. Currently, solar PV costs less than two US cents per kilowatt hour in the GCC countries, outperforming natural gas, liquefied natural gas, oil, coal and nuclear power in this respect. These countries are already leveraging this advantage. According to the World Bank, the UAE is home to three of the world’s largest and lowest-cost solar plants. The expansion of solar energy production and use will reduce the share of fossil fuels in the domestic energy mix, while also improving efficiency in operations. For instance, as Dr al Breiki stated, the Kuwait Petroleum Corporation has adopted electrical extraction technologies using solar energy to reduce emissions from oil and gas extraction processes.
In addition to solar potential, some areas in the Gulf, such as Saudi Arabia’s northwestern desert and southern Oman, boast significant wind potential. Despite solar PV being more competitive, GCC countries such as Saudi Arabia and in Bahrain are investing in wind farms, through a partnership between Bahrain’s Bapco Energies and the Abu Dhabi Future Energy Company, Masdar. GCC countries are also investing in grey hydrogen (from natural gas) or blue hydrogen (grey hydrogen with carbon capture). For instance, ADNOC currently produces 300,000 tonnes of grey hydrogen annually, and is investigating the potential for green and blue hydrogen production, using carbon capture and storage technology. The company also aims to start producing blue ammonia in 2025 at its large-scale facility, which has a capacity of one million tonnes per year.
3. Investing in carbon capture technologies
GCC countries including Saudi Arabia, the UAE, Qatar and Oman are investing in carbon capture and storage (CCS) technology. This refers to the process of reducing emissions from industries such as fossil fuel extraction, by collecting CO2 that would otherwise have been emitted into the atmosphere, and storing it underground in depleted oil and gas reservoirs and saline aquifers. This technology would arguably enable these fossil fuel producers to “have their cake and eat it” by contributing to meeting domestic net-zero targets while protecting export revenues derived from oil and gas.
GCC countries already have large-scale CCS projects in different stages of development. For example, Qatar’s Ras Laffan LNG carbon-capture facility has a capacity of 2.2 million tonnes per year. QatarEnergy’s Sustainability Strategy also includes a commitment to increase CCS capacity at its facilities to between 7 million and 9 million tonnes per annum by 2030. Similarly, as Dr al Breiki highlighted during the webcast, CCS technology has enabled Saudi Arabia’s Uthmaniyah oilfield “to capture about 40 million cubic meters of carbon dioxide and store it underground to improve oil extraction.” The table below outlines all CCS projects implemented or planned in GCC countries until 2030 to capture CO2 at source or through direct air capture.
Table 1. Carbon capture and storage projects in GCC countries in 2023
| Facility | Country | Operational date | Industry | Capture, transport or storage capacity (million tonnes per annum of CO2) |
Operational | ||||
| Saudi Aramco Uthmaniyah | Saudi Arabia | 2015 | Natural gas processing | 0.8 |
| Qatargas Qatar LNG | Qatar | 2019 | Natural gas processing | 2.2 |
In construction | ||||
| 44.01 Project Hajar | Oman | 2024 | Direct air capture | Under evaluation |
| Qatar Petroleum North Field East | Qatar | 2025 | Natural gas processing | 2.1 |
| QAFCO Ammonia-7 Blue Ammonia Facility | Qatar | 2026 | Hydrogen, ammonia, fertilizer | 1.5 |
Advanced development | ||||
| ADNOC Ghasha Concession Fields | UAE | 2025 | Natural gas processing | Under evaluation |
| ADNOC Natural gas processing plant | UAE | 2025 | Natural gas processing | 2.3 |
| Saudi Aramco Jubail Hub | Saudi Arabia | 2027 | Natural gas processing | 9 |
Early Development | ||||
| Gulf Cryo MEG Plant | Saudi Arabia | 2024 | Chemical | Under evaluation |
| ADNOC TA’ZIZ Blue Ammonia | UAE | 2025 | Hydrogen, ammonia, fertilizer | 0.8 |
4. Institutionalizing the role of NOCs in decarbonization efforts
At COP28 in Dubai, 50 international and national oil companies, representing more than 40 percent of global oil production, signed the Oil and Gas Decarbonization Charter (OGDC). The charter, launched by the COP28 Presidency and the Kingdom of Saudi Arabia, commits signatory companies to key climate actions, namely net-zero operations by 2050 at the latest (Scopes 1 and 2), ending routine flaring by 2030, and near-zero upstream methane emissions by 2030. The charter was launched as one of a series of initiatives under the Global Decarbonization Accelerator (GDA), unveiled during COP28 with the stated purpose of speeding up the energy transition and drastically reducing global emissions. Four GCC NOCs signed the charter: Saudi Aramco, Abu Dhabi’s ADNOC, Oman’s PDO and Bahrain’s Bapco Energies, thereby reasserting and contributing to their countries’ net-zero targets.
The launch of the OGDC targeting NOCs could be interpreted as a diplomatic compromise between the advocates of phasing down and transitioning away from fossil fuels, and those who fear that an accelerated transition would have significant impact on their economies and societies.
Takeaways and looking forward
In the GCC context, this political recognition of transitioning away from fossil fuels has the potential to pave the way for more investment, research and innovation opportunities targeted towards the new GCC generation. This could mean job opportunities for young people who want to be part of the solutions to the climate problems caused by previous generations.
During the webcast, Dr Moussa highlighted the tension that exists in global debates on climate action and decarbonization. Climate action advocates argue for the urgent need to phase out fossil fuels to mitigate climate change, while many government officials and development advocates argue for the continued use of fossil fuels to drive national development and reduce energy poverty. For many resource-rich developing countries, fossil fuels remain a critical source of energy and economic development. MENA governments have therefore been supporting the decarbonization efforts of their national oil companies, despite criticism from environmentalists and climate activists that the emphasis on decarbonization technologies will slow the phase-out of fossil fuels. GCC countries argue that the world needs a wide range of technologies and scientific innovations to tackle one of the most important existential challenge of modern times, and that their NOCs can be part of this scientific and technological advancement alongside the main global players. They also claim it is unrealistic to expect a complete phase-out of oil and gas overnight. As Dr Moussa highlighted, history has shown that a transition from one energy system to another takes time. It is important to acknowledge that even “with alternative energy or clean energy, these energy sources can increase, but oil and gas will still play a role.”
The GCC fossil fuel producers are at the heart of a global debate around the future of energy systems and new economies. They acknowledge the importance of transitioning through their local and international commitments, and the pledges and targets they have set. Some, like the Saudi government and Aramco, are faster than their neighbouring countries in assessing the consequences of the transition and taking action, such as the decision to stop investing in additional oil production beyond their current capacity and to focus on more productive portfolios, such as petrochemicals, refineries and new energies. However, not all GCC countries and their companies have the same financial capacities to act fast without social and economic turbulence.
The seemingly contradictory policies and decisions being taking in some Gulf countries show the difficulties in managing the transition. Countries such as the UAE pledge billions in clean energy innovations, while the government and its oil company also announce investments worth billions to boost oil and gas production. For the Gulf countries, investment in all types of energies has been the mantra from the beginning of the energy transition negotiations as a way to show agency in decision-making and deciding the fate of their countries, without denying their shared responsibility in the global quest for solutions to climate change. For the UAE, leadership in oil and gas development is not only part of its economic development plan, but also part of its global political leverage, while for other countries, such as in Kuwait, the sector is more a question of generational issues. From this perspective, the region’s political leadership is seen as needing to shift to younger generations, able to think differently and view current economic and societal problems from a different angle than oil and gas resources. There is a shift in how the oil and gas sector is viewed by Gulf citizens, with less political power residing in the oil and gas sector, and an increasing focus on other sectors. This will enable the region’s leaders to reach a position where they could reduce spending on oil and gas, and even consider being the first in the region to transition away from fossil fuels.
Increasing NOCs’ role in decarbonization
Ensuring improved emissions reporting
Effective and transparent reporting on emissions by NOCs and smaller companies remains a critical challenge. Without accurate data, it is impossible to ensure responsibility for emissions or to meaningfully reduce them. As Dr al Breiki highlighted during the webcast, improving reporting is a necessary first step in holding companies accountable. NOCs in the GCC countries follow a variety of international reporting guidelines and standards, to varying degrees. For instance, Aramco’s GHG reporting aligns with International Petroleum Institute Environmental Conservation Association (IPIECA) Petroleum Industry Guidelines for Reporting Greenhouse Gas Emissions, as well as the Greenhouse Gas (GHG) Protocol of the World Resources Institute and the World Business Council for Sustainable Development. This is a positive step, and one that must be taken by all Gulf NOCs. In addition to helping achieve decarbonization targets, accurate reporting offers economic benefits for exporting countries. For instance, without the data from the exporter, European Union (EU) importers must use the EU’s “default” emissions level for each product, which is assumed to be greater than actual emissions, thereby incurring a financial penalty to the exporter. Reporting actual emissions and then working to reduce them therefore limits costs from the EU Carbon Border Adjustment Mechanism (CBAM) and EU methane rules.
The Extractive Industries Transparency Initiative (EITI), with its multi-stakeholder structure and the introduction of its 2023 Standard, also offers a pathway for improved company transparency and reporting of GHG from exploration and production. For example, NRGI’s recent report on methane emissions in Senegal’s oil and gas sector highlights how the EITI can help governments and companies enhance transparency in methane emissions reporting. While Senegal is an EITI implementing country, GCC countries and NOCs can align their GHG reporting with the Standard even as non-implementers.
Expanding accountability to Scope 3 emissions
According to Dr al Breiki, “Most companies setting targets focus only on reducing emissions in Scopes 1 and 2, neglecting Scope 3 emissions.” This is inadequate, as Scope 3 emissions—those resulting from the consumption of oil and gas products—are significantly higher than Scope 1 and 2 emissions combined, accounting for the overwhelming majority of total emissions from major oil companies.
Despite Scope 3 emissions being four times higher than Scope 1 and 2 emissions, they are frequently overlooked by NOCs and other oil and gas companies. This critical oversight, where the bulk of fossil fuel emissions occur at the end of the value chain during combustion by consumers, must be urgently addressed in any comprehensive decarbonization strategy. In July 2023, Bapco Energies launched its Sustainability Linked Finance Framework, allowing the company to link its financing with decarbonization goals, in line with the Bahrain’s commitment to sustainability and climate action. According to the company’s 2023 Annual Report, Bapco claims to be the first NOC to include Scope 3 emissions reduction commitments. Other NOCs in the region are still not doing this, but such decisions by governments and companies must be encouraged within the context of fighting climate change.
Incentivizing NOC decarbonization: carrot and stick
NOCs across the GCC countries are currently not incentivized to divert resources away from their vast oil and gas reserves towards new technologies which may offer less immediate financial return. Gulf governments can draw lessons from existing international policies, such as the U.S. Inflation Reduction Act (IRA) and the EU’s CBAM and carbon tax. As Dr Moussa stated, a combination of incentives (the “carrot”) and regulatory pressures (the “stick”) can push NOCs towards decarbonization efforts. The IRA, for instance, offers financial incentives for companies investing in clean energy technologies, while the EU’s CBAM imposes penalties for continued high-emission practices. If governments in the Gulf region adopt a similar dual approach towards their companies, this could drive meaningful progress in reducing emissions while maintaining economic stability.
Establishing clear, holistic and realistic priorities and action plans
When evaluating energy transition policies, it is essential to assess their impact across multiple dimensions: economic, financial, human and practical, both in terms of effectiveness and efficiency. As Dr Moussa noted, successful energy transition policies must balance these diverse factors to ensure both long-term sustainability and immediate practicality.
Investing in renewable energy
Investment in renewable energy production is undoubtedly a positive priority, but it must be approached with economic sensitivity. According to Dr Moussa, “If the company wants to invest in renewable energy, it is better to sell electricity than to use it for their own needs to replace oil.” Renewable energy investments by NOCs should focus on creating broader economic value through the sale of electricity to consumers, fostering a transition that benefits both the environment and the economy.
In other words, although GCC countries have set ambitious renewable energy targets, there is need for a strategic focus on renewable energy investments that generate fresh revenue streams, rather than merely replacing oil for domestic use. NOCs could prioritize selling renewable energy to external markets, leveraging the economic value of clean electricity. This approach not only contributes to the global energy transition, but also helps reduce financial risks from declining fossil fuel demand, safeguarding these countries’ economies during the transition.
Putting in place context-sensitive strategies and policies
For energy transition strategies to succeed, they must be realistic and sensitive to local contexts. For instance, despite the MENA region’s great solar potential, simply installing solar panels on a large scale is insufficient if the supporting infrastructure, such as the electricity grid, is unable to handle the output, or if industries are designed primarily for oil and gas consumption. In such cases, the benefits of solar energy remain unrealized, and progress stalls. Therefore, policies must be tailored to existing capabilities, and include investments in infrastructure upgrades that can support new energy sources.
Acknowledging the limitations of CCS technologies
CCS technologies are often promoted as a solution that will reduce emissions, but they are not without significant limitations. CCS has questionable economic and financial returns, often requiring substantial investments with minimal profitability. For GCC NOCs, focusing too heavily on CCS technologies might expose them to further financial risks, especially as the global market increasingly prioritizes renewable energy sources and low-carbon technologies. While CCS can play a role, it should not be treated as a primary solution for decarbonization, and investments in energy efficiency and renewables should take precedence.
Establishing actionable and detailed plans for net-zero targets
One of the key challenges facing the global decarbonization effort is the lack of clear, detailed action plans. As Dr al Breiki argued, “most countries set targets for net zero, but fail to provide clear annual action plans to reach those targets.” Ambitious targets are meaningless without concrete steps to achieve them. Governments and NOCs must develop transparent, year-by-year roadmaps that outline how they plan to meet their net-zero commitments, ensuring that targets are not merely aspirational, but are also actionable.
Acknowledgements
NRGI extends its gratitude to Dr. Charbel Moussa and Dr. Mohamed ElBreik for their insightful contributions as guests on the NRGI webcast on Decarbonization in the GCC countries.
We also thank Hanen Keskes, former MENA senior officer, for her valuable contributions to this work.
Conditional Support for Pemex: Achieving Financial Sustainability During the Energy Transition

Key messages
- Mexico must reform its financial support for the national oil company, Pemex. Since 2013, the state has given 2.8 billion pesos (about USD 140 million) to Pemex. This support has made Pemex dependent on the state and has led to inefficiencies.
- In 2025, there is a window of opportunity open to reform state support for Pemex. Mexico’s new government has taken office and will write a new Federal Expenditure Budget, following constitutional reform that has changed Pemex into a Public State Company.
- There is mounting pressure for reform in the next round of debt refinancing for Pemex. The company’s USD 100 billion debt is alarming creditors, leading them to require higher interest rates from Pemex.
- Before granting another round of state support, the government should establish clear conditions for such funding. International experience—for example, from Eskom, the state electricity company in South Africa—shows that conditionality contributes to financial sustainability for state-owned businesses. Eskom’s experience offers lessons on how to design and administer support for Pemex.
- A powerful condition for support could be that Pemex assesses and mitigates the risks for its business stemming from the global energy transition. This could involve scenario planning; aligning its business plan with the country’s climate plan; implementing a just transition plan for oil-producing regions, and managing the closure of petroleum infrastructure.
Mexico’s national oil company, Pemex, is in financial crisis. It has debt approaching USD 100 billion, equivalent to 6 percent of Mexico’s Gross Domestic Product, and oil production is declining. While state financial support is necessary to keep Pemex afloat, it has contributed to a company culture of unsustainable and costly dependency. The global energy transition adds to the crisis, threatening to permanently reduce global demand for oil, along with oil prices.
Pemex needs about USD 22 billion to meet its debt-related commitments up to 2026. In 2025, it faces USD 9 billion of debt that matures. By 2026, this rises to nearly USD 13 billion. With the arrival of Mexico’s new federal government, there have been discussions about how to support Pemex more effectively. Various ideas have been floated, seeking to modernize the company and restructure its debt. However, there has been little discussion of how to address the issues related to unconditional state support for Pemex.
The constitutional reform on strategic areas and companies, approved in October 2024, reclassified Pemex and the Federal Electricity Commission (CFE) from State Productive Company (Empresa Productiva del Estado)—the status assigned to them in the 2013 energy reform—to State Public Company (Empresa Pública del Estado). This change seeks to “return to Petróleos Mexicanos and the Federal Electricity Commission their public character in order to fulfil their social responsibility.”
The constitutional amendment provides an opportunity to define more clearly in secondary legislation the remit associated with the new title, including the commercial and public-interest objectives of these companies. It also offers scope to define the support mechanisms applicable to them.
Through this analysis, we seek to promote informed discussion on how to improve the effectiveness of financial support for Pemex, involving policymakers, government representatives, the company’s management team, academia, civil society organizations working on tax and climate justice, and other stakeholders.
In this document we explain why the state needs to set conditions for support, to promote improvements in Pemex’s commercial, environmental and social performance. These conditions are not necessarily designed to reduce financial support or limit Pemex’s investment capacity—one of the factors behind its current plight. Rather, they aim to incentivize the company to better use public resources. We also describe the main problems in the current support model, before suggesting a set of preconditions and conditions for future support. Consideration of these conditions is highly relevant, given the likelihood of Pemex needing more bailouts8 in the future, possibly on an even larger scale than past support—especially if the state decides to assume part or all of the company’s debt.
Mantente al día
Accede al reporte de NRGI que busca promover una discusión informada y mejorar la efectividad del apoyo financiero a Pemex.
TeraMed’s Campaign to Unlock the Mediterranean's Renewable Energy Potential

The Mediterranean region, home to over 500 million people, is warming at a rate 20 percent faster than the global average, making it one of the most climate-vulnerable regions in the world. This warming threatens not only ecosystems and water sources but also critical industrial sectors such as agriculture. At the same time, growing populations and economic development are driving increases in energy demand, placing immense pressure on already strained energy systems.
These harsh realities were on the minds of delegates from the region to the COP29 climate conference in Azerbaijan. And they have motivated NRGI to support the innovative TeraMed initiative over the fortnight-long meetings in Baku. The initiators and supporters of the initiative from both shores of the Mediterranean took advantage of the global gathering, organizing roundtables and panels to highlight the potential of the region to accelerate the development of clean energies, and urging governments to act. Led by IRENA and the Global Renewables Alliance, TeraMed will continue to campaign in Mediterranean countries beyond the COP gathering.
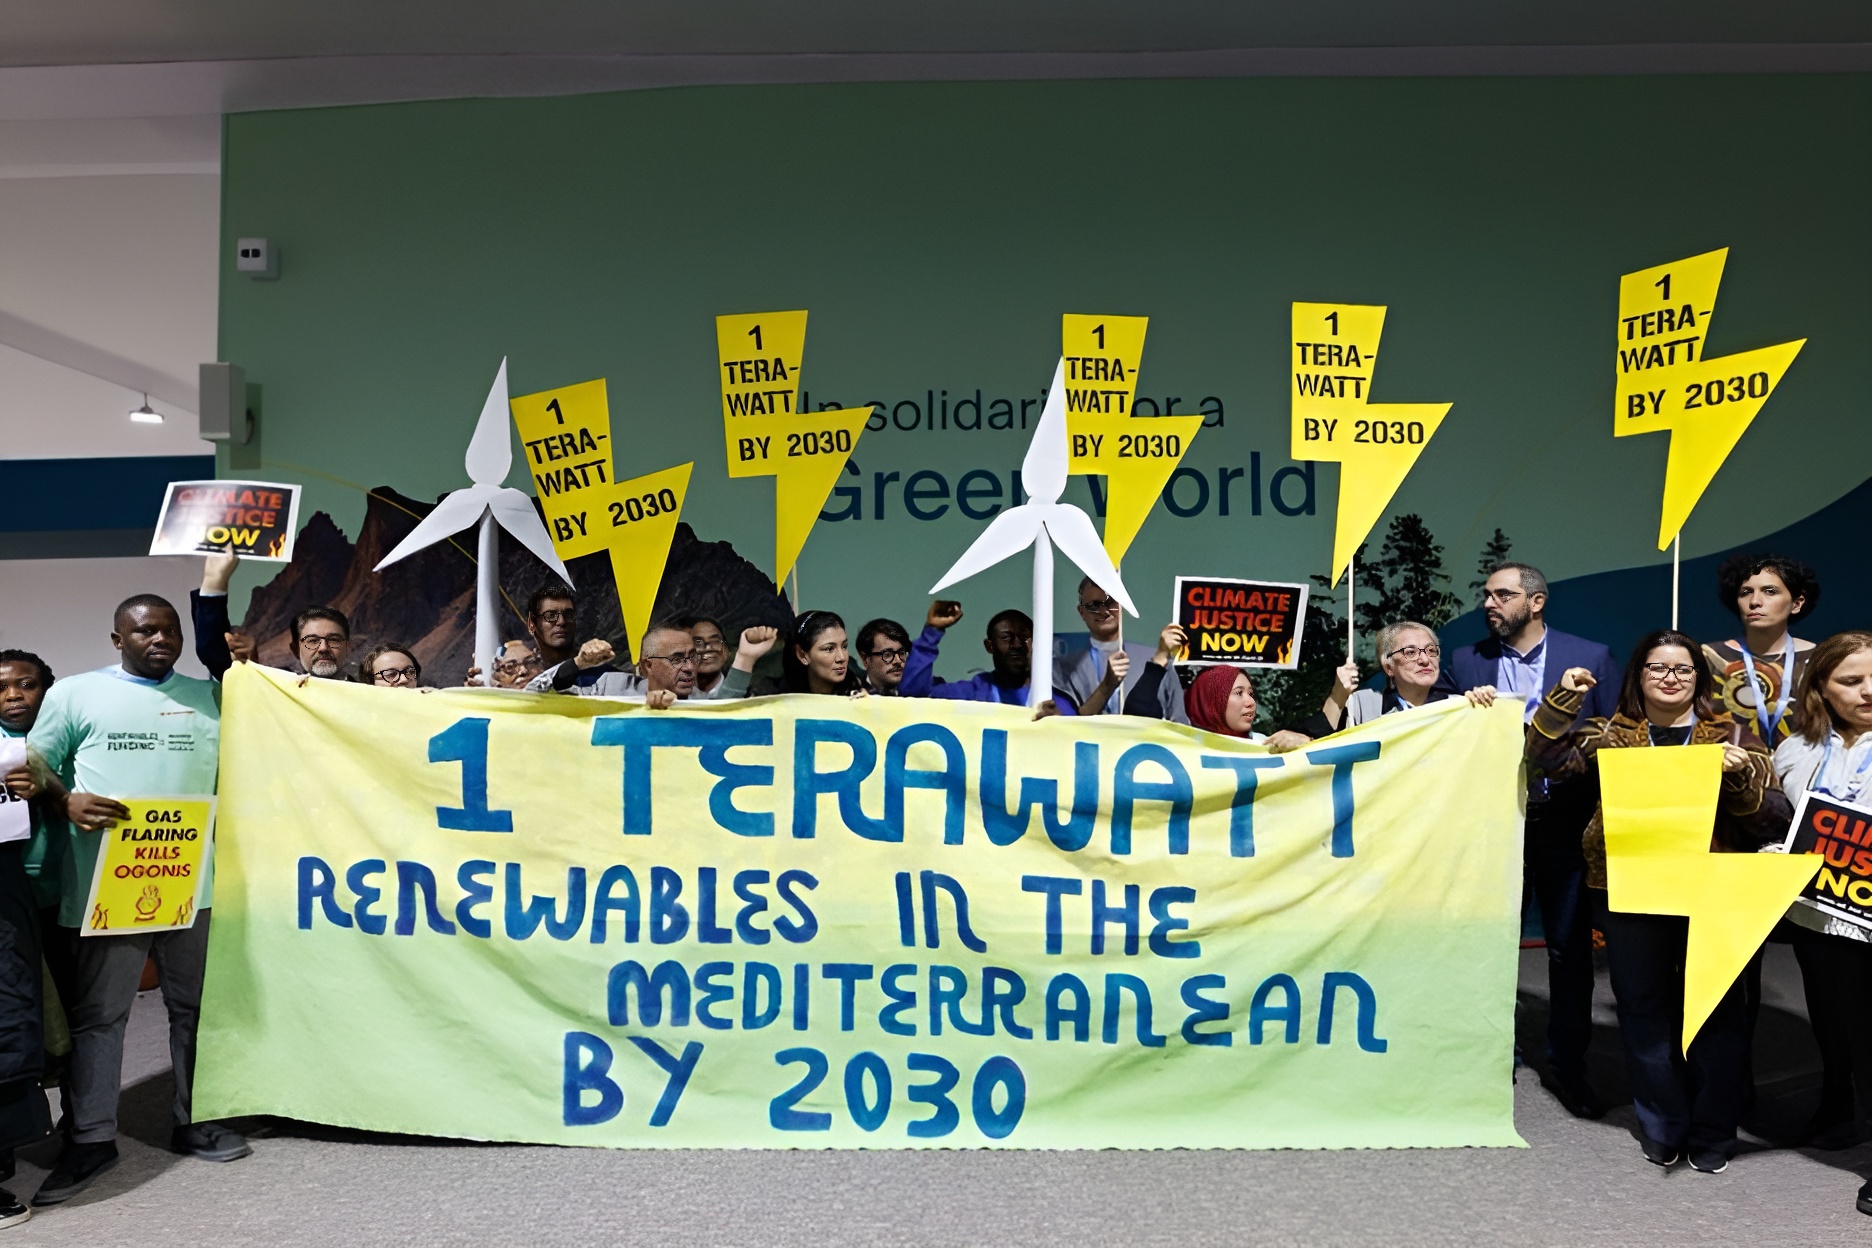
TeraMed is a bottom-up initiative launched by civil society organizations in the Mediterranean region. It aims to support climate change mitigation and also catalyze regional economic growth and promote energy equity between the northern and southern sides of the Mediterranean. TeraMed is pushing governments in the region to commit to accelerating the deployment of clean energy to reach a cumulative installed renewable energy capacity of 1 terawatt (TW) by 2030, in accordance with the global commitment made during COP28 in Dubai to triple renewable energies by that year. To reach that goal, the world needs to increase its energy production capacity to 11 TW.
This ambitious initiative underscores the region’s untapped renewable energy potential and its crucial role in driving the energy transition while addressing climate resilience and socio-economic disparities. According to ECCO, an Italian think tank and one of the initiators of TeraMed, the Mediterranean region has the potential and capacity to reach 4.5 TW from wind and solar; of that 3.5 TW could be generated from the southern shores of the Mediterranean. Also, according to ECCO’s study, pursuing the 1 terawatt goal could unlock investments of around USD 700 billion and create up to 3 million jobs in the direct supply chain of wind and solar.
The transition to renewable energy is no longer just an environmental imperative for the Mediterranean; it is also a strategic necessity. Solar and wind power offer a clear pathway to achieving energy security, reducing reliance on volatile fossil fuel markets, and addressing affordability challenges. However, unlocking this potential requires more than just ambition—it demands stronger regional partnerships, sustained investments, and effective mechanisms for technology transfer.
No government or society can stay neutral in the global fight against climate change, and countries must accelerate the just energy transition through clear commitments and inclusive processes. The TeraMed initiative focuses on two levels of commitment: national and regional.
Calling for country-level commitments
The initiative emphasizes that in order to achieve the one terawatt target, the governments of the region—from both northern and southern shores—must set clear national renewable generation targets. It also encourages governments to empower local communities to contribute to and benefit from renewable energy projects.
At the country level, the initiative calls for governments to endorse clear national renewable energy targets; this requires national capacities to assess needs and opportunities in order to set realistic and achievable targets. To achieve these energy targets, governments must overcome a range of regulatory and policy challenges that might be discouraging foreign investment.
Governments should also include local communities in decision-making processes. The social acceptance of renewable projects is crucial, especially on the southern shores of the Mediterranean. Communities need to understand how they will benefit from big energy projects, and this understanding will only come from governments who have a clear vision, targets and plans for making the energy transition an opportunity communities and citizens. These government plans should produce better environmental conditions, benefits in the form of affordable energy, and more efficient government spending.
In southern Tunisia, we at NRGI have worked to address these challenges by supporting the creation of RATÉJ (Réseau Associatif pour la Transition Énergétique Juste), the first coalition for a just energy transition in the region. This network brings together associations from areas hosting large-scale renewable energy projects, ensuring that local communities have a platform to advocate for their needs and priorities. By empowering these associations and facilitating dialogue between communities and policymakers, we have demonstrated the importance of inclusive governance in achieving social acceptance of projects and ensuring that the energy transition is an opportunity for everyone.
Regional cooperation for a just transition
Collaboration across Mediterranean nations is key to overcoming existing disparities in energy capacity. While some countries have made significant strides in renewable energy deployment, others lack the resources or infrastructure to follow suit. Closing this gap will require a unified effort to share technology, expertise and financing, creating a foundation for equitable growth across the region. By working together, Mediterranean countries set an example of how regional cooperation can tackle shared challenges while building a sustainable and resilient future.
TeraMed also calls for Mediterranean countries to collaborate more and better; create pathways for shared investments in advanced green technologies; and build a harmonized regulatory framework that supports a smooth energy transition.
The initiative is working toward interconnectivity between the northern and southern shores of the Mediterranean. TeraMed organizers say that “an interconnected Mediterranean region opens new opportunities for green industrialization, leveraging processes of nearshoring, greenshoring and friendshoring to foster an environment conducive to the electrification of final consumption, additionally advancing socio-economic gains of the entire Mediterranean region.”
While this promises mutual gain for Europe, North Africa and the Levant, it could also lead to unfair outcomes. The southern countries have resources and sustainable development needs, and the northern countries have their decarbonization goals, the technologies and the funds. This constitutes an unbalanced starting point, and so the initiative should promote just transitions. So the northern partners in the initiative and the organizations working on promoting the deployment of clean energy must ensure that local companies in the southern countries equitably benefit from the projects, and that the projects stimulate substantial employment in North Africa. In addition, it is very important for civil society organizations on both sides of the mediterranean to together advocate for transition financing that will not add new debt burden on governments.
The Mediterranean region holds immense potential to pave to way to what could be a just energy transition that involves countries from the global north and global south. The success of the just energy transition in the Mediterranean will depend on the political will to let go of extractivism, fostering collaboration across borders, investing in inclusive policies, and ensuring that no community is left behind.
Cross-Country Reflections on Coal and Just Transitions in Colombia, South Africa and Indonesia
The experts discussed on the current policy landscape for just transitions from coal in the context of Colombia, South Africa and Indonesia. One expert representing each country highlighted the unique barriers each country faces in phasing out coal production and reflect on how civil society can support just energy transitions. This panel conversation was followed by remarks by discussant Kerstin Mohr and an open Q&A.
Panel discussion:
- Juliana Peña Niño (National Resource Governance Institute), Colombia
- Ilham Rizqian Fahreza Surya (Institution for Essential Services Reform), Indonesia
- Muhammed Patel (Trade and Industrial Policy Strategies), South Africa
Reading the COP28 Tea Leaves on Gas

You’ve seen the headlines: the final agreement from COP28 includes some long-overdue if limited commitments to move away from fossil fuels. But then there is this sentence, tucked away in paragraph 29: “Transitional fuels can play a role in facilitating the energy transition while ensuring energy security.” It reads almost like a throwaway line, yet some commentators and state parties see it as the biggest of a “litany of loopholes” that could entrench fossil fuel use for decades.
What exactly is a “transitional fuel”? The agreement doesn’t say, but the term has been used in the past to refer to fossil gas. Fossil fuel lobbyists were out in force in Dubai, as were climate negotiators from some of the world’s biggest, wealthiest and most influential gas exporters like the U.S., Australia and Qatar.
This comes as less wealthy governments across Africa, Asia and Latin America are making plans to produce and burn more gas in the name of energy security. The list includes Colombia, Ghana, Lebanon, Mexico, Nigeria and Senegal. Their leaders argue that this will give them sufficient, uninterrupted electricity service; lower, more stable energy costs and prices; and the ability to make decisions about energy free from foreign interests, rules and norms.
Some of these countries will need gas to achieve these goals, at least for a while. But perversely, depending too much on gas for energy security can make economies and energy systems—and ultimately, the lives of people—less stable.
The challenges start with predicting how much gas a country will need for its own energy. It is simply hard to know how many new users of gas a country will have, how long it will take to build new gas infrastructure, or how quickly the country will transition to cleaner energy sources. The costs of a bad guess can be high, from electricity shortages to wasted public revenues, as countries like Ghana, Thailand or Egypt have learned.
And governments of some lower- and middle-income countries aren’t being realistic about where future gas supplies will come from, rolling out big plans that will not materialize for several reasons. The extraction of gas for domestic use rather than exports is becoming especially tough to finance: investors see it as not only bad for the climate but also unprofitable. If a country’s remaining gas reserves cost too much to produce, the state will probably have to spend more on subsidies or make consumers pay higher prices for electricity and other goods and services made with gas.
And what happens when a country cannot extract enough of its own gas to fuel the power plants and other domestic gas infrastructure it has built? Its main choice will be to buy imported gas, either through pipelines or aboard ships, as liquified natural gas (LNG). Deals to import gas can play a role in boosting energy security, yet governments should approach them with caution. They can tie a country’s energy system to many forces and events outside its control, sometimes with disastrous results.
In the worst cases, dependence on imported LNG can send shock waves through an economy, as middle-income South Asian gas producers like Pakistan and Bangladesh learned after Russia invaded Ukraine in 2022. Sudden LNG shortages and record prices led to closed power plants and factories; skyrocketing electricity costs; weaker local currencies and foreign exchange shortages; costly public debt; high inflation; millions of lost jobs; and a return to even dirtier, dangerous fuel sources like coal and private generators.
Faced with such risks, governments need to find right-sized, time-bound roles for gas. Otherwise, they could lock their people into using an unsustainable, expensive, polluting fuel with a very uncertain future. They also need to fully consider renewables as an alternative to gas.
Gas advocates rightly claim that solar and wind power cannot yet provide everything gas can: they are not ingredients in fertilizer or plastics, for instance, nor can they make heat for manufacturing cement, steel or other metals that countries need. Renewables also come with their own challenges, like intermittent power supply and high up-front costs, which can make them a tough choice for lower-income countries. Compared to gas power plants, though, solar and wind farms can be easier to plan for, quicker to build, less dependent on foreign energy prices and market trends, and more attractive to a wider pool of investors. All these advantages are likely to increase with time.
As part of NRGI’s work on domestic energy transition, we aim to help decisionmakers and oversight actors in the countries where we work, from Senegal and Nigeria to Mexico and Colombia, interrogate whether further investments in gas truly will make them more secure. The second part of our gas-to-power framework, coming in January, will focus on this question. The framework helps non-experts in government, civil society, research and the media weigh the competing claims around gas, laying out the latest thinking in a balanced way.
In the current debate around gas extraction and use, buzzwords like energy security can obscure the risks countries can face if they invest too much in gas, as well as the challenges of leaving fossil fuels behind. A different kind of debate is needed, one that focuses more on which energy sources can best meet a country’s needs at the least cost to its economy, people’s lives and the planet. COP28’s nebulous nod to “transitional fuels” shows there is still work to be done.
State Oil Companies Betting Billions Against the UAE Consensus

After the COP28 UN climate conference in Dubai unprecedented attention has finally landed on the hidden half of the world’s oil and gas industry: national oil companies (NOCs). These state companies produce half the world’s oil and gas, yet their finances and operations are often hidden from the view of their countries’ own citizens.
Bringing to light and engaging with the operations of NOCs is now crucial and urgent. The landmark agreement by 195 countries in Dubai—the “UAE Consensus”— calls for a “transition away from fossil fuels.” Having slow-walked climate action for decades, the richest and most polluting countries have left the global carbon budget so tight that even NOCs in the poorest countries have little time to transition.
(Meanwhile NOCs’ efforts to reduce carbon and methane pollution from the production of oil and gas are insufficient. The Oil and Gas Decarbonization Charter announced in the early days of COP28 falls well short of what is needed to reach the Paris Agreement goals.)
The COP decision sends a clear message to national oil companies and their governments: look to a greener future. Instead NOCs are on course to spend $1.8 trillion in the coming decade to produce fossil fuels. This is mostly public money funding oil and gas in amounts far beyond levels consistent with a 1.5C upper temperature increase limit.
In essence, this money is a big bet that energy transition fails. More than two-thirds—$1.2 trillion—of this spending will only break even if the world consumes oil and gas at a rate that will cause catastrophic climate change. Not only does the UAE Consensus make this bet look riskier but governments with shrinking pockets will be less able to bail out NOCs whose bets turn bad. Across countries with NOCs, the average government debt as a proportion of gross domestic product doubled between 2011 and 2021.
How might NOCs and their governments respond? They must first recognize that there can be no more business as usual. Either the global transition fails to meet the UAE Consensus and the resulting climate crisis hits hard, or the transition erodes fossil fuel demand on which these countries depend.
From there, they should assess how their strategies will fare in a range of energy transition scenarios. How would revenue shortfalls affect the economic health of their countries? Saudi Aramco and ADNOC enjoy plentiful, low-cost oil that positions them to be among the “last producers standing.” But most NOCs don’t.
Where profit hinges on global climate inaction, NOCs must pursue new pathways or right-size their spending plans; and if they don’t or can’t, their governments should tighten the reins.
Before COP28, we examined the public statements of 21 leading NOCs and found that more than half hadn’t even acknowledged the threat of the global energy transition to their business models and the fiscal well-being of their countries. And fewer than a quarter had articulated plans to mitigate this risk. The global call to transition away from fossil fuels may now change these attitudes.
Amid a largely discouraging picture, some positive examples stand out. Colombia’s Ecopetrol has disclosed a detailed analysis of transition risk and the use of risk assessment tools. This is bold—the company’s portfolio relies heavily on high-cost oil that won’t make economic sense in a greener future—but acknowledging risk and identifying options are the first steps to progress.
Yet with few obvious options for replacing the revenues and energy that oil and gas bring, political leaders and NOC executives in such countries will likely remain hooked on hydrocarbons. They need support to take these steps.
NOCs and their governments—especially the lowest-income producers with the least ability to transition their economies on their own—shouldn’t bear the whole burden of transition. Wealthy, heavily polluting countries should be the first and fastest to phase out their production—and to finance transition in lower-income countries where citizens disproportionately suffer climate impacts and have contributed far less to warming. Without concrete commitments by wealthy countries on this front, the call for a “just and equitable” transition in the UAE Consensus risks falling flat.
The UAE Consensus requires both NOCs and the international community to respond, and to do so in this crucial decade.
National oil companies are making risky bets amid the energy transition
Managing Senegal’s Oil and Gas Revenues

Key messages
- The oil and gas sector it is not expected to transform Senegal’s economy or public finances. Fields that have received a final investment decision are are unlikely to generate revenues over 3 percent of GDP.
- Senegal already possesses some of the institutions needed to promote good revenue management of oil and gas revenues, including: (1) a relatively transparent and comprehensive annual budgeting process; (2) robust compliance with Extractive Industries Transparency Initiative (EITI) standards; (3) a relatively free and vibrant media.
- Given Senegal’s acute domestic investment needs, the government’s new sovereign wealth fund proposal may be ill-timed. Such funds are not the best vehicle for investing natural resource wealth domestically. Instead, the government should consider investing these funds through the budget. It could also be advisable to employ an expenditure rule limiting government spending, or a non-resource current balance rule preventing governments from squandering resource revenues by running a deficit in other areas, combined with a capital expenditure growth rule to mandate investment.
- The national oil company, PETROSEN’s debt accumulation and revenue retention pose significant risks for public finances over the coming years. The government should consider strengthening oversight of PETROSEN, for instance by appointing independent board members, publishing independent audits and clarifying the company’s dividend policy.
- Some fishing communities in Senegal are concerned about the impact of oil and gas projects on their livelihoods. If these negative impacts are confirmed, the authors of this report recommend that the government consider compensation through environmental and social management plans, as opposed to allocating a fixed share of resource revenues to sub-national governments.