
Beyond Extraction: Why COP32 Must Redefine Africa's Role in the Global Energy Transition

As the world prepares for COP31 in Turkey, Nana Dr. Antwi-Boasiako Amoah, Chair of the African Group of Negotiators on Climate Change, looks ahead to COP32 in Ethiopia in 2027. He argues that COP32 offers Africa an opportunity to redefine its role in the global energy transition, using its critical minerals to build stronger economies, deepen regional cooperation and secure a fairer share of the value they create.
In 2027, COP will return to Sub-Saharan Africa for the first time in 15 years. When historians reflect on this moment, Africa should be remembered not just as the host of another climate conference, but as the continent that helped redefine action at the intersection of climate and development transformation.
If this lofty ambition is to be realized, it will depend on how the continent comes together to leverage and govern its critical transition minerals. Around the world, governments and other non-state actors, especially the private sector, are investing trillions of dollars in clean energy technologies and infrastructure. Demand for the minerals needed for clean energy technologies is expected to continue rising sharply over the coming decades.
Africa is well placed to benefit from this new minerals boom, as it is rich in many critical mineral reserves. To name just a few examples: the Democratic Republic of the Congo remains central to global cobalt production; Zambia and the DRC anchor one of the world's richest copper belts; Guinea is indispensable to global bauxite supply; and South Africa continues to play a leading role in platinum group metals.
It is clear that the success of the global energy transition will depend significantly on Africa and her resources. Yet, there remains a real risk that Africa could be left looted unless the transition is deliberately designed to create value for the continent. This paradox defines our era.
Twenty years ago, the global resource governance movement transformed the conversation from one centered on extraction of resources to one focused on inclusive development through transparency, accountability and citizen participation. Organizations such as the Natural Resource Governance Institute (NRGI), together with governments, civil society and international partners, helped place accountability, transparency and better governance at the heart of resource management.
Today's challenge is different. Africa must not only govern its minerals better. It must negotiate its future better.
For more than three decades, the African Group of Negotiators (AGN) has helped shape international climate negotiations by advancing African priorities on adaptation, climate finance and Loss and Damage. COP32 now offers the opportunity to extend that leadership to one of the defining issues of this century: the governance and diplomacy of critical minerals.
Across the world, major economies are redesigning industrial strategies around secure mineral supply chains. The European Union's Critical Raw Materials Act, the United States-led Forum on Resource Geostrategic Engagement, China's International Economic and Trade Cooperation Initiative on Green Mining and Minerals and similar initiatives elsewhere reflect a profound geopolitical shift. Minerals are no longer simply commodities; they have become strategic assets.
Africa's greatest strategic asset is therefore not simply its mineral endowment. It is its collective bargaining power.
For too long, success has been measured by how many tons of minerals leave African ports. That is the wrong measure. Success should be judged by whether mineral wealth creates decent jobs, reliable energy systems, stronger public institutions, competitive industries, technological capability and lasting prosperity for African citizens.
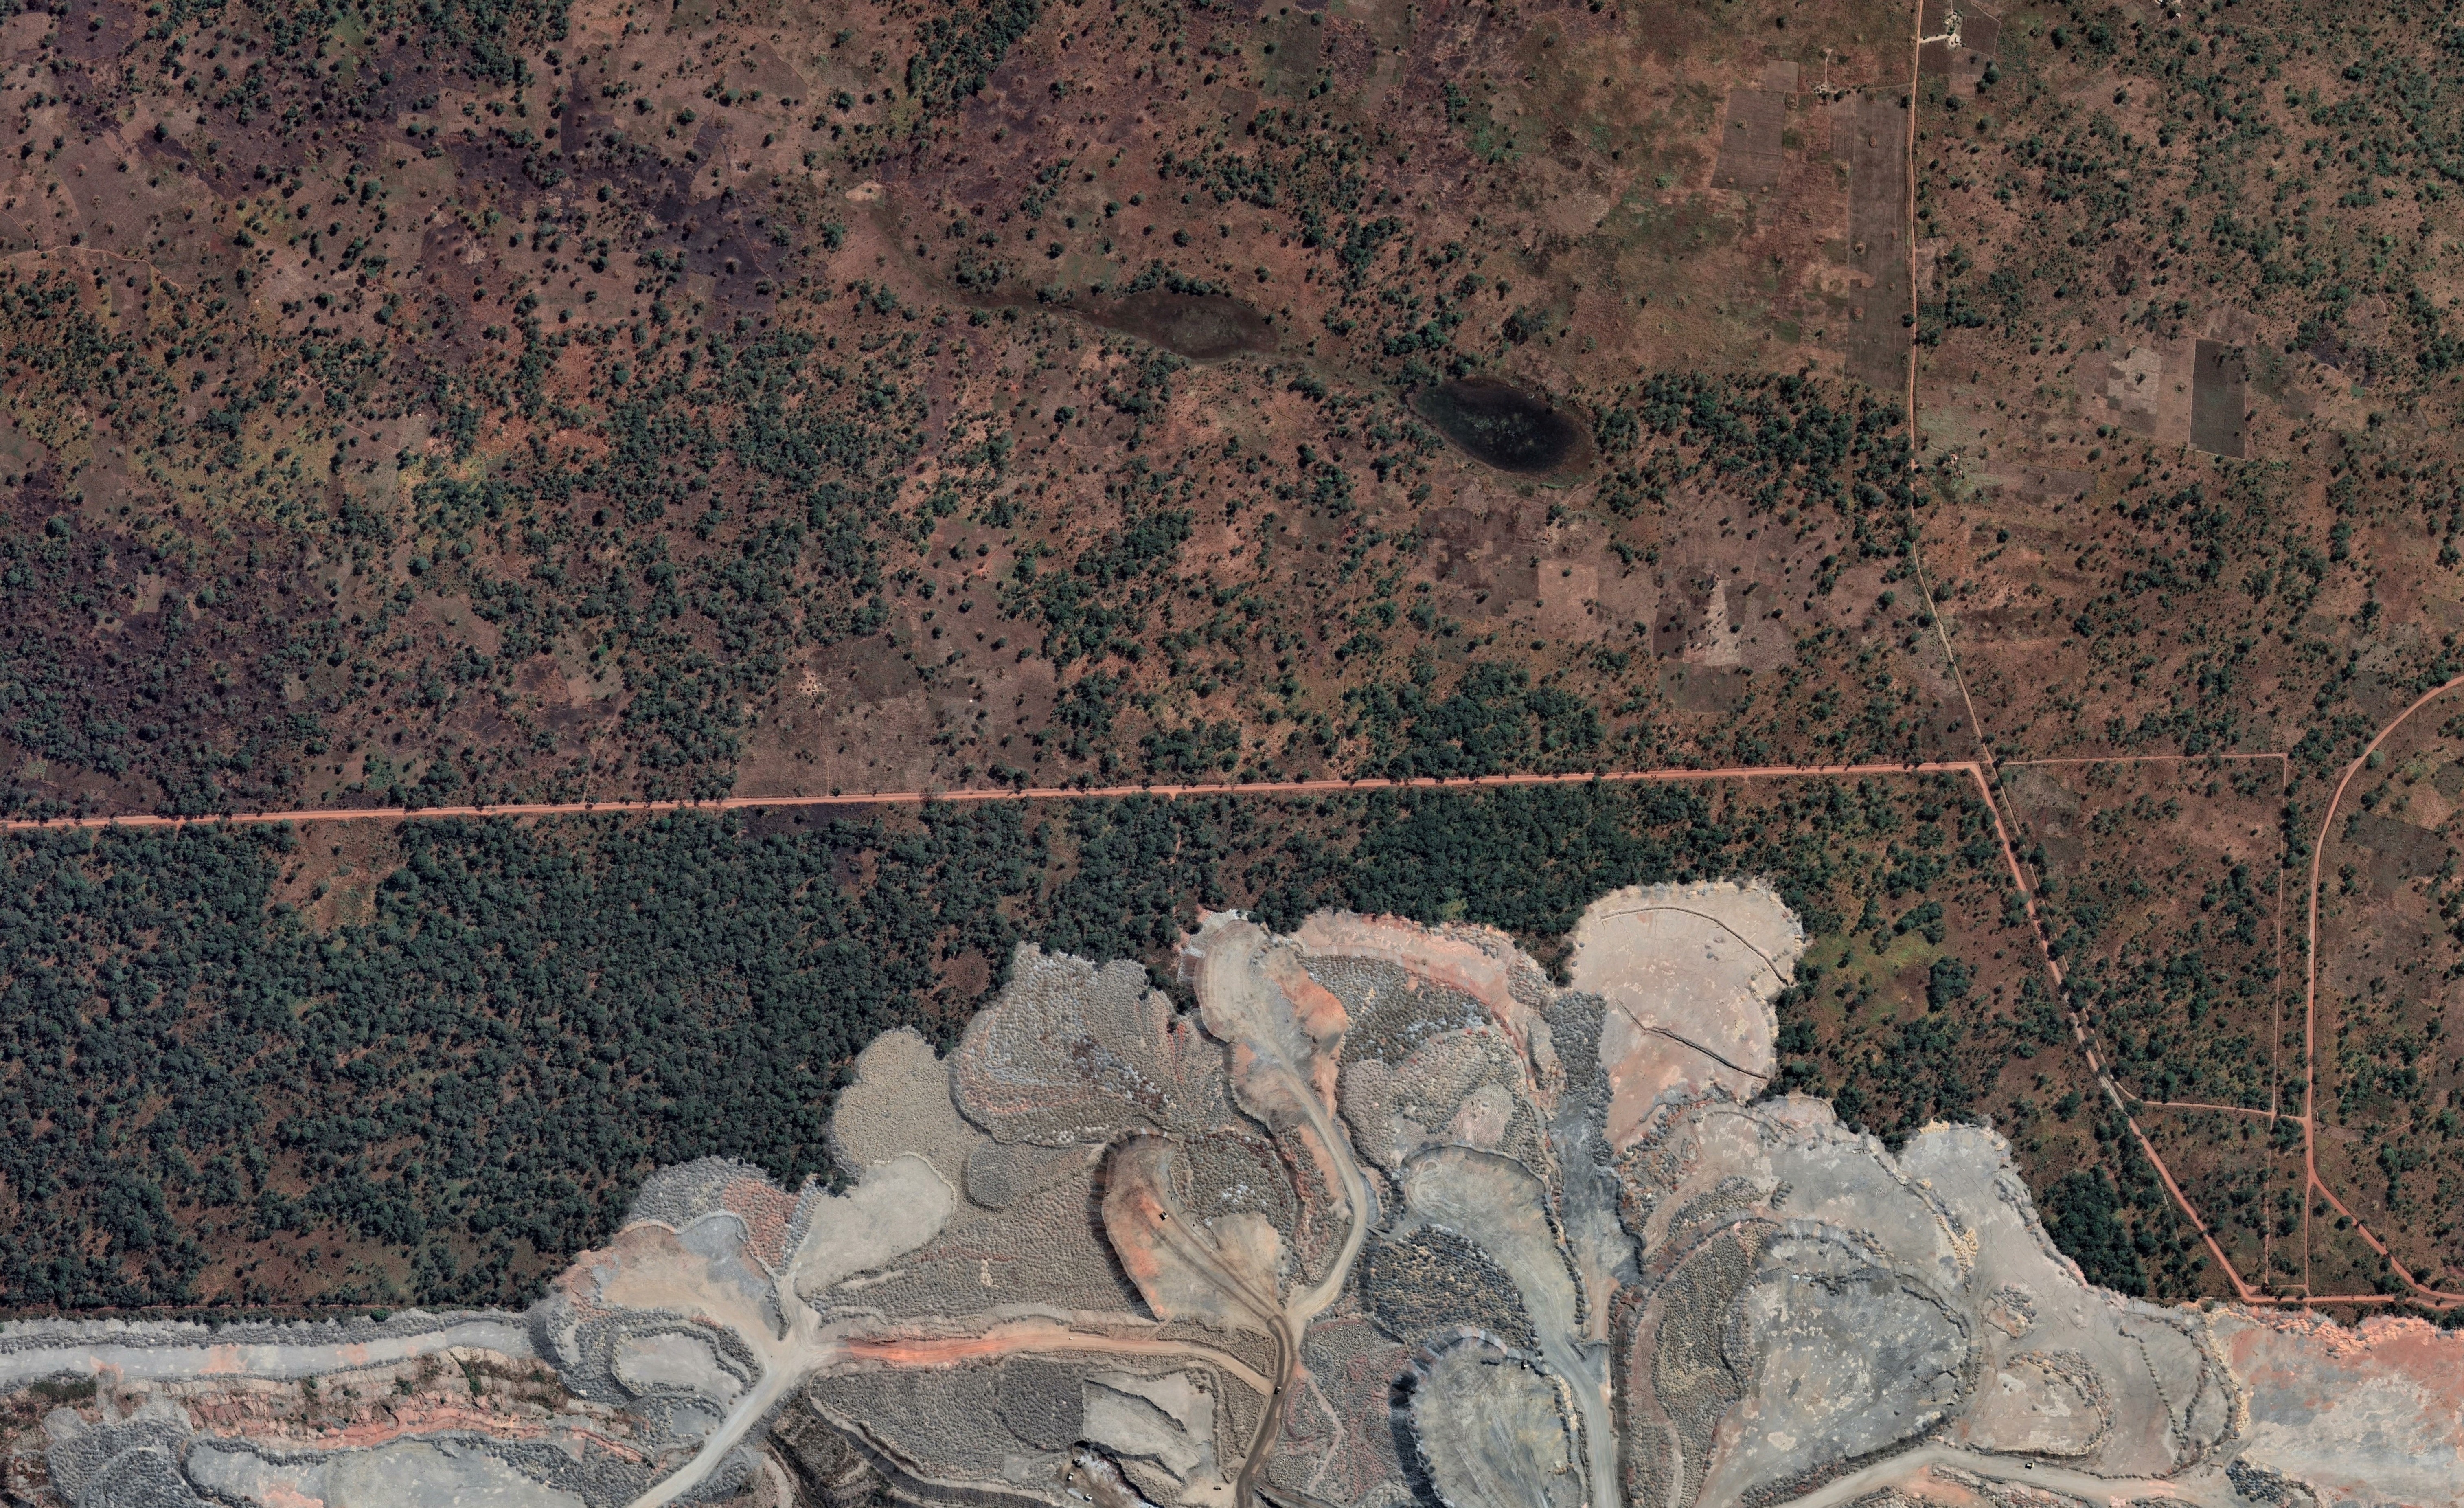
This requires a new generation of mineral diplomacy. Not diplomacy centered solely on concession agreements, but diplomacy that connects climate ambition with industrial policy, infrastructure investment, technology transfer, regional integration and economic resilience.
But better deals alone will not deliver transformation. Without transparent institutions, accountable governance and public trust, even the most ambitious mineral partnerships will fail to deliver on their promise.
History has shown that mineral booms can fuel corruption, environmental degradation, elite capture and community conflict when governance is weak. Conversely, countries with transparent licensing systems, contract disclosure, beneficial ownership transparency, sound fiscal management, environmental accountability and meaningful citizen participation are better positioned to attract responsible investment. This enables them to convert mineral wealth into long-term development.
Governance is the defining key in this regard. Strong governance strengthens investor confidence while ensuring that mineral wealth contributes to sustainable and inclusive development. So, good governance is not an obstacle to investment. It is one of its greatest competitive advantages. The challenge before Africa is not to choose between negotiating better partnerships and strengthening governance, but to recognize that the two are inseparable.
The meetings of the parties under the UNFCCC, usually referred to as COP, have often been criticized for being heavy on talk and light on implementation. We are determined that COP32 should be different. It presents an opportunity for Africa to champion an African Minerals and Just Transition Compact—a practical framework that aligns climate ambition with development ambition and builds on existing African Union frameworks, including Africa’s Green Minerals Strategy, to strengthen coherence and collective action. The Compact would establish a new partnership between producer and consumer countries rooted in good governance and based on shared prosperity rather than simple resource extraction.
We believe such a Compact should rest on four principles.
First, mineral partnerships should promote long-term economic transformation built on a clear, measurable ambition: by 2040, African countries should collectively double the share of value retained from their transition mineral resources. Estimates from the African Development Bank (AfDB) suggest that less than 20 percent of the total value of many mineral value chains is currently retained on the continent. Today, most African countries capture only a small fraction of the total value generated along mineral supply chains, often limited to royalties, taxes and low-value extraction activities, while the bulk of value accrues through processing, manufacturing and downstream industries located elsewhere. Doubling this share would thus require a more equitable capture of tax and fiscal revenues from mining, alongside harnessing increased value from processing and manufacturing. This in turn would depend on skills development, technology transfer, energy and infrastructure development and regional economic integration.
Second, Africa should focus on regional value chains instead of isolated national projects. By leveraging the African Continental Free Trade Area (AfCFTA), coordinated policies and strategic infrastructure, countries can collectively maximize the benefits of mineral development.
Third, climate and development finance must support mineral-producing economies in building productive capacity, not only in expanding extraction. Multilateral development banks (MDBs), climate funds and development partners should establish a dedicated facility, anchored in the MDB Joint Coordination Framework on Critical Minerals, with an initial capitalization of US$25 billion to provide concessional finance for geological data, renewable energy, transport corridors, industrial parks, research and innovation, governance reforms and workforce development. This figure reflects indicative estimates of the scale of investment required across priority areas, drawing on analyses by institutions such as the AfDB, IEA and World Bank on the infrastructure, industrial and governance investments needed to support mineral-based development.
Fourth, transparency, accountable institutions, contract disclosure, beneficial ownership, environmental stewardship and meaningful community participation must become defining features of responsible mineral partnerships.
To put this Compact into action, we will need to enter a new era of cooperation between producer and consumer countries. We believe there is momentum in this direction, and 2027 can be a turning point: leveraging the opportunities presented by African leadership of COP32 and UK leadership of the G20 to co-develop this new framework grounded in mutual accountability, local value creation and long-term economic transformation.
Remember, Africa does not seek to slow the global energy transition. On the contrary, our countries have contributed the least to climate change while experiencing some of its most severe impacts. Africa has every interest in seeing the transition succeed. But success cannot be measured only by the speed of global decarbonization. It must also be measured by whether the transition creates opportunity where the critical minerals originate. A fair and just transition is what Africa demands, and this Compact will help to deliver it.
Nana Dr. Antwi-Boasiako Amoah chairs the African Group of Negotiators (AGN) on Climate Change for 2026–2027, representing Africa's 54 countries in UN climate negotiations. He is Director of Adaptation, Climate Resilience and Risk Management at Ghana's Environmental Protection Authority and previously served as Lead Negotiator on National Adaptation Plans for the G77 and China. He also lectures part-time at the University of Ghana's Centre for Climate Change and Sustainability Studies. He contributed this piece as part of NRGI's 20th anniversary thought piece series on the future of resource governance.
Notes
-
1
Authors’ analysis based on “Greenhouse Gas Emissions from Energy Data Explorer”, International Energy Agency, 2 August 2023, www.iea.org/data-and-statistics/data-tools/greenhouse-gas-emissions-from-energy-data-explorer. And Hannah Ritchie, Max Roser, and Pablo Rosado, “CO₂ and Greenhouse Gas Emissions,” Our World in Data, 2020, ourworldindata.org/co2-and-greenhouse-gas-emissions.
-
2
Authors’ calculations based on Hannah Ritchie, Pablo Rosado, and Max Roser, “Greenhouse Gas Emissions,” Our World in Data, 2020. And “Oil and Natural Gas Supply,” IEA, 2022, www.iea.org/reports/oil-and-natural-gas-supply. Quoted in African Natural Resources Management and Investment Centre, Minimising Greenhouse Gas Emissions in the Petroleum Sector: The Opportunity for Emerging Producers (Abidjan, Côte d’Ivoire: African Development Bank, 2022), 14, www.newproducersgroup.online/wp-content/uploads/2022/11/Minimising-Greenhouse-Gas-Emissions-in-the-Petroleum-Sector.pdf.
-
3
In order to ensure greater international equity in the energy transition, authorities in countries implementing schemes such as the EU’s CBAM should include, in or alongside such schemes, measures to mitigate their negative effects on low and middle-income countries, e.g., through financial and/or technical assistance to help such countries green their economies.
-
4
Methane is a common by-product of oil extraction and a particularly potent greenhouse gas. In the process of getting oil and gas out of the ground, it is commonly emitted either through leaks or planned release into the atmosphere – either unburned (“venting”) or burned (“flaring”). Processing (e.g., refining) and transporting oil and gas also generate significant emissions. See “Methane from Oil and Gas Production Explained,” The World Bank - Global Gas Flaring Reduction Partnership, accessed 24 October 2023, www.worldbank.org/en/programs/gasflaringreduction/methane-explained.
-
5
The Global Registry of Fossil Fuels is an “[O]pen-source database of oil, gas and coal production and reserves globally, expressed in CO2-equivalent… It contains data from 139 fossil fuel producing countries, which amounts to 99% of fossil fuel production aggregated to the national level.” The database also provides estimates of the emissions from producing oil and gas in 91 oil producing countries and 71 gas producers. See “Global Registry of Fossil Fuel Emissions and Reserves”, Global Registry of Fossil Fuels, accessed 4 September 2023, fossilfuelregistry.org.
-
6
Figures 1 and 2 show a selection of countries, including some of the world’s larger oil producers, some of the world’s lower emitting producers as well as a selection of countries where NRGI operates. This is intended to provide reference points to explore whether individual countries will be more or less “carbon-competitive” than other producers based on current intensities and identifying potential examples of good practice among lower emitting producers. We also include a selection of higher-emitting producers, which may provide examples of practices to avoid.
-
7
Source: “Carbon Intensity in the Fossil Fuel Supply Chain”, Global Registry of Fossil Fuels, 2023, fossilfuelregistry.org/carbon-intensity. Global Warming Potential (GWP) 20 is applied to methane emissions; see “Methane and Climate Change,” IEA, accessed 4 September 2023, www.iea.org/reports/methane-tracker-2021/methane-and-climate-change. The impact would be smaller if we used Global Warming Potential 100. The impact over the next 20 years is important and sufficient to justify action on cutting upstream emissions (and using GWP 100 would fail to show this); this is why we have chosen to display GWP 20 in this figure and figure 2. For further discussion, see Janos Maté and David Kanter, “The Benefits of Basing Policies on the 20 Year GWP of HFCs” (Greenpeace, 2011), ozone.unep.org/system/files/documents/Benefits%20of%20Basing%20Policies%20on%2020%20GWP%20of%20HFCs.pdf.
-
8
The world’s largest oil producers are the United States (accounting for 21 percent of global production), Saudi Arabia (13 percent) and Russia (10 percent). See “Frequently Asked Questions (FAQs) - What Countries Are the Top Producers and Consumers of Oil?”, U.S. Energy Information Administration (EIA), 22 September 2023, www.eia.gov/tools/faqs/faq.php?id=709&t=6.
-
9
Source: “Carbon Intensity in the Fossil Fuel Supply Chain.”
-
10
The world’s largest (fossil) gas producers are the United States (accounting for 25 percent of production), Russia (17 percent) and Iran (6 percent). See “Natural Gas Production”, Enerdata World Energy & Climate Statistics - Yearbook 2023, accessed 4 September 2023, www.doi.org/yearbook.enerdata.net/natural-gas/world-natural-gas-production-statistics.html. And Statista Research Department, “Natural Gas Production Worldwide from 1998 to 2022”, Statista, 29 August 2023, www.statista.com/statistics/265344/total-global-natural-gas-production-since-1998.
-
11
RMI provides data on supply chain emissions by oil and gas project. See RMI, “Assessing Global Oil and Gas Emissions”, Oil Climate Index plus Gas, 2023, ociplus.rmi.org.
-
12
Some initiatives to capture methane emissions can have a positive net present value for companies. See Chantal Beck et al., “The Future of Oil and Gas Is Now: How Companies Can Decarbonize,” McKinsey & Company, 7 January 2020, www.mckinsey.com/industries/oil-and-gas/our-insights/the-future-is-now-how-oil-and-gas-companies-can-decarbonize.
-
13
Authors’ calculations based on Tomas de Oliveira Bredariol and Christophe McGlade, “Fossil Fuels,” IEA, 11 July 2023, www.iea.org/energy-system/fossil-fuels. And Tomas de Oliveira Bredariol and Christophe McGlade, “Gas Flaring,” IEA, accessed 15 September 2023, www.iea.org/energy-system/fossil-fuels/gas-flaring.
-
14
This is a 30 percent cut relative to 2020 levels.
-
15
Authors’ analysis based on Rebecca Schulz, Christophe McGlade, and Peter Zeniewski, “Putting Gas Flaring in the Spotlight,” IEA, 9 December 2020, www.iea.org/commentaries/putting-gas-flaring-in-the-spotlight. And “Nigeria,” The World Bank, June 2022, flaringventingregulations.worldbank.org/nigeria.
-
16
In 2022 Nigeria’s government “[I[ssued guidelines to support the elimination of routine gas flaring by 2030 and a 60 percent reduction in fugitive methane emissions by 2031.” “Methane Abatement,” IEA, accessed 2 October 2023, www.iea.org/energy-system/fossil-fuels/methane-abatement.
The Connective Fabric of Natural Resource Governance: Reflections from UNGA and Climate Week

Last week, a delegation from NRGI attended the UN General Assembly and Climate Week NYC. Below are our reflections from across more than 20 sessions, side events, our 20th anniversary convening and meetings, with partners from government, civil society, Indigenous Peoples, multilaterals, philanthropy and industry.
Natural resources rarely dominate the headlines at the UN General Assembly, yet they underpin almost every item on its agenda. Whether conversations centered on climate, economic development, trade or geopolitics, the governance of oil, gas and minerals ran through many of them.
That role, however, too often remains implicit. Elevating resource governance as a priority is essential if global efforts on climate, development and security are to deliver equitable outcomes for producer countries and their citizens, and a healthy, sustainable future for all of us.
Security and trade have reframed the journey, but not the destination
Energy security has displaced energy transition as the dominant lens for energy policy, with decisions increasingly driven by geopolitics and cost of living rather than decarbonization. While the end goal of sustainable energy and economic futures remains, this marks a structural shift in the narratives that shape policy and in how influence is exercised.
In the minerals sector, a trade lens now dominates, even during a “Climate Week”. Green industrialization was a central theme, welcomed by some and viewed with skepticism by others. At a UN-hosted Solutions Dialogue on the subject, producer countries, particularly those from Africa, stressed that high costs of capital and limited fiscal space must not constrain their economic and trade ambitions. African participants were clear that the gap is now implementation, not strategy: frameworks such as the African Mining Vision and the Africa Green Minerals Strategy already exist. Because no single country holds every mineral, energy source, skill and market, enabling countries to achieve more value requires regional integration. The African Continental Free Trade Area (AfCFTA) serving as an industrial platform rather than only a trade agreement. Success, many argued, should be measured by the jobs, skills and productive capabilities retained on the continent, not by processing capacity alone. In our remarks, NRGI emphasized the need for additional financing and technical support so that producer countries can design, implement and monitor value addition and diversification strategies that truly meet the needs of their people, and enforce high human rights, environmental and governance standards.
Green industrialization could serve as a bridge that brings mineral trade and climate policy closer together. We are looking forward to further progress at COP31 in November, as green industrialization is a key priority on the Action Agenda launched by Türkiye last week. Looking to next year, NRGI is also supporting a shared agenda on equitable mineral partnerships across the COP32 and UK-led G20 processes, where African countries have an opportunity to connect their climate positions with their leverage as producers of critical minerals.
"Critical for who?": equity and the governance gap
With “critical minerals” being used so often, the question "critical for who?" recurred throughout. Across discussions, there was a unifying call for a new and more equitable economic and political paradigm, but how this plays out in practice remains highly uncertain. There were multiple calls (including from NRGI) for critical minerals to underpin just, country-led transitions that serve producer countries' development aspirations, respect the free, prior and informed consent of Indigenous Peoples and frontline communities, and remedy legacy environmental harms. Several sessions went further, asking not just how much revenue extraction generates but whether it preserves national wealth across generations. Without this, producer countries risk exchanging finite mineral wealth for limited revenues while leaving depleted assets and environmental damage to future generations.
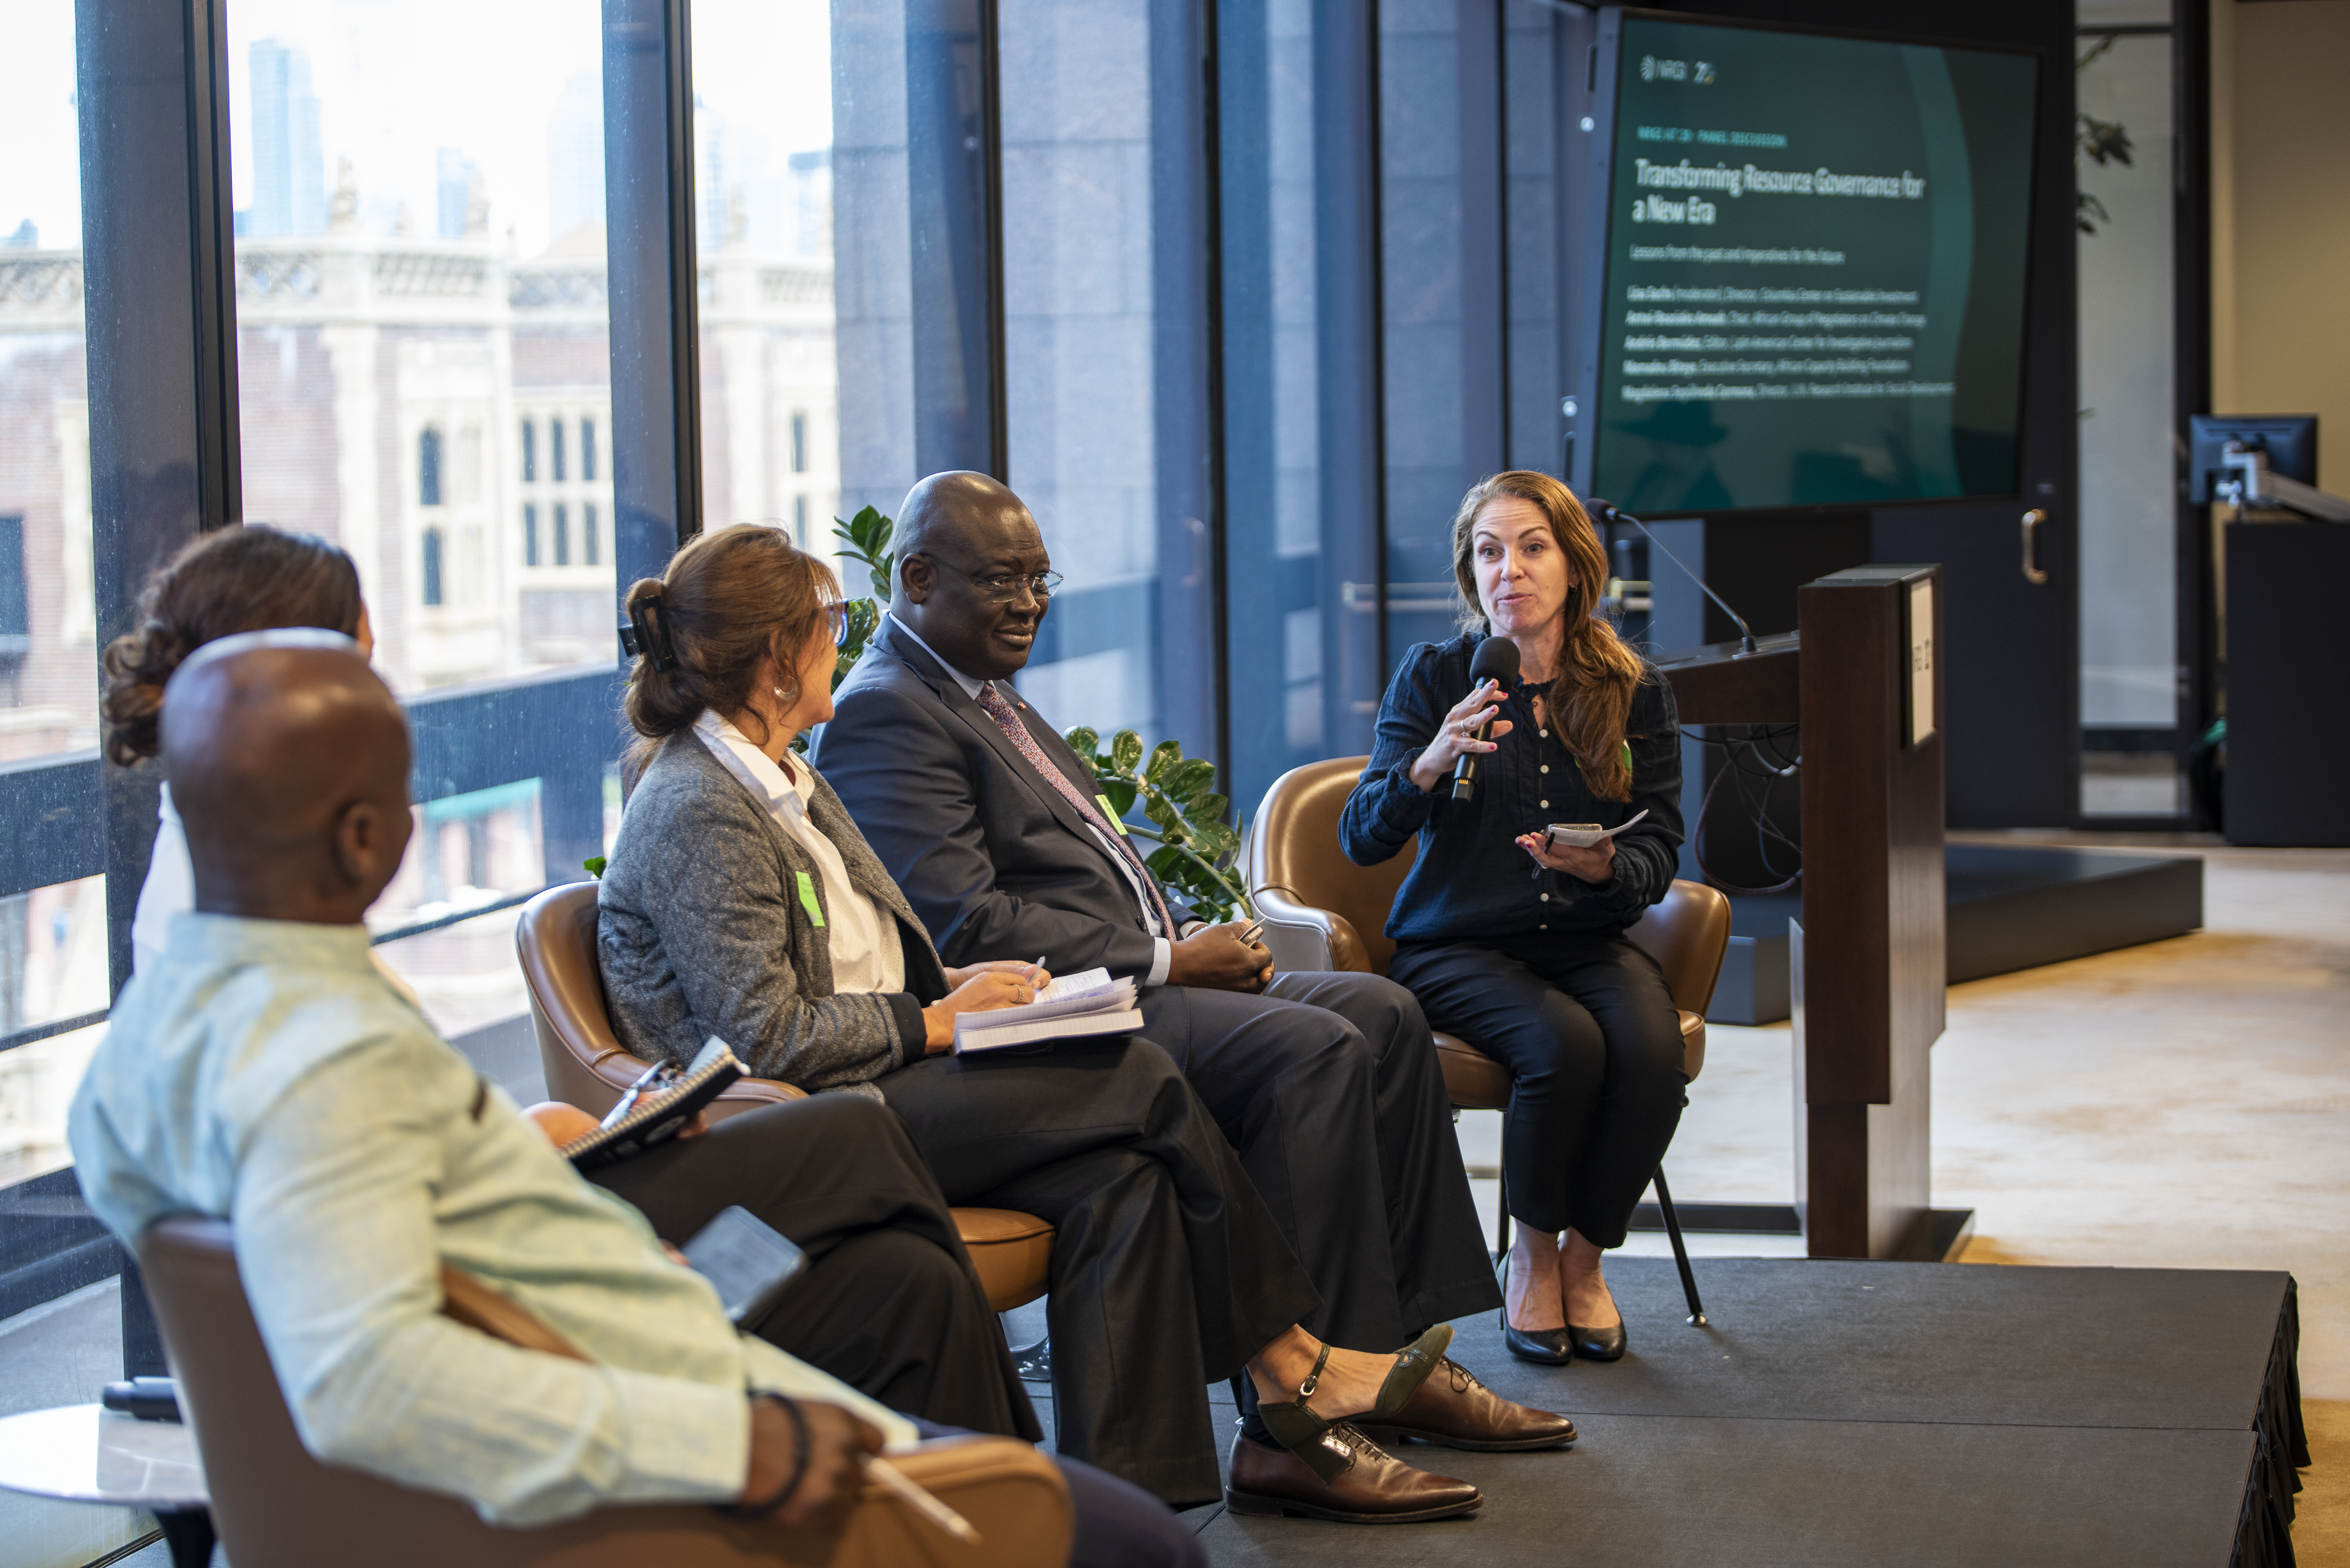
While critical minerals are the focus, the obstacles to fairer and more prosperous societies are structural and systemic – a theme that echoed throughout including in NRGI’s 20th anniversary event. Low- and middle-income countries remain underrepresented in setting new standards and paradigms, despite bearing their costs.
Encouragingly, the discussion has moved from what must change to how. Reformers shared approaches ranging from multi-stakeholder engagement and narrative storytelling to strategic litigation, the quantification of decommissioning liabilities and evidence on the financial materiality of community engagement. Each aims to ensure that community rights are respected and that polluters remediate the harm they cause. A recurring message was that affected communities need agency, not simply better consultation: access to information, the capacity to negotiate and the ability to speak for themselves with governments, companies, investors and financiers. These “unbankable” elements often determine whether supposedly bankable investments succeed.
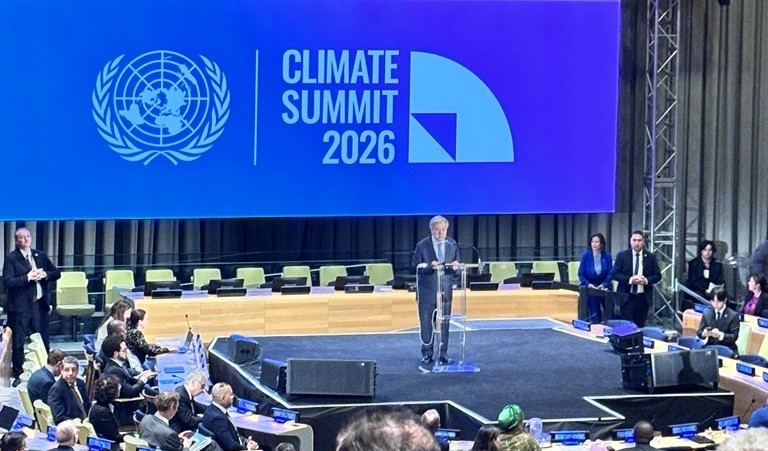
Concrete openings exist to keep making progress. At the UN Climate Summit, the Secretary-General announced a new country support mechanism for six mineral-rich developing countries to implement the recommendations of the UN Secretary-General's Panel on Critical Energy Transition Minerals. Having served on the panel, NRGI and our partners have pressed for this follow-through, including in this joint letter last July. We welcome the mechanism. Connecting with technical assistance partners outside the UN to deliver tailored, demand-led support will be critical to its success. (Learn more: See our video and press statement released during the week). The push for an International Panel on Inequality and next year’s planned SDG Summit offer further entry points to center producer countries in debates on the future economy. The ongoing review of the IFC Performance Standards is another, as these standards shape the practices of commercial banks, export-credit agencies and mining companies well beyond the IFC itself.
Artificial intelligence and the resources beneath it
Some described this as the "AI UNGA". Technology leaders addressed the Security Council, many world leaders mentioned AI in their speeches, and there were countless AI-focused side events. Yet beyond limited discussion focused on data centers, few conversations linked AI development to the minerals that build and power it. This is a gap that policymakers, companies and civil society alike must close.
A notable exception was a discussion convened by the government of the Democratic Republic of the Congo, entitled “AI and the New Geopolitics of Peace and Security”, in which NRGI participated. It followed a July Arria-formula meeting, held during the DRC's Security Council presidency, which called for a global normative framework reconciling peace, security, transparency and sustainable development. NRGI has provided technical input to that process, and this intersection is emerging as a key policy space.
The DRC's leadership is itself both noteworthy and an opportunity. It shows how low- and middle-income countries can shape emerging global norms on minerals, security and AI, rather than simply adopt rules set elsewhere.
A fragmented landscape demands trusted brokers
While emerging coalitions and new opportunities are being born of the current upheaval, fragmentation and polarization remain a challenge. Progress will depend on trusted brokers who can navigate contradictions to unite diverse groups, and on building new, action-focused coalitions.
For NRGI, we see this as a challenge and an opportunity. We will seek to leverage the trust, credibility and knowledge we have built over two decades, while holding a nuanced, independent position in a multi-polar world.
Notes
-
1
Authors’ analysis based on “Greenhouse Gas Emissions from Energy Data Explorer”, International Energy Agency, 2 August 2023, www.iea.org/data-and-statistics/data-tools/greenhouse-gas-emissions-from-energy-data-explorer. And Hannah Ritchie, Max Roser, and Pablo Rosado, “CO₂ and Greenhouse Gas Emissions,” Our World in Data, 2020, ourworldindata.org/co2-and-greenhouse-gas-emissions.
-
2
Authors’ calculations based on Hannah Ritchie, Pablo Rosado, and Max Roser, “Greenhouse Gas Emissions,” Our World in Data, 2020. And “Oil and Natural Gas Supply,” IEA, 2022, www.iea.org/reports/oil-and-natural-gas-supply. Quoted in African Natural Resources Management and Investment Centre, Minimising Greenhouse Gas Emissions in the Petroleum Sector: The Opportunity for Emerging Producers (Abidjan, Côte d’Ivoire: African Development Bank, 2022), 14, www.newproducersgroup.online/wp-content/uploads/2022/11/Minimising-Greenhouse-Gas-Emissions-in-the-Petroleum-Sector.pdf.
-
3
In order to ensure greater international equity in the energy transition, authorities in countries implementing schemes such as the EU’s CBAM should include, in or alongside such schemes, measures to mitigate their negative effects on low and middle-income countries, e.g., through financial and/or technical assistance to help such countries green their economies.
-
4
Methane is a common by-product of oil extraction and a particularly potent greenhouse gas. In the process of getting oil and gas out of the ground, it is commonly emitted either through leaks or planned release into the atmosphere – either unburned (“venting”) or burned (“flaring”). Processing (e.g., refining) and transporting oil and gas also generate significant emissions. See “Methane from Oil and Gas Production Explained,” The World Bank - Global Gas Flaring Reduction Partnership, accessed 24 October 2023, www.worldbank.org/en/programs/gasflaringreduction/methane-explained.
-
5
The Global Registry of Fossil Fuels is an “[O]pen-source database of oil, gas and coal production and reserves globally, expressed in CO2-equivalent… It contains data from 139 fossil fuel producing countries, which amounts to 99% of fossil fuel production aggregated to the national level.” The database also provides estimates of the emissions from producing oil and gas in 91 oil producing countries and 71 gas producers. See “Global Registry of Fossil Fuel Emissions and Reserves”, Global Registry of Fossil Fuels, accessed 4 September 2023, fossilfuelregistry.org.
-
6
Figures 1 and 2 show a selection of countries, including some of the world’s larger oil producers, some of the world’s lower emitting producers as well as a selection of countries where NRGI operates. This is intended to provide reference points to explore whether individual countries will be more or less “carbon-competitive” than other producers based on current intensities and identifying potential examples of good practice among lower emitting producers. We also include a selection of higher-emitting producers, which may provide examples of practices to avoid.
-
7
Source: “Carbon Intensity in the Fossil Fuel Supply Chain”, Global Registry of Fossil Fuels, 2023, fossilfuelregistry.org/carbon-intensity. Global Warming Potential (GWP) 20 is applied to methane emissions; see “Methane and Climate Change,” IEA, accessed 4 September 2023, www.iea.org/reports/methane-tracker-2021/methane-and-climate-change. The impact would be smaller if we used Global Warming Potential 100. The impact over the next 20 years is important and sufficient to justify action on cutting upstream emissions (and using GWP 100 would fail to show this); this is why we have chosen to display GWP 20 in this figure and figure 2. For further discussion, see Janos Maté and David Kanter, “The Benefits of Basing Policies on the 20 Year GWP of HFCs” (Greenpeace, 2011), ozone.unep.org/system/files/documents/Benefits%20of%20Basing%20Policies%20on%2020%20GWP%20of%20HFCs.pdf.
-
8
The world’s largest oil producers are the United States (accounting for 21 percent of global production), Saudi Arabia (13 percent) and Russia (10 percent). See “Frequently Asked Questions (FAQs) - What Countries Are the Top Producers and Consumers of Oil?”, U.S. Energy Information Administration (EIA), 22 September 2023, www.eia.gov/tools/faqs/faq.php?id=709&t=6.
-
9
Source: “Carbon Intensity in the Fossil Fuel Supply Chain.”
-
10
The world’s largest (fossil) gas producers are the United States (accounting for 25 percent of production), Russia (17 percent) and Iran (6 percent). See “Natural Gas Production”, Enerdata World Energy & Climate Statistics - Yearbook 2023, accessed 4 September 2023, www.doi.org/yearbook.enerdata.net/natural-gas/world-natural-gas-production-statistics.html. And Statista Research Department, “Natural Gas Production Worldwide from 1998 to 2022”, Statista, 29 August 2023, www.statista.com/statistics/265344/total-global-natural-gas-production-since-1998.
-
11
RMI provides data on supply chain emissions by oil and gas project. See RMI, “Assessing Global Oil and Gas Emissions”, Oil Climate Index plus Gas, 2023, ociplus.rmi.org.
-
12
Some initiatives to capture methane emissions can have a positive net present value for companies. See Chantal Beck et al., “The Future of Oil and Gas Is Now: How Companies Can Decarbonize,” McKinsey & Company, 7 January 2020, www.mckinsey.com/industries/oil-and-gas/our-insights/the-future-is-now-how-oil-and-gas-companies-can-decarbonize.
-
13
Authors’ calculations based on Tomas de Oliveira Bredariol and Christophe McGlade, “Fossil Fuels,” IEA, 11 July 2023, www.iea.org/energy-system/fossil-fuels. And Tomas de Oliveira Bredariol and Christophe McGlade, “Gas Flaring,” IEA, accessed 15 September 2023, www.iea.org/energy-system/fossil-fuels/gas-flaring.
-
14
This is a 30 percent cut relative to 2020 levels.
-
15
Authors’ analysis based on Rebecca Schulz, Christophe McGlade, and Peter Zeniewski, “Putting Gas Flaring in the Spotlight,” IEA, 9 December 2020, www.iea.org/commentaries/putting-gas-flaring-in-the-spotlight. And “Nigeria,” The World Bank, June 2022, flaringventingregulations.worldbank.org/nigeria.
-
16
In 2022 Nigeria’s government “[I[ssued guidelines to support the elimination of routine gas flaring by 2030 and a 60 percent reduction in fugitive methane emissions by 2031.” “Methane Abatement,” IEA, accessed 2 October 2023, www.iea.org/energy-system/fossil-fuels/methane-abatement.
Just Transition or Just Hesitation? Why Africa Must Stop Negotiating with Fear

As the global energy transition accelerates, Benjamin Boakye, Executive Director of the Africa Center for Energy Policy (ACEP), argues that Africa must stop negotiating from a place of fear, and instead focus on proactively building the capacity to compete, adapt and prosper.
The global energy transition has become one of the defining policy debates of our generation. Across Africa, it has generated both optimism and anxiety. For oil producing countries, the concern is understandable. Most long-term energy outlooks project that global demand for fossil fuels will gradually decline over the coming decades, creating fiscal risks for economies that remain heavily dependent on petroleum revenues. For countries endowed with critical minerals, the transition presents a different prospect: unprecedented opportunities to participate in the value chains that will power a low carbon economy.
Both realities deserve serious attention. Yet the greatest risk facing Africa is neither the projected decline in fossil fuel demand nor the volatility of mineral markets. It is the continent’s growing tendency to define its future through narratives developed out of frustration and fear to respond to global power imbalances instead of pursuing practical strategies rooted in African realities, ambitions and capabilities.
Much of Africa’s transition conversation has become an exercise in interpreting what Europe, North America and other advanced economies think Africa’s role should be in a decarbonizing world. Policymakers devote considerable effort to responding to external debates about climate justice, fossil fuel phase out pathways and financing obligations. While these discussions matter, they increasingly distract governments from the more urgent task of positioning their economies to benefit from one of the greatest industrial transformations in modern history happening with a complex interplay of innovation, geopolitics, energy security and a race to economic heights imminent in the foreseeable future.
The result is a discourse dominated by vulnerability.
Africa is vulnerable because it contributes only a small share of global greenhouse gas emissions yet bears a disproportionate burden of climate impacts. Many of its economies also remain dependent on commodity exports, constrained by limited access to capital and technology, and characterized by relatively weak industrial capacity. The challenge is not that these concerns are misplaced. They are real and deserve serious attention. The challenge is that they have come to dominate the conversation. Too much of Africa’s transition discourse now revolves around managing vulnerability rather than building capability, responding to global climate conversations with narratives of weakness rather than defining an African strategy for competing in a changing global economy. The question is not whether Africa is vulnerable, but whether it chooses to organize its response around vulnerability or around capability.
Complaints may be justified. They are not a development strategy.
A just transition for Africa should therefore not be defined primarily by compensation for losses or fairness in international negotiations. Those debates have their place, but they should not become the organising principle of Africa’s response. A just transition should instead be judged by whether African countries build the institutions, skills and industries needed to create value from the changing global economy. This will help to properly align every support beyond the continent to deliver targeted outcomes.
For oil producing countries in Africa, this requires technical honesty. Governments should recognize that while global oil demand has not yet entered sustained decline, many long-term energy outlooks, including those of the International Energy Agency, project that fossil fuel demand will gradually weaken over time, although the pace and timing remain uncertain. This creates genuine fiscal risks for countries whose public finances depend heavily on petroleum revenues.
The response, however, is neither panic nor the premature abandonment of petroleum resources. Africa must approach its resource development decisions with a deep appreciation of the uncertainty and emerging economic realities shaping competing energy forms. Equally, governments cannot continue planning as though the future will resemble the past. The real challenge is using today’s petroleum revenues to finance tomorrow’s diversified economy.
Countries such as Ghana, Nigeria and Angola should therefore focus on strengthening fiscal management, investing in human capital, improving public institutions and accelerating economic diversification. The question is not whether demand will eventually decline, but whether these countries will use the remaining window of opportunity wisely.
Mineral rich countries across the continent face a different, but equally demanding, challenge. The growing demand for lithium, cobalt, graphite, manganese and rare earth elements presents Africa with a rare opportunity to capture greater value from the global energy transition. Yet mineral wealth has never guaranteed prosperity. For decades, African economies have exported raw materials while importing technology, manufactured goods and jobs. Without deliberate, analytically grounded policies that identify commercially viable opportunities for value addition and industrialisation, the transition minerals boom could simply reproduce the extractive model under a different name. The measure of success will not be how much Africa extracts, but how much value it creates.
Africa’s opportunity extends well beyond mining. The continent’s abundant renewable energy resources, young workforce and expanding technological capabilities provide a strong foundation for industrialization, manufacturing and innovation. With strategic investments and coherent industrial policies, these assets can generate far greater economic value than exporting raw minerals alone.
This requires preparation rather than optimism.
Preparation begins with technical honesty. Governments must resist the temptation to build policy around fashionable narratives or political slogans. Not every country will become a battery manufacturing hub. Not every mineral deposit justifies domestic processing. Effective policy demands realistic assessments of comparative advantage, market conditions and institutional capability.
Strategic partnerships are equally essential. Too often, international engagement is framed as a choice between sovereignty and dependence. This is a false dichotomy. Virtually every successful industrial transformation, from East Asia to more recent experiences in Southeast Asia, has relied on strategic partnerships that mobilized capital, transferred technology, developed skills and expanded access to global markets. Africa should therefore pursue partnerships that strengthen domestic capabilities while remaining firmly aligned with its own development priorities.
Urgency is equally important.
The transition is already underway. Investment decisions are being made, supply chains are being reconfigured and new technologies are being deployed at scale. Every year spent dwelling on whether the transition is fair is another year in which others strengthen their competitive advantage while Africa delays positioning itself to benefit.
The greatest danger, therefore, is not the transition itself. It is hesitation.
The future of resource governance should not be framed around what the world owes Africa. It should be framed around what Africa owes itself: disciplined planning, technical honesty, capable institutions, strategic partnerships and sustained investment in its people.
A just transition is not achieved by dwelling on vulnerability or waiting for perfect global fairness. It is achieved by building the capacity to compete, adapt and prosper. The choice before Africa is therefore miles beyond fairness. It is whether the continent will spend the next decade negotiating from a position of fear or preparing from a position of confidence and optimizing its space and people.
The window of opportunity remains open, but it will not remain open indefinitely.
Benjamin Boakye is the Executive Director of the Africa Center for Energy Policy (ACEP), a leading African think tank on energy and extractive sector governance. He has over 15 years of experience advising governments, development partners and civil society on energy governance, the energy transition and natural resource management. His work focuses on advancing policies that strengthen economic transformation and sustainable development across Africa. He contributed this piece as part of NRGI's 20th anniversary thought piece series on the future of resource governance.
Notes
-
1
Authors’ analysis based on “Greenhouse Gas Emissions from Energy Data Explorer”, International Energy Agency, 2 August 2023, www.iea.org/data-and-statistics/data-tools/greenhouse-gas-emissions-from-energy-data-explorer. And Hannah Ritchie, Max Roser, and Pablo Rosado, “CO₂ and Greenhouse Gas Emissions,” Our World in Data, 2020, ourworldindata.org/co2-and-greenhouse-gas-emissions.
-
2
Authors’ calculations based on Hannah Ritchie, Pablo Rosado, and Max Roser, “Greenhouse Gas Emissions,” Our World in Data, 2020. And “Oil and Natural Gas Supply,” IEA, 2022, www.iea.org/reports/oil-and-natural-gas-supply. Quoted in African Natural Resources Management and Investment Centre, Minimising Greenhouse Gas Emissions in the Petroleum Sector: The Opportunity for Emerging Producers (Abidjan, Côte d’Ivoire: African Development Bank, 2022), 14, www.newproducersgroup.online/wp-content/uploads/2022/11/Minimising-Greenhouse-Gas-Emissions-in-the-Petroleum-Sector.pdf.
-
3
In order to ensure greater international equity in the energy transition, authorities in countries implementing schemes such as the EU’s CBAM should include, in or alongside such schemes, measures to mitigate their negative effects on low and middle-income countries, e.g., through financial and/or technical assistance to help such countries green their economies.
-
4
Methane is a common by-product of oil extraction and a particularly potent greenhouse gas. In the process of getting oil and gas out of the ground, it is commonly emitted either through leaks or planned release into the atmosphere – either unburned (“venting”) or burned (“flaring”). Processing (e.g., refining) and transporting oil and gas also generate significant emissions. See “Methane from Oil and Gas Production Explained,” The World Bank - Global Gas Flaring Reduction Partnership, accessed 24 October 2023, www.worldbank.org/en/programs/gasflaringreduction/methane-explained.
-
5
The Global Registry of Fossil Fuels is an “[O]pen-source database of oil, gas and coal production and reserves globally, expressed in CO2-equivalent… It contains data from 139 fossil fuel producing countries, which amounts to 99% of fossil fuel production aggregated to the national level.” The database also provides estimates of the emissions from producing oil and gas in 91 oil producing countries and 71 gas producers. See “Global Registry of Fossil Fuel Emissions and Reserves”, Global Registry of Fossil Fuels, accessed 4 September 2023, fossilfuelregistry.org.
-
6
Figures 1 and 2 show a selection of countries, including some of the world’s larger oil producers, some of the world’s lower emitting producers as well as a selection of countries where NRGI operates. This is intended to provide reference points to explore whether individual countries will be more or less “carbon-competitive” than other producers based on current intensities and identifying potential examples of good practice among lower emitting producers. We also include a selection of higher-emitting producers, which may provide examples of practices to avoid.
-
7
Source: “Carbon Intensity in the Fossil Fuel Supply Chain”, Global Registry of Fossil Fuels, 2023, fossilfuelregistry.org/carbon-intensity. Global Warming Potential (GWP) 20 is applied to methane emissions; see “Methane and Climate Change,” IEA, accessed 4 September 2023, www.iea.org/reports/methane-tracker-2021/methane-and-climate-change. The impact would be smaller if we used Global Warming Potential 100. The impact over the next 20 years is important and sufficient to justify action on cutting upstream emissions (and using GWP 100 would fail to show this); this is why we have chosen to display GWP 20 in this figure and figure 2. For further discussion, see Janos Maté and David Kanter, “The Benefits of Basing Policies on the 20 Year GWP of HFCs” (Greenpeace, 2011), ozone.unep.org/system/files/documents/Benefits%20of%20Basing%20Policies%20on%2020%20GWP%20of%20HFCs.pdf.
-
8
The world’s largest oil producers are the United States (accounting for 21 percent of global production), Saudi Arabia (13 percent) and Russia (10 percent). See “Frequently Asked Questions (FAQs) - What Countries Are the Top Producers and Consumers of Oil?”, U.S. Energy Information Administration (EIA), 22 September 2023, www.eia.gov/tools/faqs/faq.php?id=709&t=6.
-
9
Source: “Carbon Intensity in the Fossil Fuel Supply Chain.”
-
10
The world’s largest (fossil) gas producers are the United States (accounting for 25 percent of production), Russia (17 percent) and Iran (6 percent). See “Natural Gas Production”, Enerdata World Energy & Climate Statistics - Yearbook 2023, accessed 4 September 2023, www.doi.org/yearbook.enerdata.net/natural-gas/world-natural-gas-production-statistics.html. And Statista Research Department, “Natural Gas Production Worldwide from 1998 to 2022”, Statista, 29 August 2023, www.statista.com/statistics/265344/total-global-natural-gas-production-since-1998.
-
11
RMI provides data on supply chain emissions by oil and gas project. See RMI, “Assessing Global Oil and Gas Emissions”, Oil Climate Index plus Gas, 2023, ociplus.rmi.org.
-
12
Some initiatives to capture methane emissions can have a positive net present value for companies. See Chantal Beck et al., “The Future of Oil and Gas Is Now: How Companies Can Decarbonize,” McKinsey & Company, 7 January 2020, www.mckinsey.com/industries/oil-and-gas/our-insights/the-future-is-now-how-oil-and-gas-companies-can-decarbonize.
-
13
Authors’ calculations based on Tomas de Oliveira Bredariol and Christophe McGlade, “Fossil Fuels,” IEA, 11 July 2023, www.iea.org/energy-system/fossil-fuels. And Tomas de Oliveira Bredariol and Christophe McGlade, “Gas Flaring,” IEA, accessed 15 September 2023, www.iea.org/energy-system/fossil-fuels/gas-flaring.
-
14
This is a 30 percent cut relative to 2020 levels.
-
15
Authors’ analysis based on Rebecca Schulz, Christophe McGlade, and Peter Zeniewski, “Putting Gas Flaring in the Spotlight,” IEA, 9 December 2020, www.iea.org/commentaries/putting-gas-flaring-in-the-spotlight. And “Nigeria,” The World Bank, June 2022, flaringventingregulations.worldbank.org/nigeria.
-
16
In 2022 Nigeria’s government “[I[ssued guidelines to support the elimination of routine gas flaring by 2030 and a 60 percent reduction in fugitive methane emissions by 2031.” “Methane Abatement,” IEA, accessed 2 October 2023, www.iea.org/energy-system/fossil-fuels/methane-abatement.
Extracting Emissions: Why Resource-Rich Countries Should Cut Emissions from Extractive Operations

-
Global efforts to mitigate climate change are likely to greatly reduce demand for fossil fuels over time. Countries that depend on revenues from these resources should diversify their economies.
-
Investors and customers are pressuring the oil, gas and mining industries to cut greenhouse gas emissions from their production processes. This trend is likely to intensify, including with new policies from key trading partners seeking to reduce greenhouse gas emissions from the extractive commodities that they import. Examples of such measures include the European Union’s Carbon Border Adjustment Mechanism and its regulations on methane emissions from oil, gas and coal operations.
-
To stay competitive, governments of resource-rich countries will need to cut emissions from oil, gas and mining operations in their territories. Some are already doing this. But progress has been slow, and much work remains. To improve results, a wider set of stakeholders than just governments and including civil society actors should engage on the issue and seek increased transparency and accountability on emissions from the extractive industries.
Introduction
On 1 October 2023, the European Union launched the transitional phase of its “Carbon Border Adjustment Mechanism” (CBAM) through which the EU will tax products of the most polluting industries coming into the EU in proportion to greenhouse gas emissions involved in their manufacture. While the CBAM doesn’t yet apply to raw extractive commodities, it does apply to processed metals and mineral products such as aluminum, cement, fertilizer, iron and steel. And the EU is considering extending the CBAM to cover metals more broadly and refined oil by 2030.
The CBAM’s introduction, as well as the EU’s recent announcement that it will regulate methane emissions from oil, gas and coal operations (including in non-EU countries that export to the bloc), is part of a growing trend whereby investors, downstream industries and governments of resource-importing countries pressure the oil, gas and mining sectors to cut emissions from their operations. Here we analyze this trend and how resource-rich countries can respond to it.
We find that countries producing the extractive commodities that pollute the most (whether from extraction, supply chains or final consumption) will find it increasingly difficult to be competitive as the world prioritizes lower-emission varieties. Governments in such countries should therefore analyze emissions from their countries’ extractive operations. Moreover, officials should a) take this into account when deciding whether to invest further public financial resources in these industries given likelihood of decreased demand for high-emission commodities, and b) cut emissions from the production process as this will be an important factor in the economics of extraction going forward.
Climate change mitigation and resource-rich countries’ economic models
The extractive industries and the commodities that they produce are the main contributors to climate change. The use of mined products, especially the burning of coal, including by the extractive industries themselves, accounts for 28 percent of global greenhouse gas emissions; and burning oil and gas accounts for around 33 percent of total emissions.1
Cutting the use of fossil fuels is therefore essential to fighting climate change and efforts to do so will likely have major impacts on fossil fuel producing countries in the medium to long term. If countries follow through on pledges to cut greenhouse gas emissions, this will mean that oil, gas and coal demand will fall, posing problems for resource-rich countries where economic models depend on the production of fossil fuels. Indeed, many analysts think that global oil demand has already peaked. These dynamics make it imperative for fossil fuel producing countries to diversify their economies.
But demand for and production of fossil fuels is not disappearing overnight, and their climate impact is not limited to their end use. Producing, processing and transporting oil and gas (i.e., the sector’s scope 1 and 2 emissions) accounts for 10-13 percent of worldwide greenhouse gas emissions2 (compared to 2-3 percent from mining). Fossil fuel producers are therefore also under pressure to cut emissions from the production and supply of fossil fuels.
What are scope 1, 2 and 3 emissions?
The three different “scopes” relate to the different ways that extractive companies (or a specific project or the sector more broadly) can cause greenhouse gas emissions.
- “Scope 1” emissions are those that the company causes directly, e.g., through burning fossil fuels or failing to stop leaks of greenhouse gases from its infrastructure.
- “Scope 2” emissions are those that the company causes indirectly through purchases of electricity, steam, heat or cooling (e.g., they could come from fossil fuels that were burned to produce electricity that the company purchases).
- “Scope 3” are the emissions caused by the use of the products and services that the company sells to others. For an oil company, this would include the emissions caused by eventual burning of the fuel produced by the oil company, e.g., in a car or airplane.
Impacts of increasing carbon prices on producing countries
Across the world, governments, customers and investors are all increasing pressure on the extractive industries to reduce emissions from their operations and from their products. These efforts include the rise of carbon pricing, through which governments apply financial penalties to companies/individuals for their greenhouse gas emissions , and discourage the use of fossil fuels. For example, from 2018 to 2021, countries accounting for 80 percent of global energy use increased their average carbon price by around 17 percent. And World Bank data suggest that carbon prices increased further in 2021 and 2022.
This continues a long-term trend. From 2012 to 2018, carbon prices and the share of emissions that they covered had also increased. And an increasing number of countries (e.g., Canada, Norway, EU members) plan to bring in new carbon prices, or increase existing ones. As noted above, the EU’s CBAM even extends the EU’s carbon prices to cover emissions that occurred outside the EU during the production of the bloc’s imports of certain products. This could leave mineral-rich countries exporting to the EU worse off. As one of us has argued elsewhere, such countries should consider implementing their own carbon prices, both for the wider benefits they carry and to eliminate or reduce payments to the EU under the CBAM and potentially under the similar schemes being considered by Canada, the U.K. and the U.S. (though not necessarily with the same sectoral coverage).3
Increased carbon prices could further reduce demand for fossil fuels, leading to a lower market price which in turn could make many oil and gas projects unprofitable. Higher carbon prices will put most pressure on producers of the dirtiest fuels—coal, but also heavier, more carbon-rich oils, the burning of which generates the most emissions, requiring the highest payments of carbon prices, when compared with other fuels. Extra-heavy oils are estimated to emit at least 24 percent more CO2 when burned than light oils. Projects that are both high-cost (meaning that the commodity costs more per unit to extract) and highly carbon-intensive may struggle to be competitive in the future. Governments should therefore be wary of investing public money into development of such projects.
Importance of reducing emissions from extractive operations for future investment and revenues
While measures in extractives-importing countries such as the EU’s CBAM do not currently target emissions from the process of getting the imported oil, gas and minerals out of the ground in the first place. this could soon change. For example, the International Energy Agency and the OECD have called for fossil fuel importing countries to adopt standards on leaks of methane from extraction of the oil and gas that they import.4
The European Union has decided to leverage its position as the largest importer of oil and gas to reduce supply chain emissions of methane from the fossil fuels that the bloc imports. To do so, it will oblige countries from which it imports oil, gas and coal to apply the same monitoring, reporting and verification requirements that fossil fuel producers inside the bloc will have to meet. The European Union will also set a maximum methane emission intensity to the oil, gas and coal that it uses starting in 2030. EU member states will have the power to fine importers who do not respect these limits and monitoring, reporting and verificaiton measures. The bloc is also looking to coordinate this approach to methane emissions with other fossil fuel importers. Such approaches could make it harder for producers with the highest levels of methane leaks to achieve a high market price for their fossil fuel exports (unless they are able to reduce these leaks). Governments in producing countries should act to cut emissions from their extractive industries now, instead of leaving it too late and seeing exports suffer once importing countries implement such measures and producers scramble to make changes.
Similarly, investors and customers are pressuring the extractive industries to clean up or lose business or investment. Analysts consider low-carbon oil, gas and mining projects more likely to receive funding than higher-emission projects. And over the longer term, institutional investors expect high-emission oil and gas projects to no longer be viable. Even though for most countries, the bulk of the emissions from their oil and gas comes from burning the fuels upon end use, differences between countries’ supply chain emissions from producing oil and gas vary significantly, as shown in figures 1 and 2 below.5 ,6 These variations in supply chain emissions can add significantly to total emissions (supply chain plus end use) as well. Based on estimates from the Global Registry of Fossil Fuels, total emissions per barrel of oil from countries with the highest supply-chain emissions (top 25 percent) are over 60 percent higher than oil from countries with the lowest supply-chain emissions (bottom 25 percent). The equivalent figure for gas is over 90 percent.
Figure 1. Estimated emissions from oil supply chains7 ,8

Figure 2. Estimated emissions from gas supply chains9 ,10

NB: Yellow bars indicate countries where NRGI has programs and/or are highlighted for other reasons (see footnote 7 for an explanation).
Emissions can also vary significantly between projects in the same country, so some projects within a country may be “competitive” in terms of emissions, while others are not.11
In some cases, policymakers may be able to close this gap. For example, according to McKinsey, the oil and gas sector can reduce its operational emissions by over half at an average cost of less than $50 per ton of carbon dioxide equivalent in greenhouse gas emissions, which may be commercially viable for many projects. Methane accounts for 46 percent of emissions from oil and gas operations. It can be particularly strategic to focus on cutting methane emissions because of the gas’s potency–over a 20-year time horizon, it warms the climate 80 times as much as CO2. This is especially the case because existing technologies can already cut methane emissions from oil and gas production by 70 percent; and around 40 percent of methane emissions from oil and gas could be cut at no net cost by capturing and selling gas that would otherwise be wasted.12 It is also the main source of greenhouse gas emissions from mining; techniques exist to cut methane emissions from that sector too.
To date, a key issue holding back efforts to cut methane emissions has been that companies have lacked incentives to bring them down; even if the cost of cutting methane emissions can be recouped through savings, the “return on investment” may be insufficient to encourage companies to do so. For projects that are not very profitable and cannot afford to bring operational emissions down from a high level, ceasing production, and international incentives to do so, should also be considered.
Those resource-rich countries that move first and fastest to decarbonize their extractive sectors may acquire an edge. This may be particularly true for those with newer facilities that can be designed for low emissions intensities from the start, rather than having to retrofit old infrastructure. For fossil fuel producers, this may help them to be among the “last producers standing” as the world cuts the use of fossil fuels, with importers buying from those sources with the lowest emissions.
Resource-rich countries’ efforts to decarbonize extractive operations
In response to the dynamics identified above some resource-rich countries are starting to cut emissions from their extractive industries.
For example, one of the main sources of emissions from upstream extractives is gas flaring (see above for an explanation) which accounts for around 10 percent of the total emissions from oil and gas production, processing and transport.13
Colombian national oil company Ecopetrol reduced flaring steadily from 2012 to 2021, achieving an estimated 60 percent reduction in flared gas per barrel produced. Colombia has also adopted a specific regulation to cut methane emissions from the sector in 2022. Governments in 10 of the 12 countries where NRGI operates programming have committed to contribute to cutting global methane emissions by 30 percent by 2030.14 In addition, Mexico committed to spend USD 2 billion to reduce methane emissions from oil and gas exploration by 98 percent. Chile, Colombia and Mexico have also introduced carbon pricing, which should encourage extractive industries to cut the use of fossil fuels in their operations. Companies have also tried to limit the emissions from the planned East Africa Crude Oil Pipeline in Uganda and Tanzania by powering it with solar energy (though substantial environmental issues remain).
Roles for civil society and other stakeholders
Much work remains for those seeking to reduce emissions from extractive industry operations. Notwithstanding various stated commitments of companies and governments, and international pledges of financial and technical support, progress has been slow or otherwise disappointing. For example, in Nigeria, although gas flaring substantially decreased between 2000 and 2012, the level of flaring per barrel of oil produced barely changed after that, despite a commitment from the government in 2016 to eliminate routine flaring by 2030.15 ,16 And as international oil companies sell off their most-polluting assets, these have sometimes been bought by companies with lower environmental standards, leading to higher emissions.
Increased transparency and accountability will be important in ensuring greater engagement with the issue and to push governments, companies and investors to take the necessary action. At the international level, the Extractive Industries Transparency Initiative (EITI) has taken an important step, with the revised EITI Standard encouraging extractive-sector companies to publish project-level greenhouse gas emissions from oil, gas and mining projects. This will help governments and citizens assess which projects are most at risk of becoming uncompetitive due to high emissions and how to respond.
At the national level, more effective engagement by a broader set of actors can “move the needle” on emissions from extractive operations. This engagement will be more likely if stakeholders understand that reducing emissions from extractive sector operations is not just about countering climate change, but also related to other national priorities such as protecting government revenues and reducing harms to the health and environment of local communities. With that orientation, civil society, local community groups and concerned citizens can push governments (and businesses) to sufficiently prioritize emissions minimization, including by strengthening the regulatory framework and its enforcement. Looking beyond climate change at this broader set of reasons to cut extractive sector emissions can also increase civil society interest and capacity to campaign effectively on the issue of extractive sector operations emissions. This broader engagement will be important for resource-rich countries to effectively respond to the increasing challenge to cut emissions from extractive operations.
Acknowledgements
The authors would like to thank Paul Bagabo, Lee Bailey, Fernanda Ballesteros, Tengi George-Ikoli, Antonio Hill, Alexandra Malmqvist, David Manley, Valérie Marcel, Juliana Peña Niño, Rob Pitman, Thomas Scurfield, Ricardo Troncoso, Daniel Wilde and Nicola Woodroffe for very helpful comments.
Notes
-
1
Authors’ analysis based on “Greenhouse Gas Emissions from Energy Data Explorer”, International Energy Agency, 2 August 2023, www.iea.org/data-and-statistics/data-tools/greenhouse-gas-emissions-from-energy-data-explorer. And Hannah Ritchie, Max Roser, and Pablo Rosado, “CO₂ and Greenhouse Gas Emissions,” Our World in Data, 2020, ourworldindata.org/co2-and-greenhouse-gas-emissions.
-
2
Authors’ calculations based on Hannah Ritchie, Pablo Rosado, and Max Roser, “Greenhouse Gas Emissions,” Our World in Data, 2020. And “Oil and Natural Gas Supply,” IEA, 2022, www.iea.org/reports/oil-and-natural-gas-supply. Quoted in African Natural Resources Management and Investment Centre, Minimising Greenhouse Gas Emissions in the Petroleum Sector: The Opportunity for Emerging Producers (Abidjan, Côte d’Ivoire: African Development Bank, 2022), 14, www.newproducersgroup.online/wp-content/uploads/2022/11/Minimising-Greenhouse-Gas-Emissions-in-the-Petroleum-Sector.pdf.
-
3
In order to ensure greater international equity in the energy transition, authorities in countries implementing schemes such as the EU’s CBAM should include, in or alongside such schemes, measures to mitigate their negative effects on low and middle-income countries, e.g., through financial and/or technical assistance to help such countries green their economies.
-
4
Methane is a common by-product of oil extraction and a particularly potent greenhouse gas. In the process of getting oil and gas out of the ground, it is commonly emitted either through leaks or planned release into the atmosphere – either unburned (“venting”) or burned (“flaring”). Processing (e.g., refining) and transporting oil and gas also generate significant emissions. See “Methane from Oil and Gas Production Explained,” The World Bank - Global Gas Flaring Reduction Partnership, accessed 24 October 2023, www.worldbank.org/en/programs/gasflaringreduction/methane-explained.
-
5
The Global Registry of Fossil Fuels is an “[O]pen-source database of oil, gas and coal production and reserves globally, expressed in CO2-equivalent… It contains data from 139 fossil fuel producing countries, which amounts to 99% of fossil fuel production aggregated to the national level.” The database also provides estimates of the emissions from producing oil and gas in 91 oil producing countries and 71 gas producers. See “Global Registry of Fossil Fuel Emissions and Reserves”, Global Registry of Fossil Fuels, accessed 4 September 2023, fossilfuelregistry.org.
-
6
Figures 1 and 2 show a selection of countries, including some of the world’s larger oil producers, some of the world’s lower emitting producers as well as a selection of countries where NRGI operates. This is intended to provide reference points to explore whether individual countries will be more or less “carbon-competitive” than other producers based on current intensities and identifying potential examples of good practice among lower emitting producers. We also include a selection of higher-emitting producers, which may provide examples of practices to avoid.
-
7
Source: “Carbon Intensity in the Fossil Fuel Supply Chain”, Global Registry of Fossil Fuels, 2023, fossilfuelregistry.org/carbon-intensity. Global Warming Potential (GWP) 20 is applied to methane emissions; see “Methane and Climate Change,” IEA, accessed 4 September 2023, www.iea.org/reports/methane-tracker-2021/methane-and-climate-change. The impact would be smaller if we used Global Warming Potential 100. The impact over the next 20 years is important and sufficient to justify action on cutting upstream emissions (and using GWP 100 would fail to show this); this is why we have chosen to display GWP 20 in this figure and figure 2. For further discussion, see Janos Maté and David Kanter, “The Benefits of Basing Policies on the 20 Year GWP of HFCs” (Greenpeace, 2011), ozone.unep.org/system/files/documents/Benefits%20of%20Basing%20Policies%20on%2020%20GWP%20of%20HFCs.pdf.
-
8
The world’s largest oil producers are the United States (accounting for 21 percent of global production), Saudi Arabia (13 percent) and Russia (10 percent). See “Frequently Asked Questions (FAQs) - What Countries Are the Top Producers and Consumers of Oil?”, U.S. Energy Information Administration (EIA), 22 September 2023, www.eia.gov/tools/faqs/faq.php?id=709&t=6.
-
9
Source: “Carbon Intensity in the Fossil Fuel Supply Chain.”
-
10
The world’s largest (fossil) gas producers are the United States (accounting for 25 percent of production), Russia (17 percent) and Iran (6 percent). See “Natural Gas Production”, Enerdata World Energy & Climate Statistics - Yearbook 2023, accessed 4 September 2023, www.doi.org/yearbook.enerdata.net/natural-gas/world-natural-gas-production-statistics.html. And Statista Research Department, “Natural Gas Production Worldwide from 1998 to 2022”, Statista, 29 August 2023, www.statista.com/statistics/265344/total-global-natural-gas-production-since-1998.
-
11
RMI provides data on supply chain emissions by oil and gas project. See RMI, “Assessing Global Oil and Gas Emissions”, Oil Climate Index plus Gas, 2023, ociplus.rmi.org.
-
12
Some initiatives to capture methane emissions can have a positive net present value for companies. See Chantal Beck et al., “The Future of Oil and Gas Is Now: How Companies Can Decarbonize,” McKinsey & Company, 7 January 2020, www.mckinsey.com/industries/oil-and-gas/our-insights/the-future-is-now-how-oil-and-gas-companies-can-decarbonize.
-
13
Authors’ calculations based on Tomas de Oliveira Bredariol and Christophe McGlade, “Fossil Fuels,” IEA, 11 July 2023, www.iea.org/energy-system/fossil-fuels. And Tomas de Oliveira Bredariol and Christophe McGlade, “Gas Flaring,” IEA, accessed 15 September 2023, www.iea.org/energy-system/fossil-fuels/gas-flaring.
-
14
This is a 30 percent cut relative to 2020 levels.
-
15
Authors’ analysis based on Rebecca Schulz, Christophe McGlade, and Peter Zeniewski, “Putting Gas Flaring in the Spotlight,” IEA, 9 December 2020, www.iea.org/commentaries/putting-gas-flaring-in-the-spotlight. And “Nigeria,” The World Bank, June 2022, flaringventingregulations.worldbank.org/nigeria.
-
16
In 2022 Nigeria’s government “[I[ssued guidelines to support the elimination of routine gas flaring by 2030 and a 60 percent reduction in fugitive methane emissions by 2031.” “Methane Abatement,” IEA, accessed 2 October 2023, www.iea.org/energy-system/fossil-fuels/methane-abatement.